


Where to Buy
Cuellar Farms is stocked at 31 licensed dispensaries across Oregon, with the deepest coverage in Portland, Salem, Corvallis, Medford, and Beaverton. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
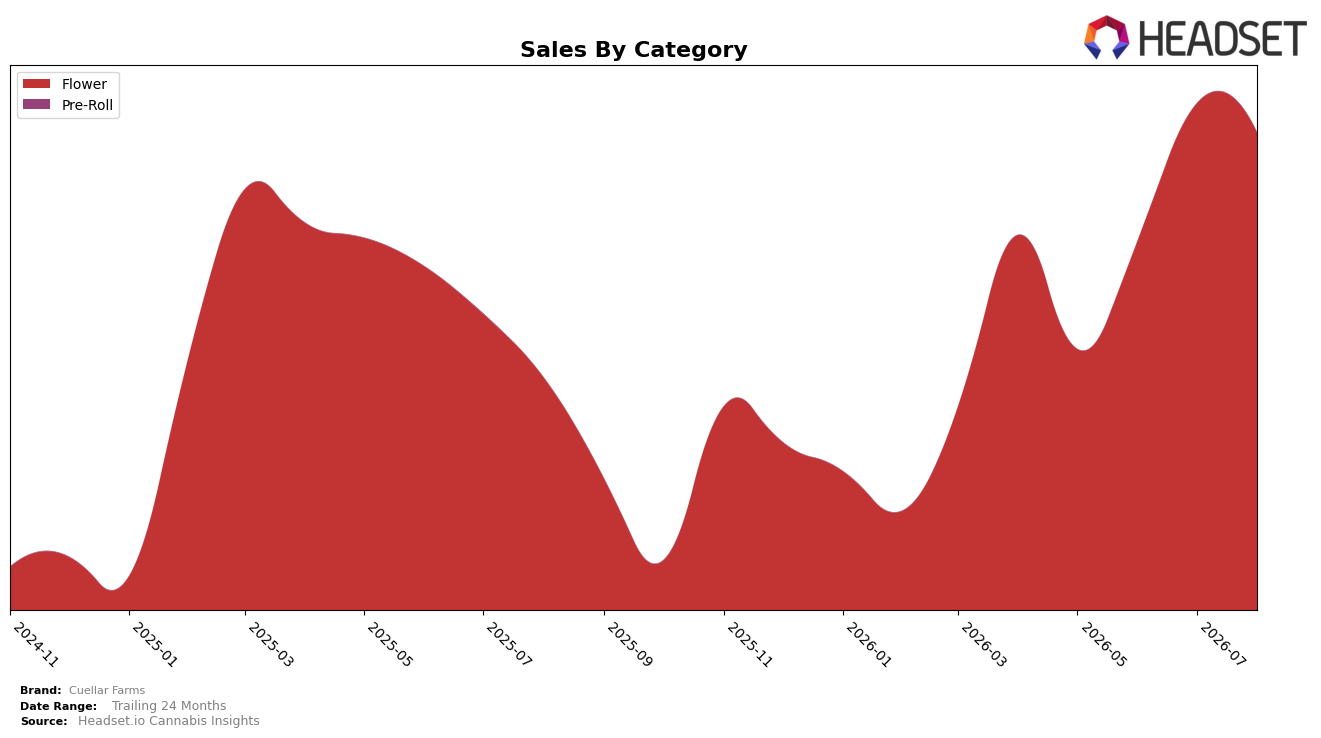
Cuellar Farms operated as a single-category brand in August 2026 with Flower accounting for 100.0% of sales, pairing a 105.5% year-over-year gain with a 5.8% month-over-month decline, and holding an average price down 22.3% versus last year. Within the Oregon Flower landscape, the brand sat at rank 34 in August 2026, indicating the price-reset strategy is trading unit velocity for position stability even as monthly sales tapered.
The combine of a 22.3% price reduction and 105.5% year-over-year sales growth alongside a 5.8% month-over-month dip implies Cuellar Farms is leaning on accessible price points to expand penetration while absorbing seasonal or assortment-driven pullback into late summer. Concentration in Flower at 100.0% share limits diversification, so maintaining rank 34 in Oregon depends on sustaining unit gains at the lower price tier and mitigating volatility that produced the August 2026 month-over-month decline.
Competitive Landscape
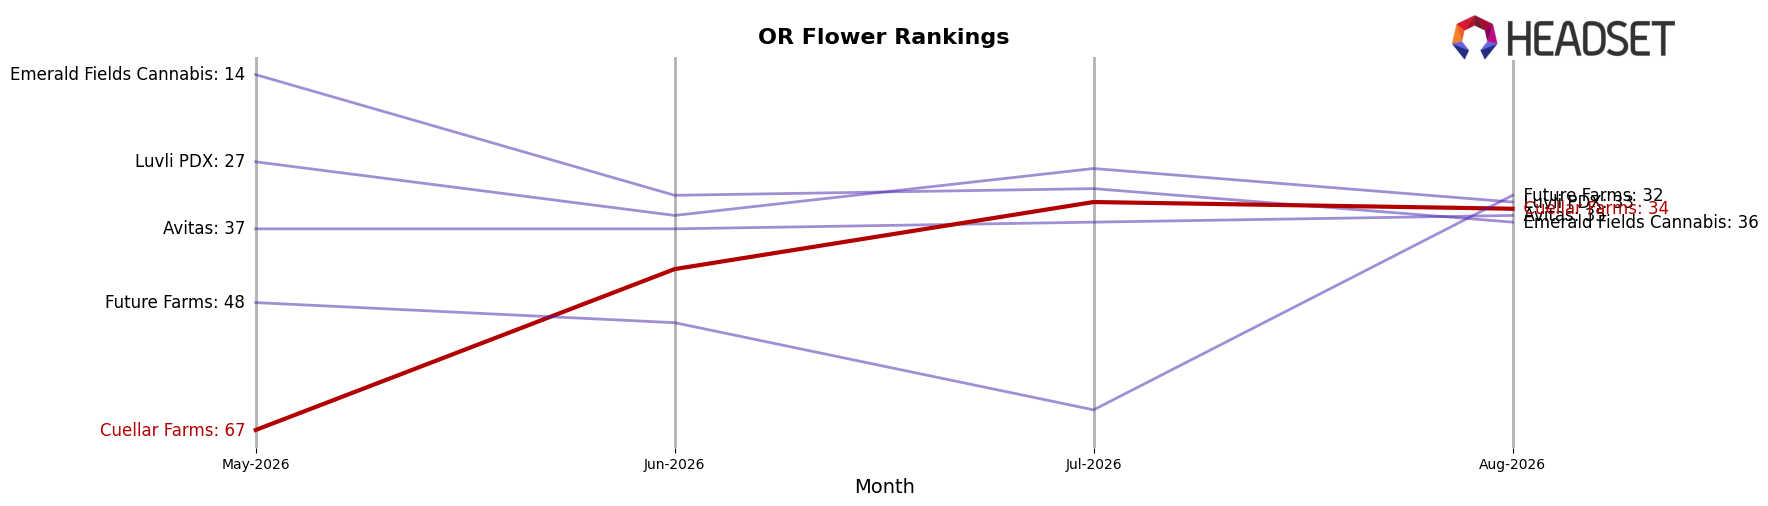
Cuellar Farms sits at rank #34 in OR Flower in August 2026, improving 46 positions year over year from #80, and edging up 33 places since May 2026 from #67; the brand also briefly peaked at #33 in July 2026, indicating a one-rank slip month over month. Against leaders, Grown Rogue moved from #3 to #1 with a 49.1% YoY sales gain while Oregrown advanced from #23 to #3 on 182.4% YoY growth, and Panda Farms vaulted from #99 to #4 alongside 1,059.6% YoY growth; by contrast, PRUF Cultivar / PRŪF Cultivar slipped from #1 to #2 with a 17.2% YoY sales decline. The pattern—rapid YoY climb from #80 to #34 but flatlining near the low-30s in July–August—implies Cuellar Farms is transitioning from recovery into a consolidation phase where incremental share gains will require displacing competitors that are accelerating ranks faster.
Notable Products
Blueberry Muffin #4 (Bulk) held rank 1 in August 2026 with a month-over-month change of +26.6%, while Red Mandarine (Bulk) moved to rank 2 with +37.9%, indicating that the highest absolute mover stayed within Flower and that gains below +50% were sufficient to reshape the top two. Two of the top two SKUs are Flower, and with no top-10 presence from other listed SKUs in the same family, the concentration suggests a narrow set of winners rather than broad portfolio lift. Red Mandarine (Bulk) at rank 2 with +37.9% MoM and Blueberry Muffin #4 (Bulk) at rank 1 with +26.6% together delivered $177,388, implying that August 2026 revenue leaned on a pair of flagship Flower offerings rather than diversification.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

