
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Fenario is stocked at 57 licensed dispensaries across Oregon, with the deepest coverage in Eugene, Bend, Portland, Corvallis, and Brookings. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
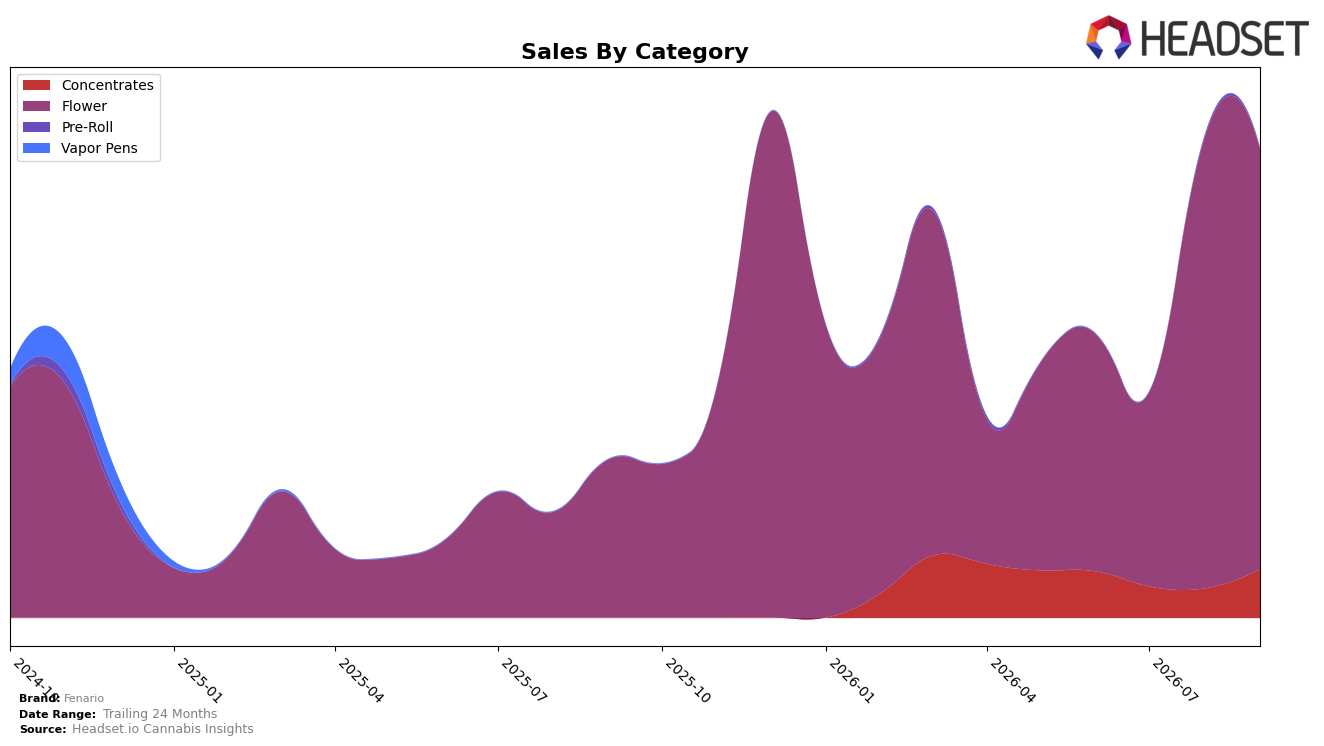
Fenario concentrated 89.38% of September 2026 sales in Flower while holding 10.34% in Concentrates and just 0.28% in Pre-Roll, a mix that coincided with a 166.43% year-over-year surge in Flower but a 6.87% month-over-month pullback, alongside a 65.73% month-over-month jump in Concentrates. With average prices up 54.15% year over year to $31.50 and Flower’s average at $31.77, the brand lifted total year-over-year sales by 198.07% even as Pre-Roll fell 22.86% month over month. The thesis is that Fenario’s outsized reliance on Flower amplified YoY gains but also increased monthly volatility, with Concentrates acting as the near-term offset to September’s Flower dip.
Positioning-wise, the category skew places Fenario as a Flower-first brand ranked 48 in Flower within Oregon, where a 6.87% monthly Flower decline contrasts with a 65.73% monthly rise in Concentrates, implying a deliberate hedge into higher-value extracts as prices climbed 54.15% year over year. Given a 10.34% sales share in Concentrates versus 89.38% in Flower, the pattern suggests headroom to rebalance mix for steadier month-to-month performance while maintaining the YoY momentum driven by a 166.43% Flower increase.
Competitive Landscape
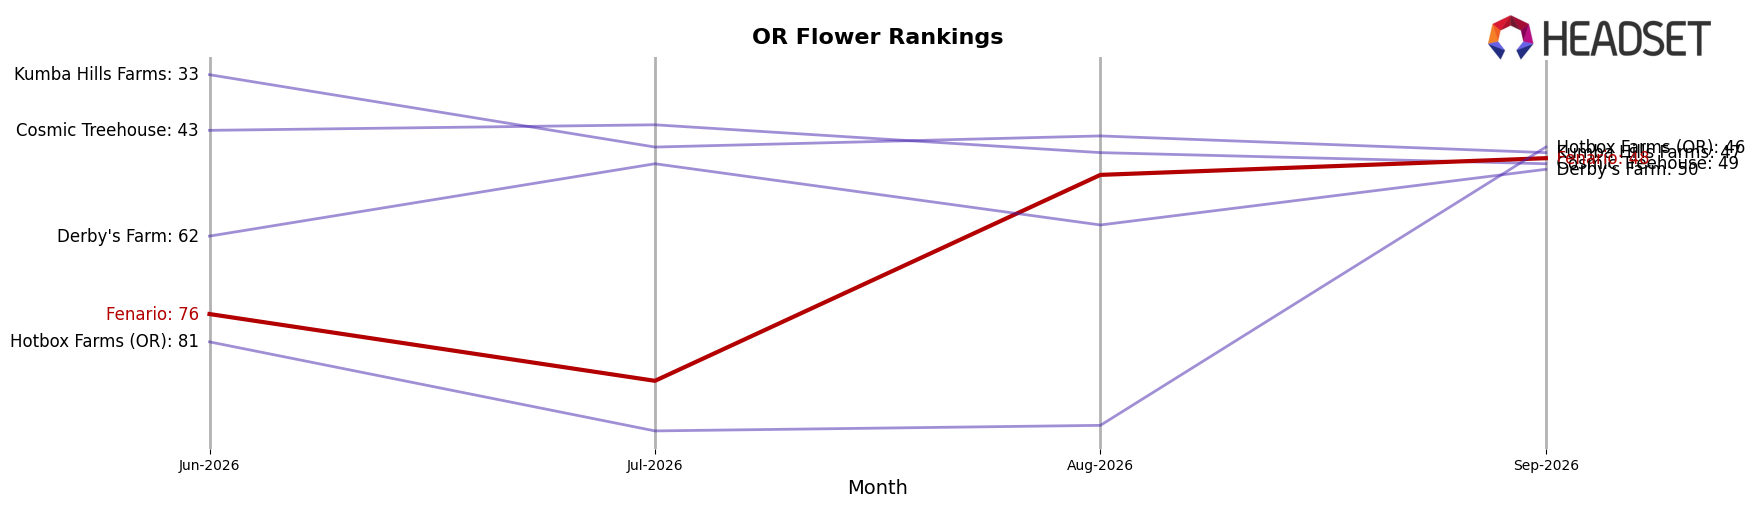
Fenario sits at rank #48 in OR Flower for September 2026, improving 58 positions year over year from #106 and rising 28 spots since June 2026 from #76, while still trailing its peak at #42 reached in December 2025. In contrast, Grown Rogue moved up to #1 from #3 with a 63.8% year-over-year sales gain, and Oregrown advanced to #3 from #16 alongside a 169.7% year-over-year increase, indicating that Fenario’s mid-pack climb is occurring as top competitors accelerate faster at the top of the rankings. The pattern implies Fenario’s rank trajectory is recovery-oriented but will require share-capturing moves to convert a rebound from #106 to #48 into durable top-40 re-entry.
Notable Products
Humboldt Uppercut (3.5g) posted the steepest decline in September 2026 with a -60.7% MoM drop as it slid to rank 8, while Triple Burger (Bulk) fell -22.6% yet held rank 1. In contrast, Humboldt Uppercut (Bulk) surged +246.2% MoM to rank 6, and Super Boof (3.5g) rose +50.5% MoM at rank 5. With eight of the top ten being Flower SKUs and one format of Humboldt Uppercut collapsing as the bulk format accelerated, the pattern implies a shift toward bulk-driven velocity and away from smaller pack sizes, concentrating Fenario’s near-term gains in high-volume Flower.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

