

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Arise Cannabis is stocked at 69 licensed dispensaries across Oregon and Washington, 66 of them in Oregon, with the deepest coverage in Portland, Salem, Eugene, Bend, and North Bend. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
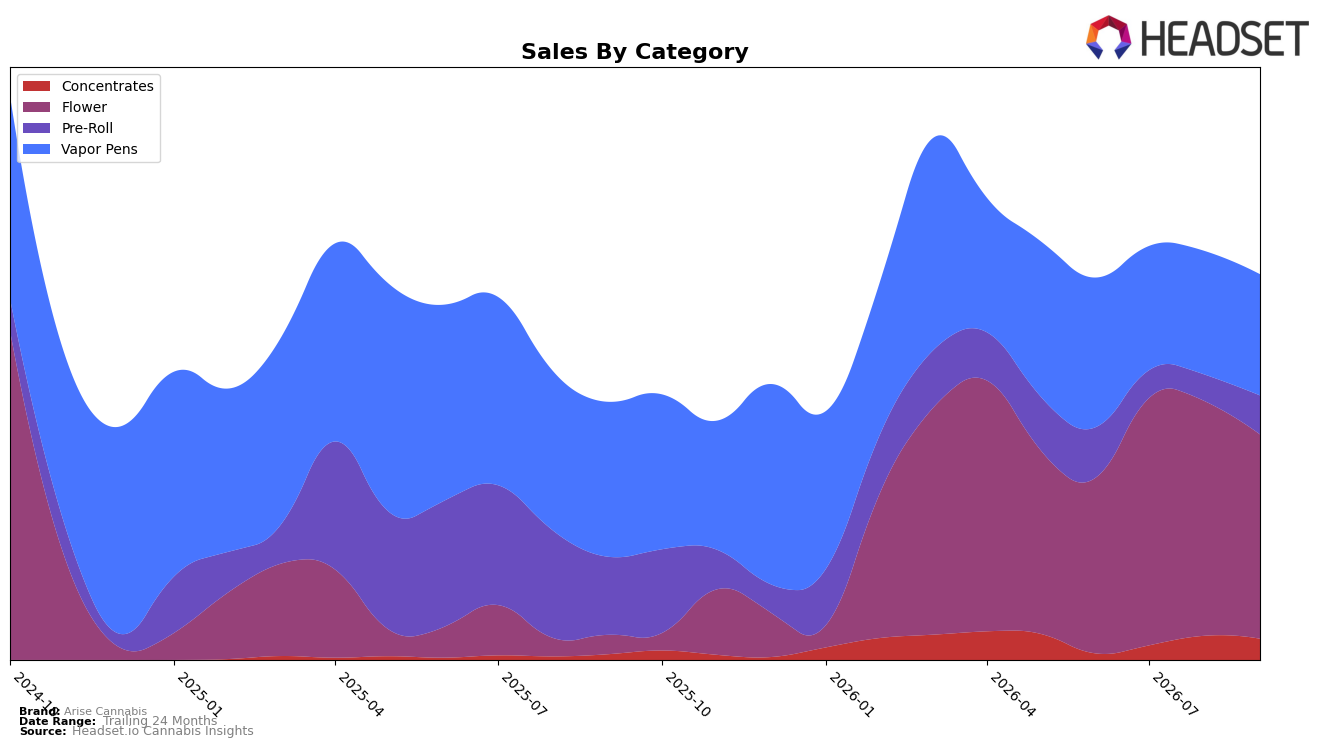
Arise Cannabis shifted heavily into Flower in September 2026, with category share at 53.0% and year-over-year sales up 971.4%, while month-over-month dipped 12.9%; by contrast, Vapor Pens held 31.4% share with year-over-year down 21.8% and month-over-month down 1.9%. Pre-Roll contributed 10.1% share with year-over-year down 50.2% but month-over-month up 47.3%, and Concentrates at 5.5% share rose 270.1% year-over-year but fell 12.2% month-over-month. Average price dropped 36.2% year-over-year to $11.07 alongside a category-leading mix weight in Flower, and within Oregon Flower the brand held rank 60, indicating the volume surge is tied to price compression and a pivot toward higher-share but lower-priced formats.
The combination of a 971.4% Flower surge and a 36.2% average price decline suggests Arise Cannabis is leaning into value-led Flower to drive velocity, while a 21.8% Vapor Pens decline and a 50.2% Pre-Roll contraction year-over-year point to selective deprioritization of premium and impulse formats; the 47.3% month-over-month rebound in Pre-Roll implies targeted promos or distribution wins rather than a structural shift. Holding rank 60 in Oregon Flower with a 12.9% month-over-month Flower dip and a 12.2% month-over-month decline in Concentrates indicates positioning as a price-accessible Flower player with episodic Pre-Roll pushes, implying near-term share gains will depend on sustaining low-price Flower while stabilizing pen declines.
Competitive Landscape
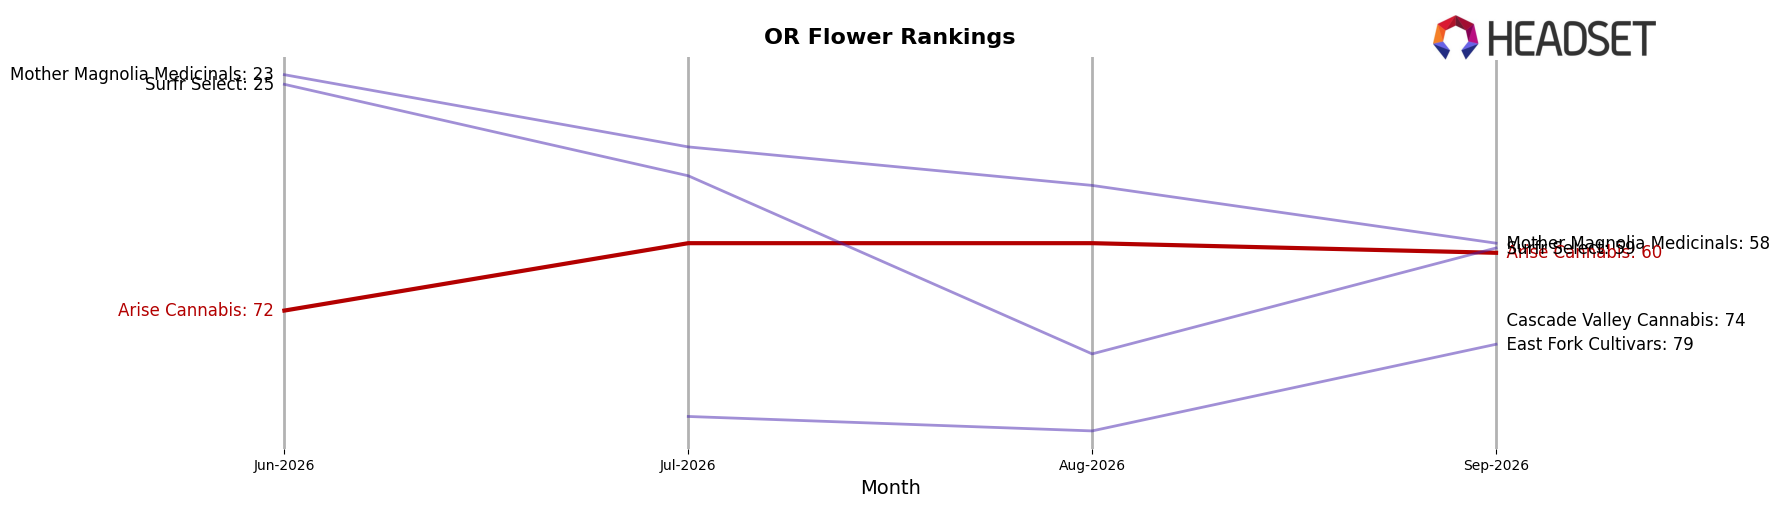
Arise Cannabis is ranked #60 in OR Flower in September 2026, improving 169 positions year over year from #229 and rising 12 ranks from #72 in June 2026, while still trailing its peak of #45 from October 2024; meanwhile, Grown Rogue moved up to #1 from #3 with 63.8% YoY sales growth and Oregrown advanced to #3 from #16 with 169.7% YoY growth, indicating that Arise Cannabis’s rank recovery is occurring alongside faster-moving leaders and implies the brand’s current trajectory points to mid-tier stabilization rather than a return to its prior top-50 position without a step-change in velocity.
Notable Products
Chocolate Moonshine (1g) posted the steepest decline at -64.4% month over month while slipping to rank 7, and Purple Churro (1g) fell -44.9% yet still held rank 1; this pairing indicates demand concentrated at the top is eroding faster than the leaderboard can reshuffle. In contrast, Blackwater OG (1g) rose +18.4% to rank 2 as Flower SKUs occupied 6 of the top 10 positions, implying the category remains the volume anchor even as individual strains swing sharply. With Pre-Roll entries clustered at ranks 6–9 but without measurable month-over-month gains and only $9,545 attached to the best-moving Flower SKU, the mix points to a reliance on Flower leadership that is vulnerable to volatility rather than diversified momentum.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

