
Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
For The Flavor is stocked at 38 licensed dispensaries across Washington, with the deepest coverage in Olympia, Seattle, Tacoma, Bremerton, and Lacey. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
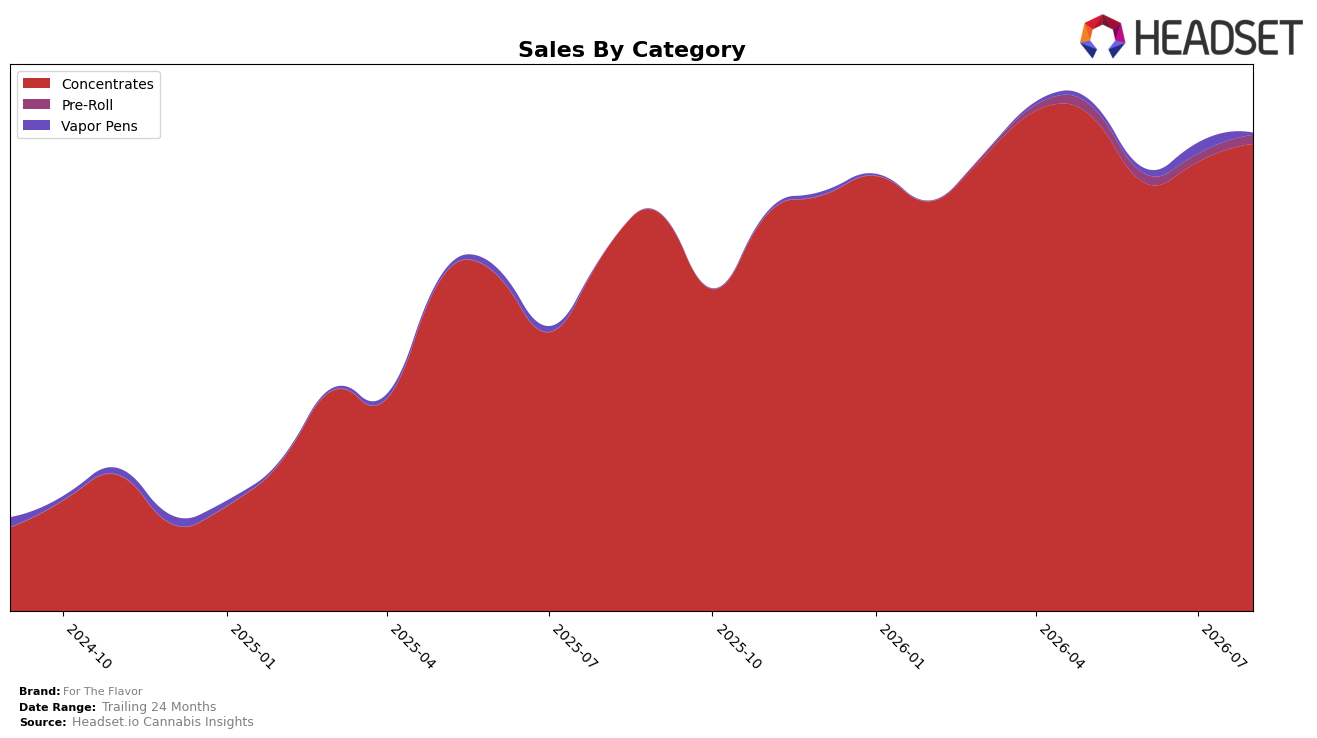
For The Flavor remained overwhelmingly concentrated in Concentrates during August 2026, with a 97.81% category share and a 30.55% year-over-year gain alongside a 4.04% month-over-month increase, while the average price rose 1.84% YoY to $9.32. Pre-Roll expanded to 1.81% share with an 8.93% MoM lift, whereas Vapor Pens contracted to 0.38% share on an -83.09% MoM decline; the category anchor still posted a rank of 35 in Concentrates in Washington. The pattern implies a deliberate deepening in the core Concentrates franchise while testing small adjacent bets, with price stability supporting share defense even as ultra-minor formats diverge sharply in momentum.
These shifts suggest positioning as a Concentrates-first specialist that can tolerate volatility in fringe formats: rising Concentrates share at 97.81% alongside a 4.04% MoM uptick indicates prioritization of repeatable turns, while Pre-Roll’s 8.93% MoM growth provides a low-risk diversification wedge against Vapor Pens’ -83.09% MoM drag. Holding rank 35 in Concentrates within Washington while delivering 30.55% YoY growth signals that incremental distribution or assortment depth, rather than broad category spread, is the near-term lever, implying the brand’s optimal path is to consolidate in high-velocity Concentrates while selectively scaling Pre-Roll to buffer category cyclicality.
Competitive Landscape
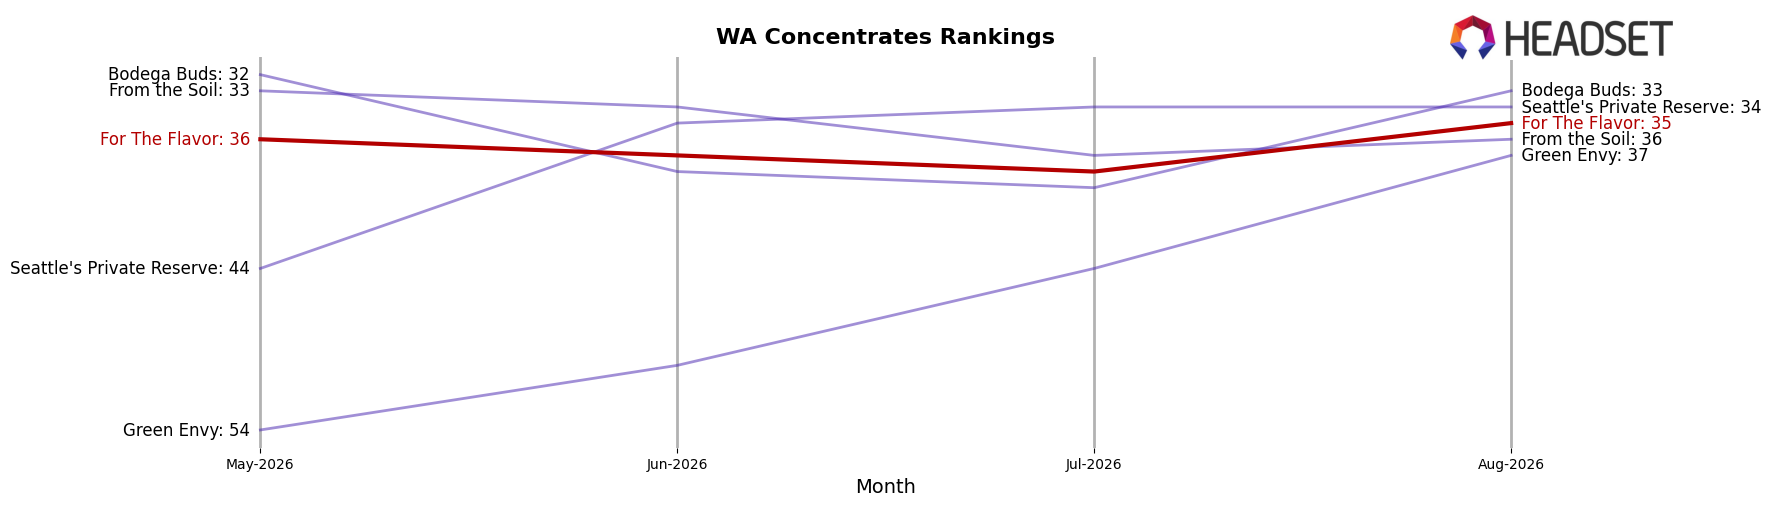
For The Flavor sits at rank 35 in Washington Concentrates in August 2026, improving 13 positions from rank 48 year over year, and nudging up 1 spot from rank 36 three months ago; this new rank also matches its peak at 35 in August 2026, indicating a ceiling test. Against market leaders, Ooowee held at rank 1 while its sales fell 6.1% year over year, and Constellation Cannabis advanced from rank 6 to rank 4 on 15.9% sales growth, suggesting incumbents are either flat or advancing; meanwhile, Buddy Boy Farms surged from rank 56 to rank 5 alongside a 456.9% sales increase, showing rapid share consolidation above the mid-tier. The combination of a 13-rank YoY climb and a 1-rank lift since May 2026 implies For The Flavor is improving but may need sharper velocity gains to break past a mid-30s plateau amid faster-moving rivals.
Notable Products
Banana Cream Cake Live Resin (1g) posted the standout move in August 2026 with +72% MoM to rank 2, while Popsicles Cured Resin (1g) climbed +63% MoM to rank 3, indicating momentum is concentrated in a narrow band just below the category leader. Hallie Berry Cured Resin (1g) held rank 1 with +31% MoM, but its growth lagged the +63% to +72% cohort, implying share is accruing fastest to the mid‑table risers rather than the incumbent top SKU. With four of the top five SKUs up between +31% and +72% and all top ten positions occupied by Concentrates, the mix points to deeper commitment to single‑gram resin formats over breadth expansion, concentrating revenue in high‑velocity strains rather than diversifying into new categories.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

