
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
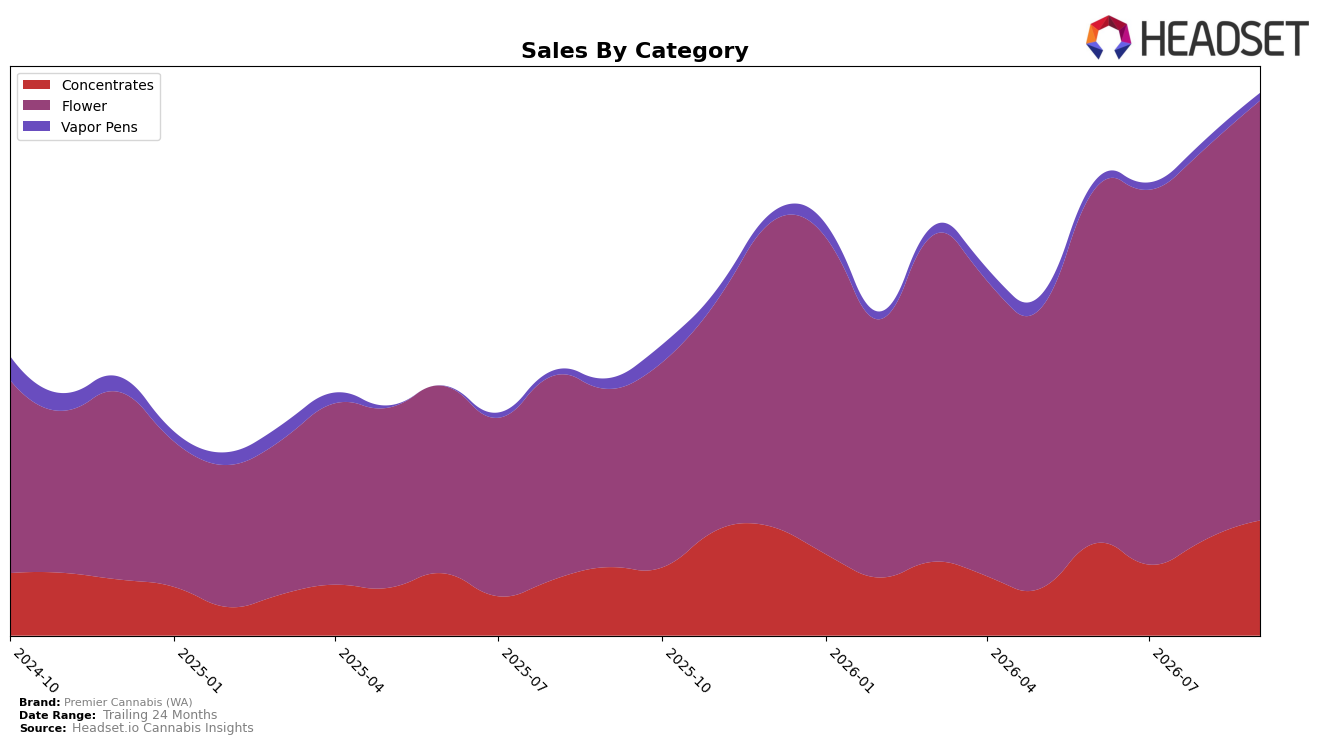
Premier Cannabis (WA) concentrated 77.31% of September 2026 sales in Flower with 135.42% year-over-year growth and 7.39% month-over-month, while Concentrates held 21.23% share with 67.90% year-over-year and 20.31% month-over-month; Vapor Pens shrank to 1.46% share with -27.42% year-over-year and -12.15% month-over-month. Against a brand-level 110.53% year-over-year sales lift and a 9.19% year-over-year average price increase to $38.94, Flower’s faster expansion and higher $40.82 average price point indicate mix-driven uplift, whereas Vapor Pens’ contraction acts as a drag; the pattern implies the brand’s current growth is anchored in WA Flower, with Concentrates emerging as the incremental volume engine.
With Flower at rank 46 in Washington and accounting for over three-quarters of mix, the 7.39% month-over-month gain alongside Concentrates’ 20.31% month-over-month rise suggests depth in core inhalables but a narrowing footprint in Vapor Pens at -12.15% month-over-month. Given Flower’s 135.42% year-over-year outpacing the brand’s 110.53% and Concentrates’ 67.90%, the portfolio is tilting toward higher-priced Flower while de-emphasizing Pens at a 1.46% share; this positioning implies near-term share stability via Flower price realization with headroom to move up from rank 46 if Concentrates scale continues and Vapor Pens are treated as a deliberate deprioritization rather than a growth lane.
Competitive Landscape
Premier Cannabis (WA) sits at rank #46 in WA Flower in September 2026, a 61-position climb from #107 year over year, and a 9-spot improvement from #55 in June 2026, marking a new peak rank of #46 in September 2026. Against category leaders, Phat Panda held #1 year over year and remains #1 with +19.0% YoY sales, while Mama J's advanced from #4 to #3 with +3.2% YoY sales; compared with these trajectories, Premier Cannabis (WA)’s 61-rank YoY jump coupled with a 9-rank quarter-over-quarter gain indicates momentum concentrated in distribution or SKU productivity rather than absolute scale, implying a transition from fringe (#107) to mid-pack (#46) that, if maintained, positions the brand to contest the #30–#40 tier next.

Notable Products
Moonbutter (3.5g) posted the steepest decline in September 2026 at -11.6% MoM while slipping to rank 4, contrasting with Wedding Cake (3.5g) up 41.4% MoM at rank 1 and Gorilla Glue #4 (7g) up 39.4% MoM at rank 7. Three SKUs rose over 33% month over month—Wedding Cake (3.5g) at 41.4%, Gorilla Glue #4 (7g) at 39.4%, and Premier Glue Fresh Pressed Live Rosin (1g) at 35.1%—but Premier Glue (3.5g) was effectively flat at +0.1% MoM while holding rank 3. With eight of the top ten in Flower and two in Concentrates, the mix implies a pivot toward scaling Flower-led velocity while selectively nurturing Live Rosin to diversify margin pools.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

