
Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
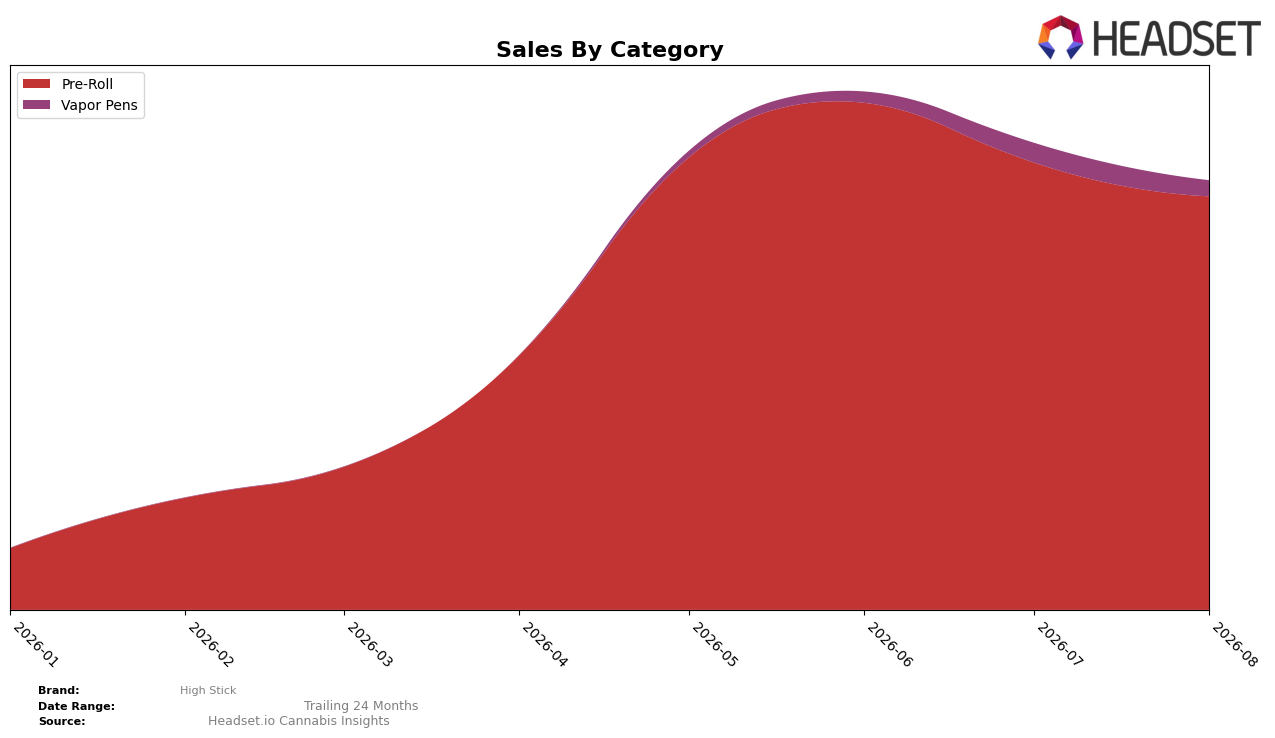
High Stick concentrated 96.34% of August 2026 sales in Pre-Roll with a 3.66% tail in Vapor Pens, while Pre-Roll average price sat at $32.29 and Vapor Pens at 35.64. Month over month, Pre-Roll contracted by 7.58% and Vapor Pens fell 18.73%, and within Pre-Roll the brand sat at rank 44 in British Columbia, indicating a mid-pack position rather than leadership. With Ontario as the top province and Pre-Roll as the top category, the mix skews heavily toward a single format; this concentration plus dual-category MoM declines implies exposure to category-specific headwinds rather than cross-format cushioning.
The 96.34% reliance on Pre-Roll alongside an 18.73% drop in the smaller Vapor Pens segment suggests limited elasticity to redirect demand when the core dips by 7.58%. Holding rank 44 in British Columbia within Pre-Roll, paired with a 3.66% share of sales in Vapor Pens, implies the brand’s positioning is anchored in value or availability within Pre-Roll rather than diversified differentiation across formats; the pattern argues for either deepening Pre-Roll distinctiveness to climb from rank 44 or building a broader mix so that month-to-month volatility in one category does not drive overall variance.
Competitive Landscape
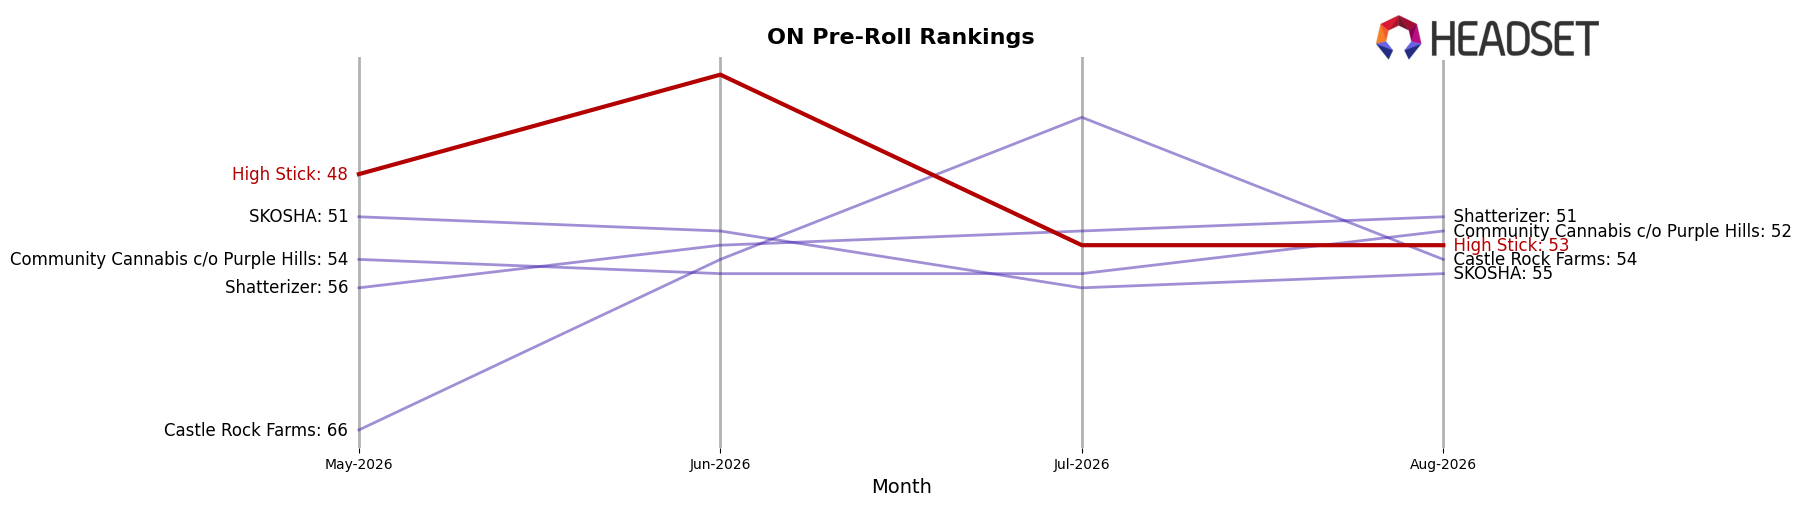
High Stick ranks #53 in ON Pre-Roll in August 2026, down 5 positions from #48 in May 2026 and 12 positions off its peak at #41 in June 2026; with no year-over-year rank available, the near-term slide contrasts with Back Forty / Back 40 Cannabis holding #1 while rising 1 place since July 2026 and logging 56.6% YoY sales growth, and diverges further from Spinach at #5 after climbing 9 spots since March 2026 alongside 81.6% YoY growth. Meanwhile, General Admission sits at #2 despite a -28.1% YoY sales change, and Jeeter is #4 with a -44.5% YoY decline, indicating that High Stick’s drop from #41 in June 2026 to #53 in August 2026 reflects a loss of relative momentum even as some top incumbents soften, implying the brand must recover share quickly or risk drifting out of the top 60 as ladder-climbers consolidate placements.
Notable Products
Cherry Picker Lemonade Liquid Diamond Infused Pre-Roll 5-Pack (2.5g) posted the steepest decline at -31.10% and slid to rank 4, while Breakaway Bubba Liquid Diamond Resin Infused Pre-Roll 3-Pack (1.5g) fell -24.73% at rank 2; in contrast, Gloves Off Grape Infused Pre-Roll (1g) rose +17.13% to rank 3 and Silky Citrus Infused Pre-Roll 3-Pack (1.5g) gained +35.29% at rank 8. Starting Five Liquid Diamond Infused Pre-Roll 5-Pack (2.5g) held rank 1 with +6.80% month over month and approximately $342,982 in August 2026, as Blue Line Razz Liquid Diamond Infused Pre-Roll 10-Pack (5g) dropped -39.15% at rank 6. With nine of the top ten in Pre-Roll, the mix points to concentration risk around multi-pack infused formats that can amplify volatility but also anchor share when a flagship holds rank 1.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

