
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
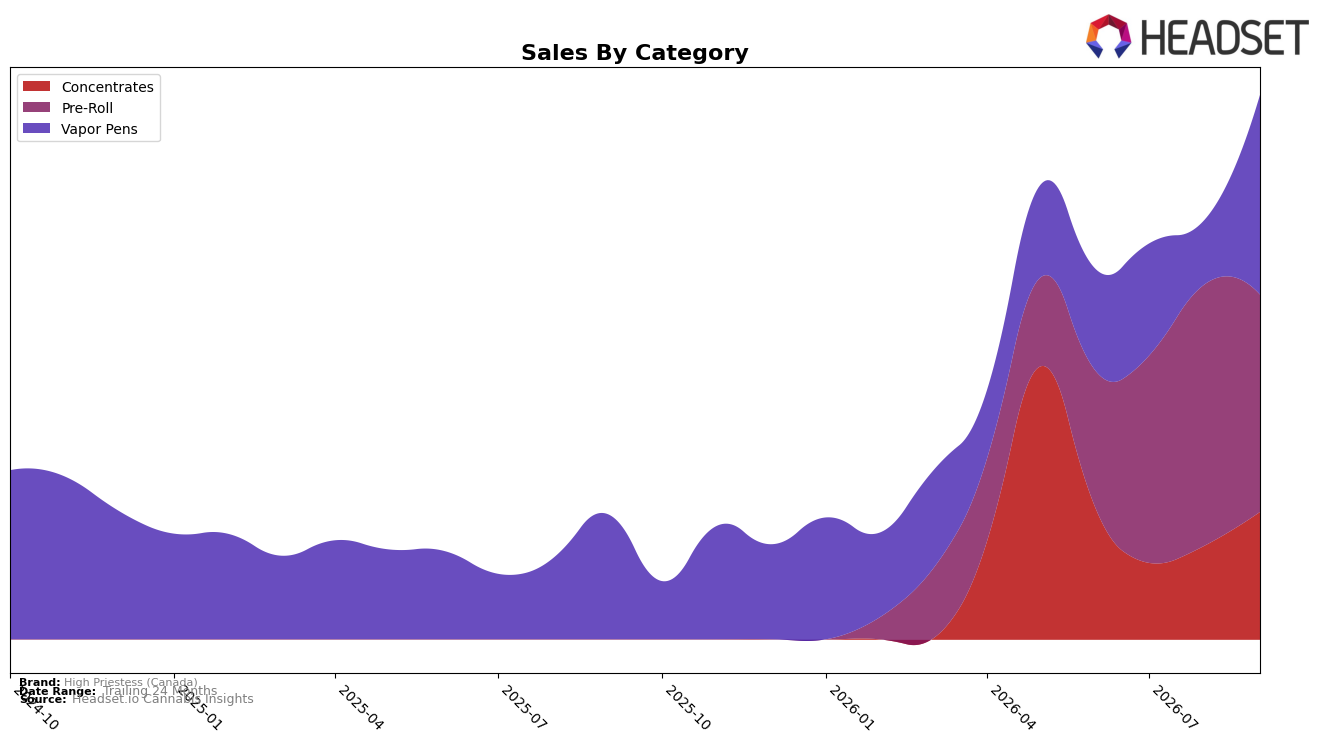
High Priestess (Canada) shifted its category mix in September 2026 toward Vapor Pens and away from Pre-Roll, with Vapor Pens jumping to 36.65% share on 209.68% month-over-month growth and 59.93% year-over-year growth, while Pre-Roll fell to 39.90% share with a 16.83% month-over-month decline. Concentrates expanded to 23.45% share on 35.89% month-over-month growth, and the brand’s average price fell 20.67% year over year even as total brand sales rose 336.38% year over year, suggesting volume-led gains. The pattern implies a deliberate pivot toward inhalables that trade higher unit velocity at lower price points, concentrating mix in faster-moving formats while trimming exposure to weaker Pre-Roll momentum.
The mix shift places the brand to compete on velocity within Vapor Pens, where its category rank in Alberta is 50, and where a 209.68% month-over-month surge can convert into sustained shelf presence if price discipline persists alongside the 20.67% year-over-year price decrease. With Concentrates adding 35.89% month-over-month growth against a 16.83% month-over-month decline in Pre-Roll, the portfolio leans into adjacent formats that can ladder consumers up from Pre-Roll without abandoning value, positioning the brand to trade customers into higher-share inhalable segments while accepting lower Pre-Roll contribution near term.
Competitive Landscape
High Priestess (Canada) sits at rank #50 in AB Vapor Pens in September 2026, improving 43 positions from rank #93 in September 2025, and rising 49 spots from rank #99 in June 2026 to reach a new peak at #50 in September 2026; meanwhile, category leaders shifted less dramatically, with BoxHot moving from #3 to #1 year over year and Back Forty / Back 40 Cannabis holding near the top from #2 to #2 while General Admission slid from #4 to #5. With category headroom visible—top players posting sales changes from +56.6% to -21.2% while High Priestess (Canada) advanced in rank without breaching the top 40—the trajectory implies a recovery phase focused on sustained share capture rather than immediate top-tier contention.

Notable Products
Gemini Sun and Moon Duo Pack Shatter Infused Pre-Roll 2-Pack (1.5g) posted the steepest decline at -20.4% and slipped to rank 3, while Aquarius Aqua Berry Resin & Diamond Infused Pre-Roll 3-Pack (1.5g) fell -10.2% at rank 2, together signaling a pullback in infused Pre-Rolls that contrasts with Taurus Vanilla Sweet Cream Live Whipped Diamonds (1.2g) rising 35.9% to rank 1. Three Pre-Rolls sit in the top six while Vapor Pens occupy ranks 4, 5, and 7, and the Libra - CBD:THC 1:1 Maui Bubble Live Resin Cartridge (1g) plunged -45.6% at rank 7, pointing to uneven demand within pens despite category presence near the top. Taurus Vanilla Sweet Cream Live Whipped Diamonds (1.2g) led revenue at $31,183 alongside the Vapor Pens Leo - Pineapple Peach Drama Live Liquid Diamond Cartridge (1g) at rank 4 and Virgo Orchard Veil Apple Live Resin Cartridge (1g) at rank 5, indicating concentrates and select pens are absorbing share as mass multi-pack Pre-Rolls like Aries Citrus Inferno Pre-Roll 10-Pack (4g) retreat -24.2% to rank 6. The pattern implies High Priestess (Canada) is tilting toward higher-potency formats and flavored cartridges while deemphasizing larger Pre-Roll formats that are losing momentum month over month.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

