

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Snackbar (IL) is stocked at 39 licensed dispensaries across Illinois, with the deepest coverage in Chicago, Schaumburg, Arlington Heights, Aurora, and Benton. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
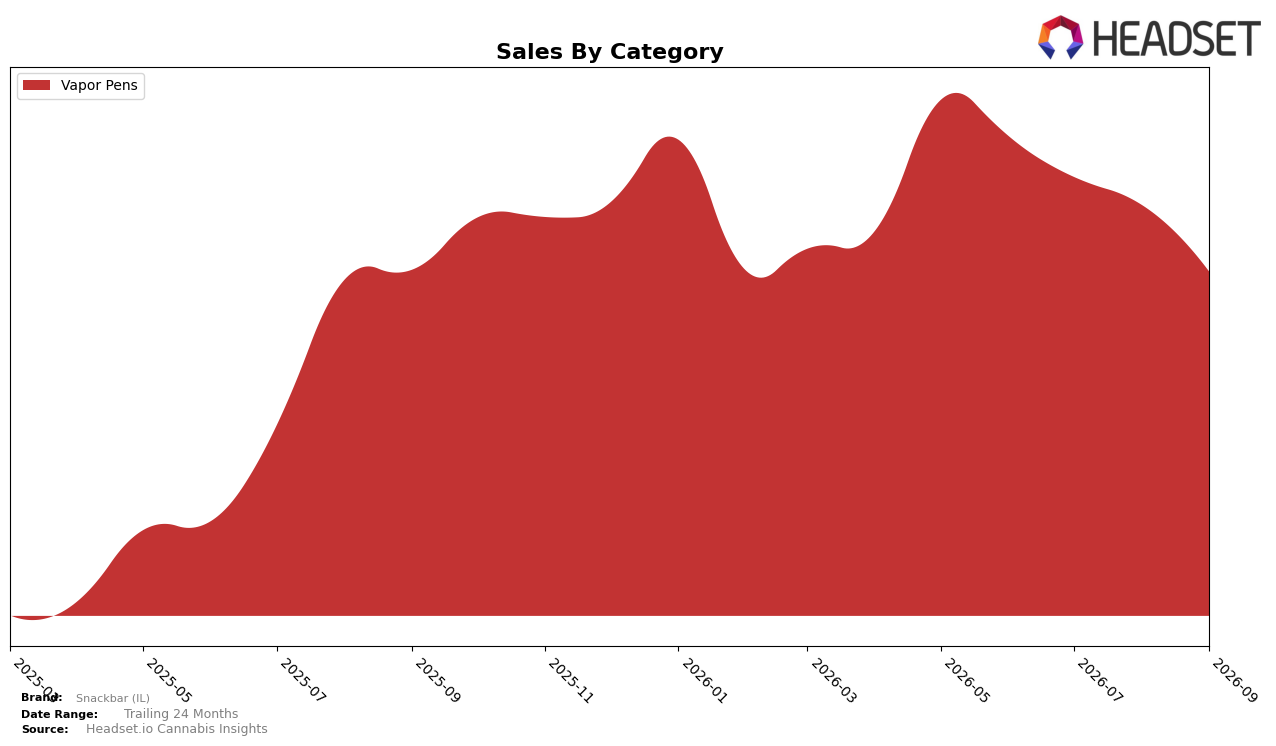
In September 2026, Snackbar (IL) operated as a single-category player in Vapor Pens, with a 100.0% category mix concentration and an average price of $47.53. Within Vapor Pens, sales contracted 57.3% year over year while declining 15.8% month over month, even as average price rose 19.2% year over year. Positioned at rank 25 in Vapor Pens in Illinois, the combination of full-category dependence and simultaneous YoY and MoM volume pressure implies exposure to price elasticity and limited diversification to buffer monthly volatility.
The shift toward higher average prices alongside a 57.3% YoY and 15.8% MoM sales decline suggests a trade-off that is eroding unit throughput at rank 25 in Illinois. With Vapor Pens at 100.0% of mix, pricing strategy carries outsized influence on share trajectory, implying that small price recalibrations or pack architecture changes could yield disproportionate gains or losses; the current configuration points to a need for elasticity-aware pricing and flavor/format targeting to stabilize rank and reduce month-to-month demand swings.
Competitive Landscape
Snackbar (IL) sits at rank #25 in IL Vapor Pens in September 2026, down 2 positions year over year from #23 and 6 positions below its June 2026 quarter-start level of #19; the brand is also 7 spots off its May 2026 peak of #18, indicating a multi-month slide rather than a single-month blip. In contrast, Fernway vaulted from #13 to #3 while growing sales 308.8%, and &Shine edged from #2 to #1 with 38.4% YoY growth, signaling that upward mobility is occurring among leaders while Snackbar (IL) loses relative position. With Select slipping from #1 to #2 despite 11.2% YoY growth and Savvy falling from #3 to #5 alongside a 32.7% decline, the dispersion of momentum suggests that Snackbar (IL)’s two-rank YoY decline and seven-rank gap from peak imply share is consolidating above it and recovery will require outperforming faster-rising peers.

Notable Products
Watermelon Lychee Distillate Disposable (1g) posted the steepest shift in September 2026 with a -29.3% MoM drop while sliding to rank 3, and Strawberry Dragonfruit Distillate Disposable (2g) also contracted -11.3% at rank 5; together these declines indicate stress in both 1g and 2g formats. Grape Crush Distillate Disposable (1g) held rank 1 despite a -6.9% MoM dip, whereas Lemon Yuzu Distillate Disposable (1g) in rank 2 inched up +2.7% MoM, pointing to share consolidation at the top as mid-pack titles retreat. Five of the top seven SKUs are Vapor Pens and three of the top three are 1g disposables, signaling format concentration even as 2g entries like Cherry Pomegranate Lemon Distillate Disposable (2g) fell -21.3% MoM to rank 6. The mix implies Snackbar (IL) is leaning into 1g disposables as the reliable volume engine while 2g trials cool, suggesting near-term focus on flavor rotation within 1g rather than further 2g expansion.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

