


Where to Buy
State Flower Cannabis is stocked at 59 licensed dispensaries across Nevada, California, and Georgia, 57 of them in Nevada, with the deepest coverage in Las Vegas, Henderson, Reno, North Las Vegas, and Carson City. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
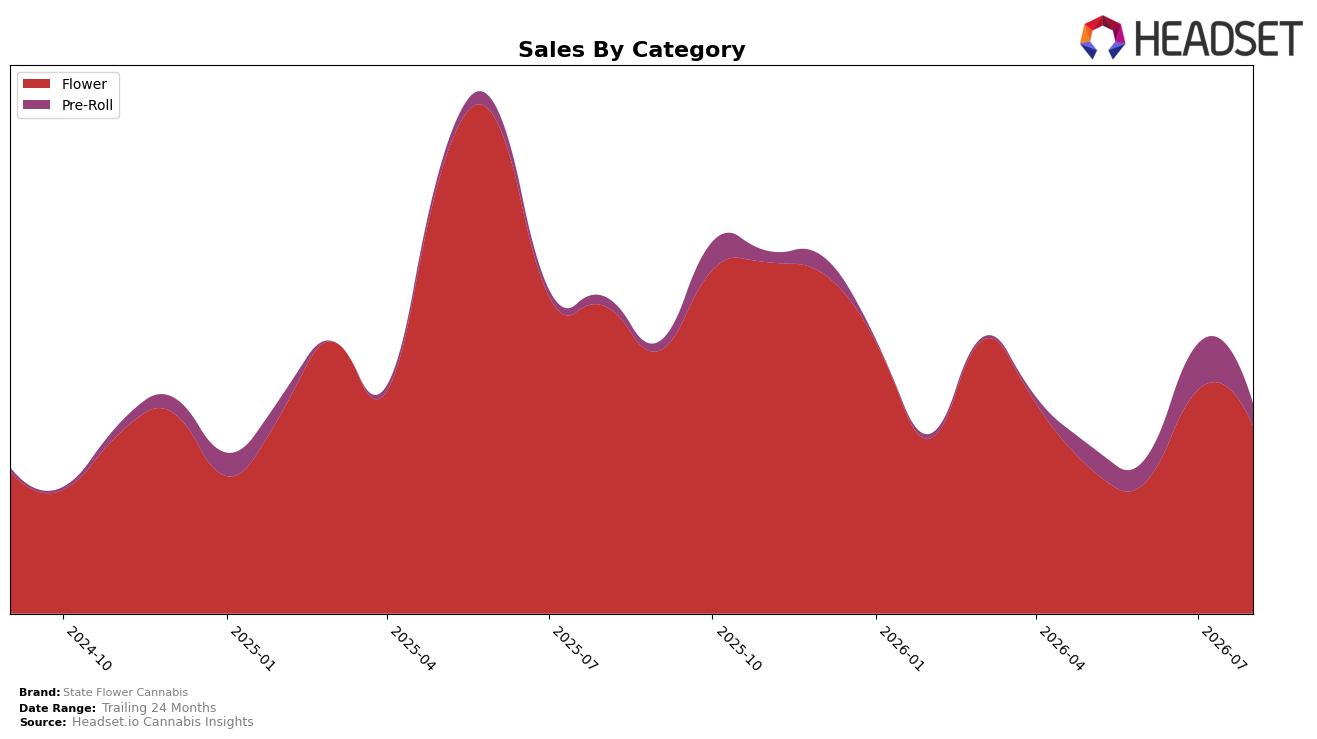
In August 2026, State Flower Cannabis concentrated 89.16% of sales in Flower with a year-over-year decline of 39.02% and a month-over-month drop of 16.09%, while Pre-Roll held 10.84% share with a 134.55% year-over-year increase but a 50.94% month-over-month contraction. Average price declined 3.66% year over year to $22.13, with Flower priced at $24.11 and Pre-Roll at $13.23, aligning with an overall brand sales decline of 33.70% year over year and 42.48% over 24 months. The pattern implies a reliance on a contracting Flower base in Nevada that is partially offset by volatile Pre-Roll gains, leaving the category mix exposed to further rank pressure at rank 42 in Flower.
The divergence between a 39.02% Flower decline and a 134.55% Pre-Roll increase, paired with a 50.94% Pre-Roll month-over-month pullback and a 16.09% Flower month-over-month decline, indicates that short-cycle Pre-Roll surges are not yet stabilizing the brand’s overall trajectory. With 89.16% of sales tied to Flower and only 10.84% to Pre-Roll, the August 2026 mix suggests limited insulation against Flower-specific headwinds, and a 3.66% average price decrease signals a value-leaning posture that has not reversed the 33.70% year-over-year sales decline. The implication is a positioning skewed toward a single core category in Nevada at rank 42, where incremental Pre-Roll share gains must accelerate and persist month over month to rebalance risk.
Competitive Landscape
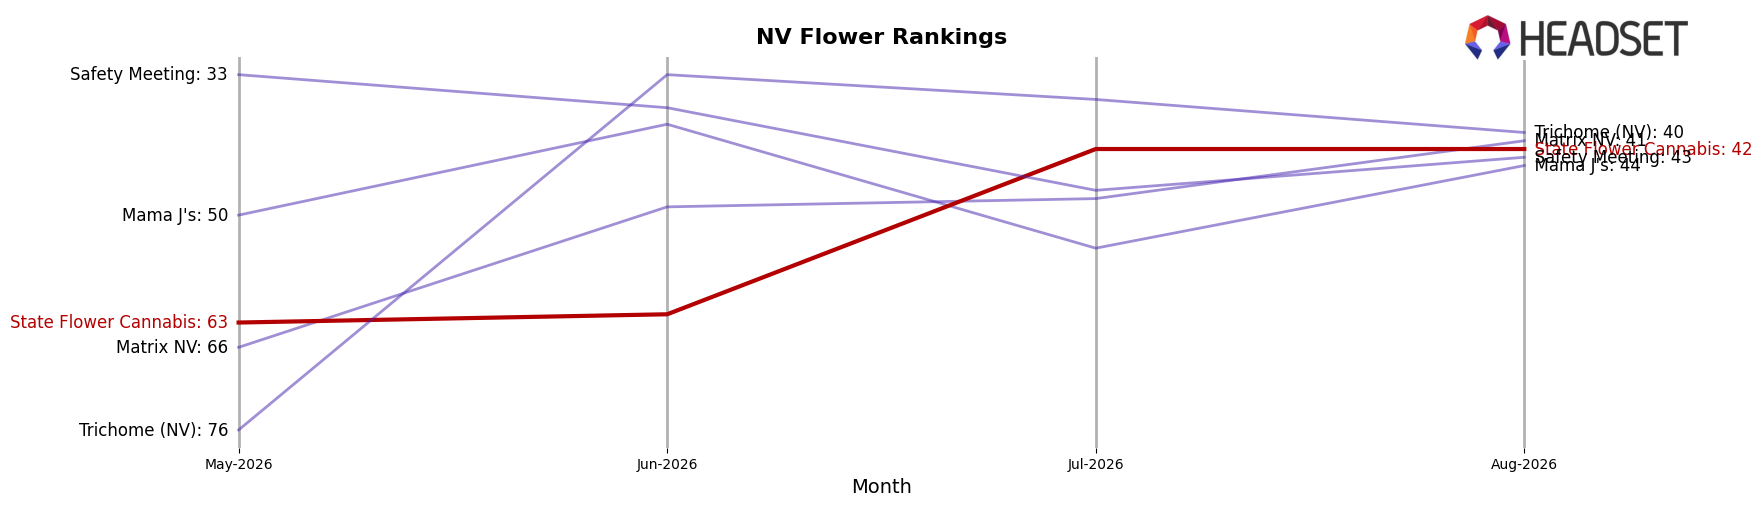
State Flower Cannabis sits at rank #42 in August 2026 in NV Flower, down 3 places year over year from #39 and up 21 positions from #63 in May 2026, while its historical peak was #26 in June 2025; in contrast, STIIIZY advanced from #2 to #1 with 50.53% year-over-year sales growth as RYTHM slipped from #1 to #2 despite 4.26% growth, and Redwood jumped from #23 to #5 alongside a 218.15% increase. The mix of a short-term climb of 33.3% in rank position from May 2026 to August 2026 (63 to 42) against a 3-rank YoY decline, coupled with competitors like Neon Moon leaping from #13 to #3 with 159.51% growth, implies State Flower Cannabis is regaining placement quarter-on-quarter but is losing relative ground versus faster-accelerating leaders, signaling a need to convert recent momentum into sustained share capture.
Notable Products
Blue Guava (3.5g) posted the sharpest movement in August 2026 with a 97.34% month-over-month rise to rank 3, while Alien Kush (3.5g) fell 62.16% to rank 9. OG Diesel (3.5g) declined 20.62% yet held a rank 1 position, and Canal Street Runtz (3.5g) slipped 8.19% at rank 2. With four of the top five coming from Flower and E85 (3.5g) up 58.55% at rank 4, the mix implies a pivot toward a smaller set of high-velocity Flower SKUs supplanting lagging strains rather than broad category expansion.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

