


Where to Buy
Awesome Dope is stocked at 117 licensed dispensaries across California, with the deepest coverage in San Diego, Sacramento, Santa Cruz, Fresno, and La Mesa. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
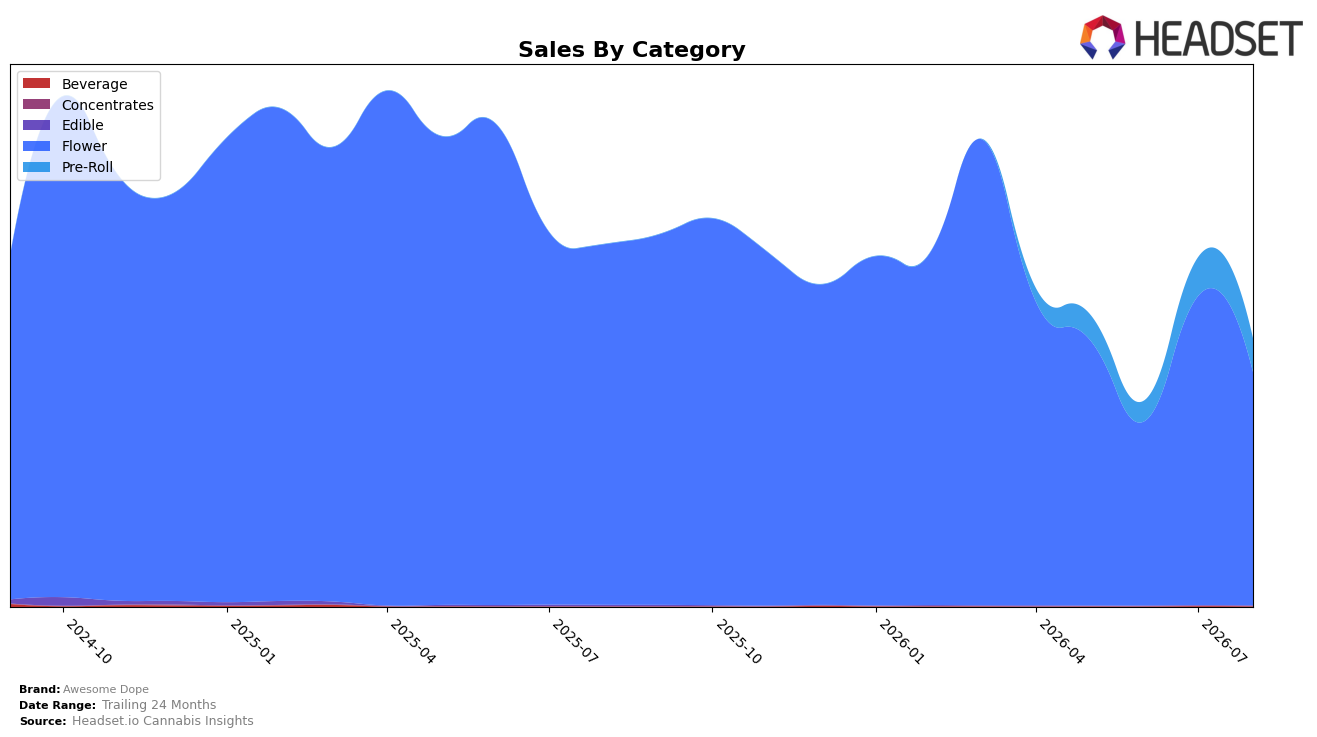
Awesome Dope’s August 2026 mix is concentrated in Flower at 87.35% share, with Flower down 35.41% year over year and 24.60% month over month, while Pre-Roll holds 12.54% share with a 13.03% month-over-month decline; Beverage is a negligible 0.08% share with a 55.69% month-over-month drop, and Edible sits at 0.03% share despite a 3.00% month-over-month uptick after a 90.46% year-over-year fall. The brand’s average price fell 38.06% year over year to $25.15 as overall sales declined 26.23% year over year, implying the portfolio is overexposed to a contracting Flower base where price compression is outpacing volume gains, and the small Pre-Roll and micro-scale Beverage and Edible lanes are too thin to offset category-level contraction.
With 87.35% of sales tied to Flower and the largest month-over-month contraction occurring in that category at 24.60%, August 2026 mix stability hinges on either stemming Flower declines or reallocating toward the 12.54% Pre-Roll segment where the decline was smaller at 13.03%. The combination of a 38.06% year-over-year price drop and a 26.23% year-over-year sales decline indicates discount-led share defense is not converting into sufficient unit growth, so positioning likely benefits from tightening the Flower assortment while selectively scaling Pre-Roll and testing Edible—despite its 90.46% year-over-year fall, its 3.00% month-over-month rise suggests a low-risk sandbox—rather than maintaining exposure to Beverage’s 55.69% month-over-month volatility.
Competitive Landscape
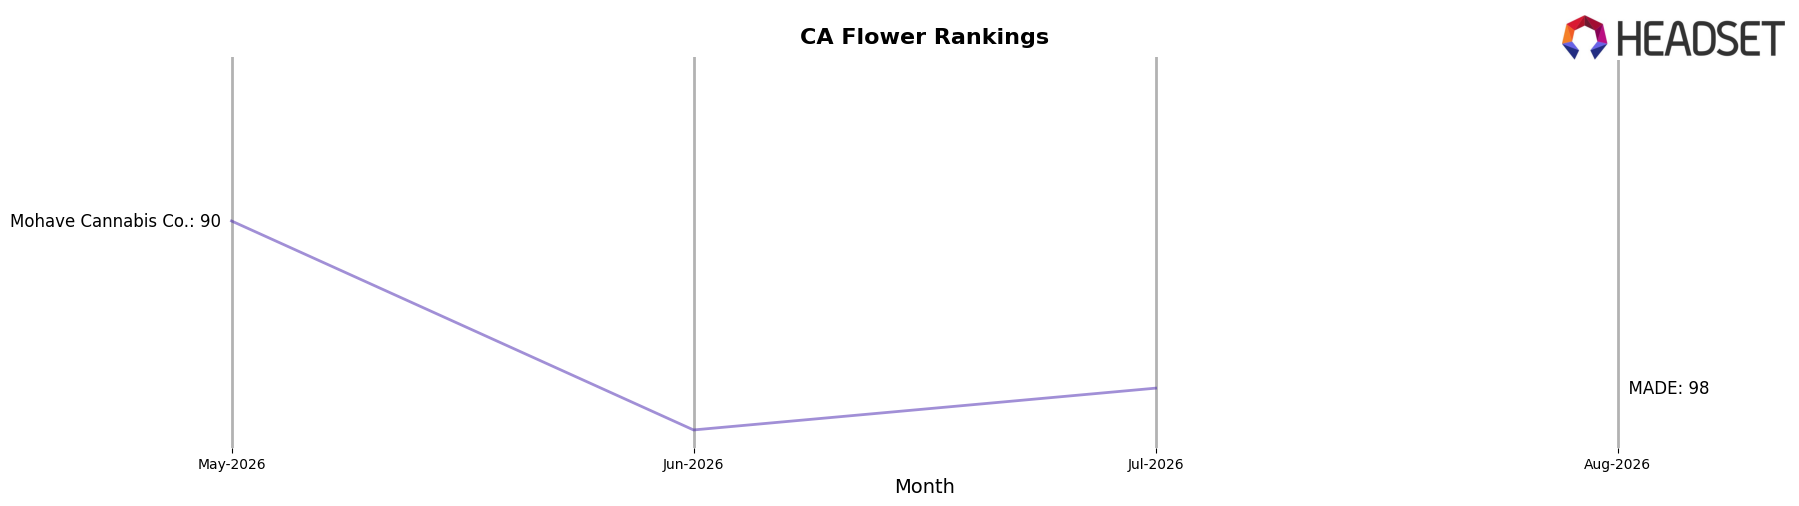
Awesome Dope sits at rank #103 in CA Flower in August 2026, falling 13 positions year over year from #90 and slipping 5 spots from #108 in May 2026 to #103 in August 2026, while its historical peak was #73 in June 2025; in contrast, STIIIZY improved from #2 to #1 with 50.40% YoY sales growth and CAM climbed from #3 to #2 with 46.56% YoY growth, whereas CannaBiotix (CBX) slid from #1 to #3 alongside a -16.00% YoY sales change; this pattern implies Awesome Dope’s downward rank trajectory is more about losing pace against accelerating leaders than a broad market contraction, signaling the need to close execution gaps where faster risers like Oakfruitland leapt from #14 to #5 on 79.85% YoY growth.
Notable Products
Awesome Dope’s steepest movement came from Jack Herer (3.5g), which fell -21.9% month over month to rank 3 while Jack Herer Pre-Roll 5-Pack (3.5g) slid -23.4% to rank 9, signaling pressure on legacy Jack Herer formats. In contrast, Orange Apricot (3.5g) jumped +50.5% to rank 2, and Jack Herer Pre-Roll (0.7g) inched up +2.9% while holding rank 1 with $1,174 in sales, indicating that value-sized pre-rolls are stable even as larger multi-packs retreat. With Flower occupying seven of the top ten ranks and two of the top three led by 3.5g SKUs, the mix suggests a pivot toward mid-size Flower velocity over bulk or multi-pack formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

