

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Cap CIty Cannabis is stocked at 13 licensed dispensaries across California, with the deepest coverage in Sacramento, Marysville, Banning, Morro Bay, and Napa. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
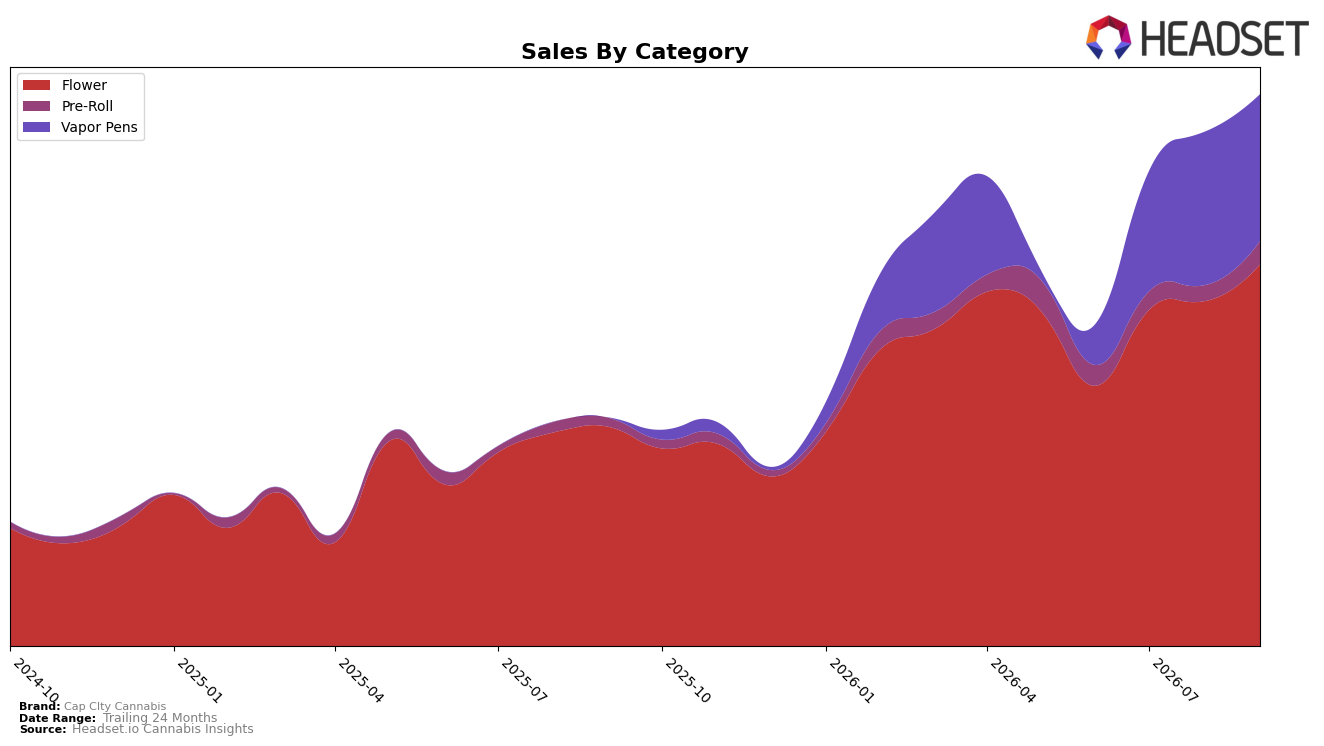
In September 2026, Cap CIty Cannabis concentrated 69.24% of sales in Flower with 74.10% year-over-year growth and a 10.67% month-over-month lift, while Vapor Pens held 26.59% share with a 4.31% month-over-month decline and no reported year-over-year figure. Pre-Roll expanded to 4.17% share with 163.61% year-over-year growth and a 46.94% month-over-month increase, and the brand’s average price fell 14.52% year over year even as overall brand sales rose 141.82% year over year. This mix indicates a pivot toward Flower-led volume in California while Pre-Roll acts as a fast-moving add-on, implying that price elasticity is converting into unit gains rather than yielding margin through higher price points.
Positionally, ranking 45th in California Flower puts Cap CIty Cannabis in a mid-pack slot within the top-category battlefield, with Flower’s 10.67% month-over-month rise contrasting with Vapor Pens’ 4.31% decline to concentrate momentum where the brand already has scale. The 46.94% month-over-month surge in Pre-Roll alongside a 14.52% year-over-year drop in average price suggests a value-forward stance that can ladder into basket-building and trial, while the 163.61% year-over-year Pre-Roll growth paired with 74.10% in Flower signals a two-tier strategy: defend Flower share through pricing efficiency and accelerate Pre-Roll for incremental reach, implying that the brand’s route to improved rank is higher unit velocity across value-priced Flower and attach-driven Pre-Rolls.
Competitive Landscape
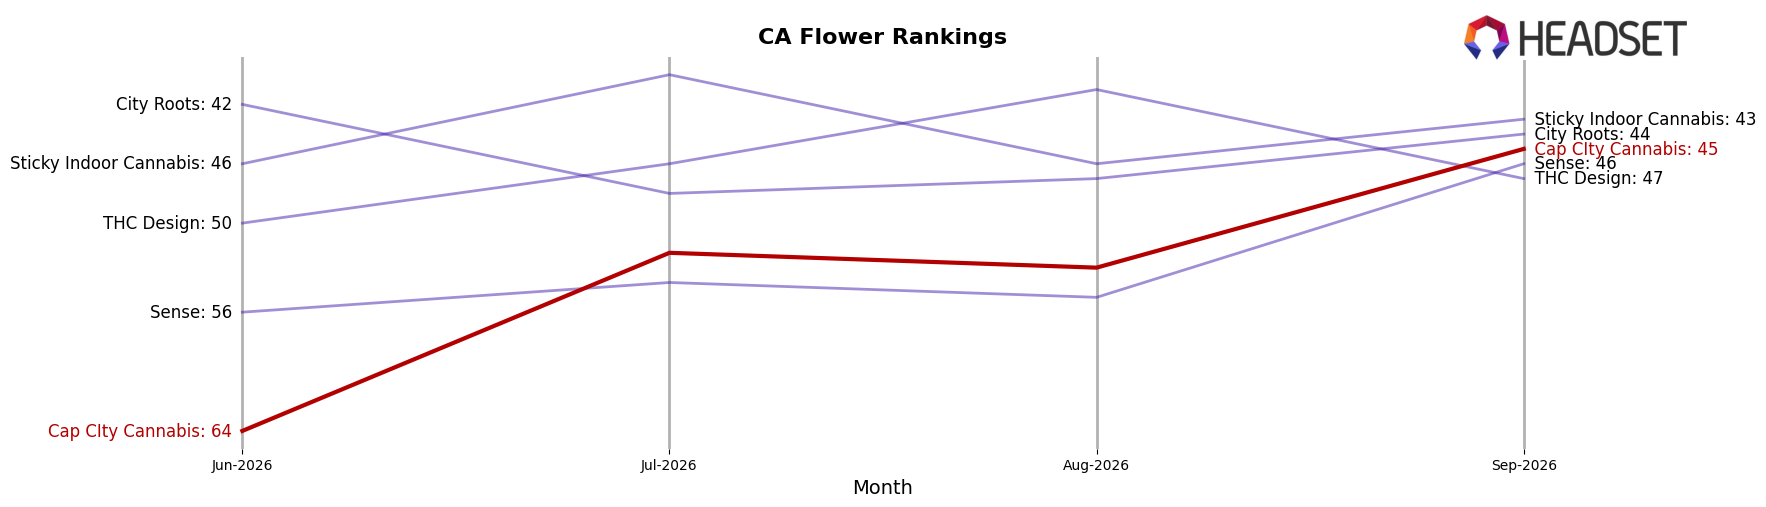
Cap CIty Cannabis sits at rank 45 in CA Flower in September 2026, improving 32 positions year over year from rank 77 while jumping 19 spots since June 2026 (from rank 64 to 45); this contrasts with STIIIZY holding rank 1 after rising from rank 2 and with Oakfruitland advancing from rank 11 to rank 5 alongside a 73.5% year-over-year sales lift, whereas CannaBiotix (CBX) slid from rank 1 to rank 3 with a 21.1% year-over-year sales decline; the combination of a peak rank reached in September 2026 and faster quarter-over-quarter ascent than year-over-year climb implies Cap CIty Cannabis is in a momentum catch-up phase where recent execution is accelerating share gains but still trails the category leaders’ pace.
Notable Products
White Runtz Pre-Roll (1g) posted the largest movement in September 2026 with a +60.5% month-over-month surge to rank 1, while Amnesia Haze Pre-Roll (1g) fell -10.6% to rank 6 and Midnight Berry Pre-Roll (1g) declined -12.0% to rank 7. Tropical Cherry (3.5g) advanced +44.7% to rank 2, and four of the top ten are Pre-Roll SKUs clustered between ranks 1 and 10, indicating a portfolio tilt toward affordable, high-velocity formats over premium Flower despite one Flower unit posting gains.
Across categories, Vapor Pens held mid-table with Grape Runtz Distillate Cartridge (1g) at rank 4 and Garlic Juice Distillate Cartridge (1g) at rank 9, contrasting with Pre-Rolls where momentum is bifurcated between a +60.5% leader and double-digit decliners. With Flower split between a rising Tropical Cherry (3.5g) at rank 2 and larger-pack Tropical Cherry (7g) at rank 5 on $27,315, the mix points to a strategy favoring entry-price trial in Pre-Rolls while maintaining visibility in Flower and Vapor Pens to hedge against volatility.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

