


Where to Buy
Lumpy's is stocked at 136 licensed dispensaries across California, with the deepest coverage in Sacramento, San Jose, Fresno, Los Angeles, and San Francisco. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
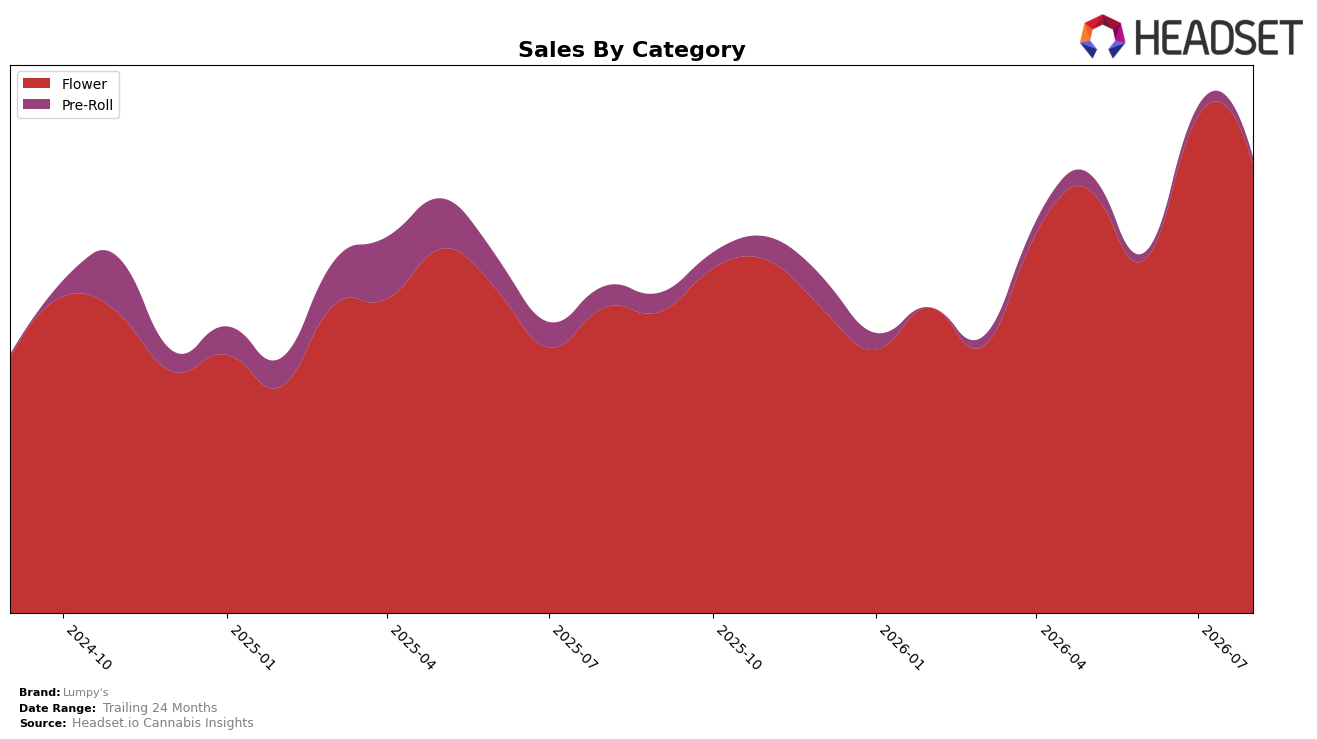
In August 2026, Lumpy's concentrated 95.49% of sales in Flower while Pre-Roll accounted for 4.51%, a split that coincided with a 44.38% year-over-year lift in Flower versus a 39.23% year-over-year decline in Pre-Roll. Month over month, Flower fell 9.81% and Pre-Roll contracted 11.44%, even as total brand sales grew 35.95% year over year and the average price dipped 0.86%. With Flower ranked 31 in California and carrying a higher average price at $36.27 versus $6.41 for Pre-Roll, the mix skews toward premiumized Flower volume despite short-term monthly softness; the pattern implies that category depth in Flower is the primary engine for annual growth while Pre-Roll is a drag on momentum.
The widening gap—Flower up 44.38% year over year against Pre-Roll down 39.23%, combined with simultaneous month-over-month contractions of 9.81% and 11.44%—suggests that Lumpy's positioning is anchored in Flower where price tolerance and rank 31 in California support scale, while Pre-Roll under-indexing limits basket extension. The slight 0.86% average price decrease alongside a 35.95% brand sales increase implies volume-led gains concentrated in Flower, indicating that reinforcing Flower assortment and selectively pruning or repositioning Pre-Roll could lift overall efficiency and improve competitive standing within the Flower set.
Competitive Landscape
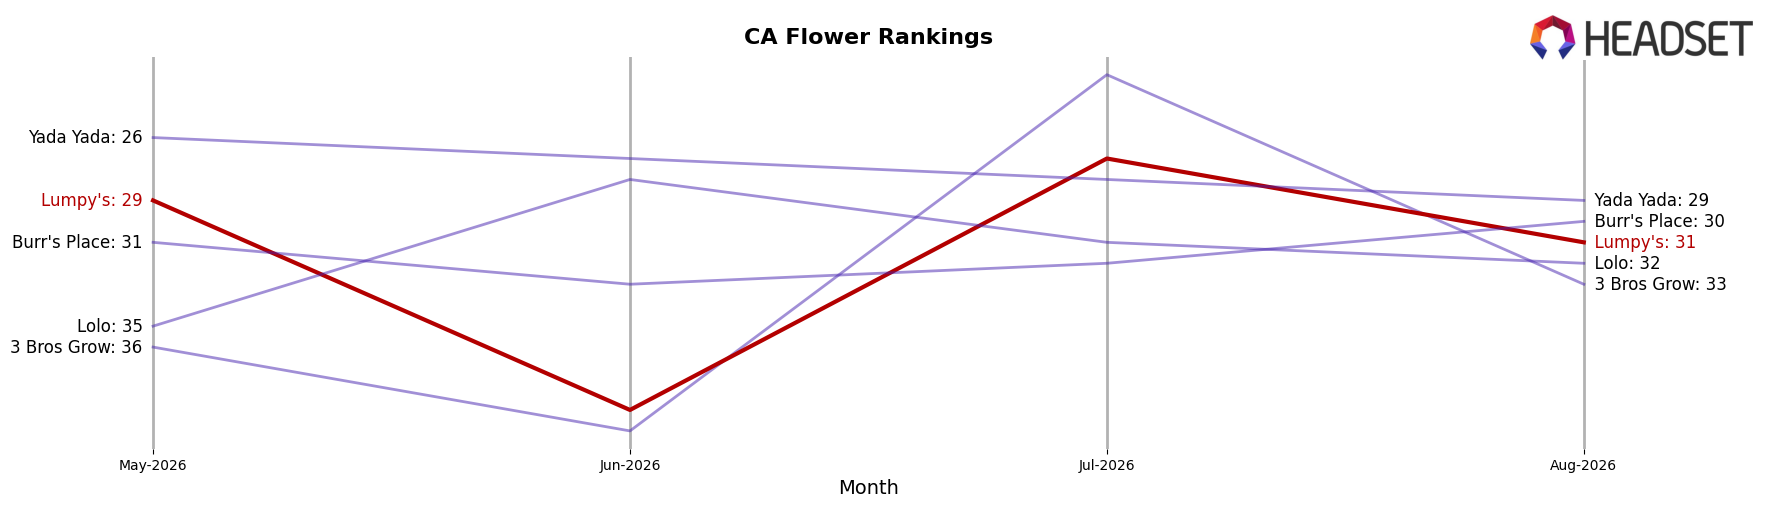
Lumpy's sits at rank #31 in CA Flower in August 2026, improving 12 positions from #43 year over year, but slipping 2 spots from #29 in May 2026 while also coming off a peak of #27 in July 2026; in contrast, STIIIZY advanced from #2 to #1 with 50.4% YoY sales growth and CAM climbed from #3 to #2 alongside a 46.6% YoY increase, indicating that Lumpy's relative gains versus last year are being outpaced by top-tier acceleration and that the brand is consolidating in the upper-30s to low-30s band rather than breaking into the top-25.
Notable Products
Banana Bread (3.5g) posted the steepest movement in August 2026 with a -30.8% month-over-month drop and slid to rank 3, while Lemon Squarez (3.5g) climbed 36.1% month over month into a share of the number 3 rank, indicating volatility within flagship Flower SKUs. Peanut Butter and Jelly (3.5g) held rank 1 with no reported month-over-month figure and carried the month’s largest dollar haul at $65,365, whereas Fluffy Pre-Roll (1g) rose 13.5% month over month to rank 2, creating a split leadership between Flower and Pre-Roll. Four of the top ten are Flower SKUs clustered across ranks 1, 3, 4, 6, 7, and 9, and two of the top ten are Pre-Roll SKUs at ranks 2 and 8, pointing to a portfolio tilt where Flower breadth anchors volume while selective Pre-Roll gains are starting to diversify mix. The pattern implies Lumpy’s is shifting from single-SKU dominance toward a two-lane strategy where Flower drives baseline rank stability and targeted Pre-Roll growth absorbs demand swings from underperforming strains.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

