

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Blush Velvet is stocked at 84 licensed dispensaries across Washington, with the deepest coverage in Seattle, Spokane, Mount Vernon, Tacoma, and Bellingham. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
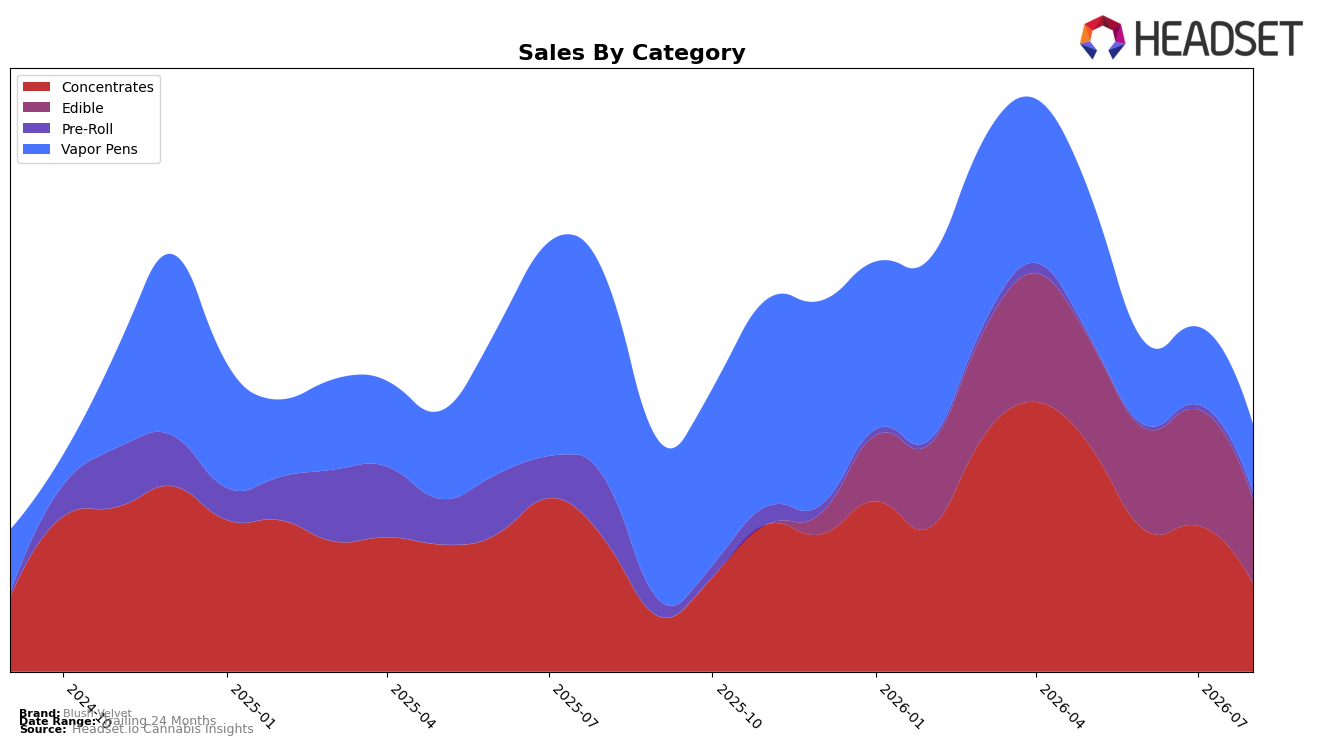
In August 2026, Blush Velvet’s mix concentrated into three core categories: Concentrates at 35.70% share with year-over-year down 33.53% and month-over-month down 39.63%, Edible at 34.04% share with month-over-month down 27.67% and no reported year-over-year rate, and Vapor Pens at 27.61% share with year-over-year down 66.63% and month-over-month down 12.49%; Pre-Roll held 2.65% share with year-over-year down 89.34% but month-over-month up 40.69%. Despite a brand-level average price up 6.52% year over year to $25.78, mix shifts leaned toward lower-priced Edible at 19.61 average price while higher-priced Concentrates at 33.83 contracted sharply, implying margin pressure even as the category spread narrows and risk concentrates in a few declining pillars.
The tilt toward Concentrates at 35.70% share alongside Vapor Pens at 27.61% concentrates exposure in two categories with steep year-over-year declines of 33.53% and 66.63%, while the Edible rise in mix to 34.04% during a 27.67% month-over-month drop signals defensive share capture rather than growth; in Washington, the absence of a current Concentrates rank suggests weakened shelf traction even as the brand’s top category remains Concentrates. The pattern implies that Blush Velvet’s positioning is over-indexed to categories with rapid volume erosion, so sustaining price at a 6.52% year-over-year increase without accelerating Edible velocity or rebuilding Concentrates recovery risks further share loss and a narrowing customer set.
Competitive Landscape
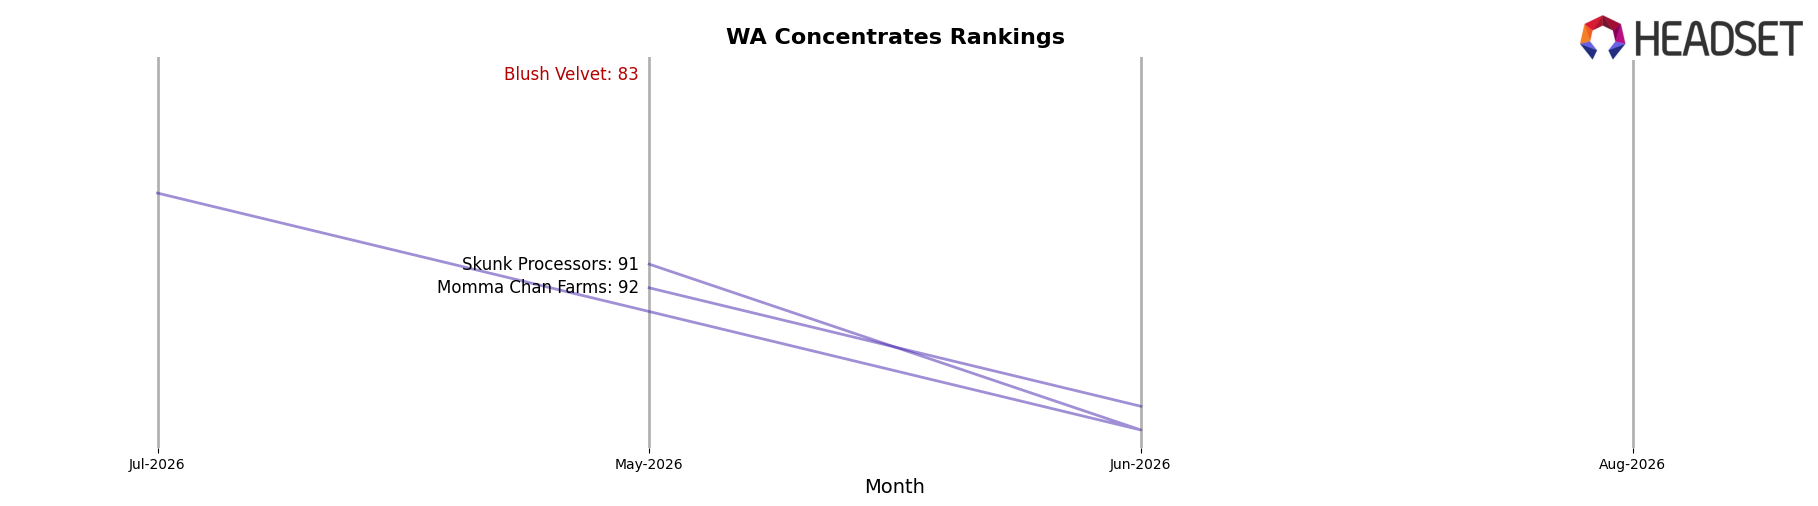
Blush Velvet sits at rank 128 in Washington Concentrates in August 2026, down 5 positions year over year from rank 123, and 45 positions lower than its three-month mark at rank 83; the brand’s peak at rank 77 in April 2026 places today’s standing 51 spots off that high. In contrast, Ooowee held rank 1 year over year and remains rank 1, while Constellation Cannabis advanced from rank 6 to rank 4 as sales grew 15.88%, indicating that category leadership is concentrating at the top as Blush Velvet cedes relative position. The pattern implies that without reversing the 5-rank YoY slippage and the 45-rank decline since May–July 2026 levels, Blush Velvet is transitioning from mid-tier visibility toward long-tail status, making near-term recovery dependent on recapturing share from brands ascending into the top 5.
Notable Products
Picasso Moon Cold Cure Rosin (1g) posted the largest movement in August 2026 with an 81.5% month-over-month jump to rank 3, while Honey Dew Cold Cure Rosin (1g) slid 57.3% to rank 6, signaling volatility concentrated within Concentrates. Peach Bellini Hash Rosin Gummies 20-Pack (100mg) fell 10.9% to rank 2 and Banana Cream Hash Rosin Gummies 20-Pack (100mg) dropped 49.9% to rank 5, and five of the top ten are Edible SKUs, indicating a category that holds shelf share but is ceding momentum to premium extracts. The new Strawberry Guava Rosin Disposable (1g) entered at rank 8 with $1,799 in sales while the 0.5g variant in the same line inched up 4.5% to rank 9, implying the Vapor Pens line is beginning to bridge the gap between slowing Edibles and surging Concentrates. Net effect: Blush Velvet’s product mix is tilting toward higher-potency formats, suggesting near-term emphasis on Concentrates and Rosin-based hardware over fruit-flavor Edibles.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

