

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
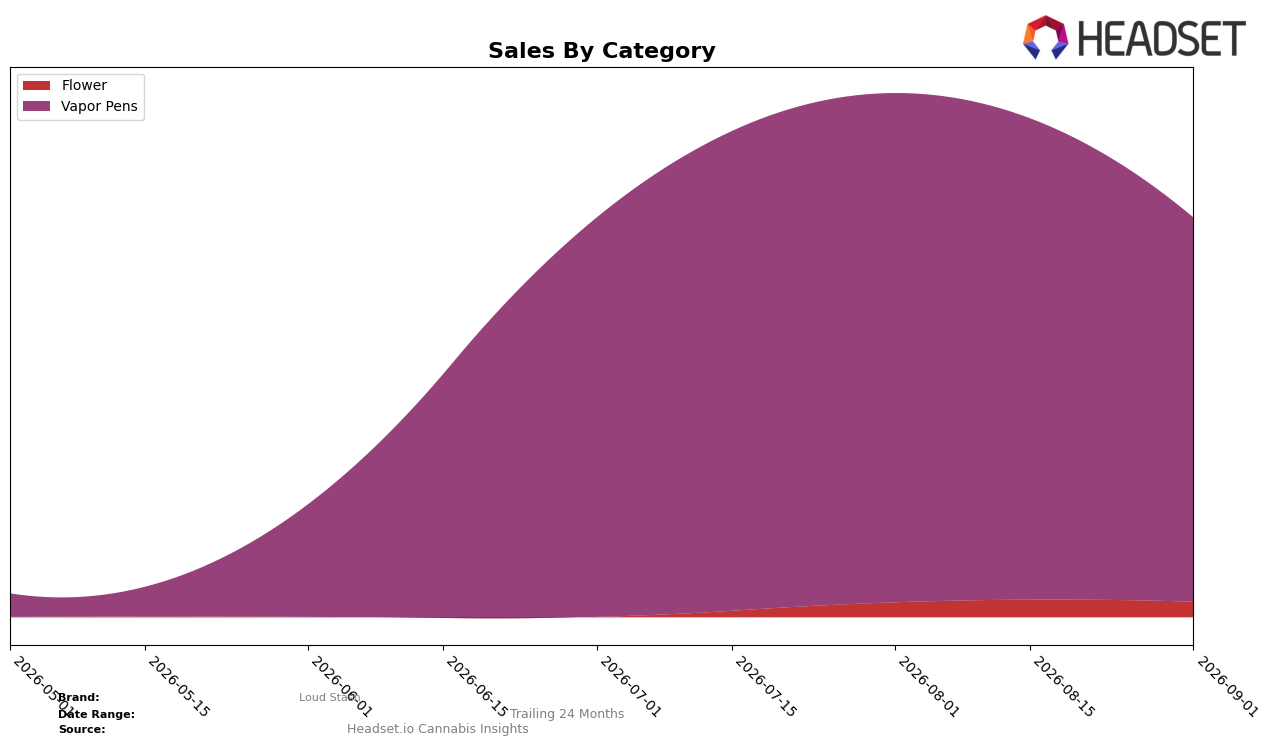
Vapor Pens accounted for 96.20% share in September 2026 with a month-over-month decline of 24.57%, while Flower rose 4.03% MoM to a 3.80% share; this mix leans heavily on one category despite divergent monthly trajectories. Average prices differed by 36.2% between Vapor Pens at $50.57 and Flower at $37.11, and the brand held rank 31 in Vapor Pens in New Jersey; this combination implies concentration risk as volume softness in the largest category can outsizedly pull overall performance even when smaller segments expand.
The 24.57% MoM contraction in a 96.20% share anchor category alongside a 4.03% MoM lift in a 3.80% share niche suggests pricing and product strategy should prioritize stabilizing Vapor Pen velocity while selectively scaling Flower to diversify exposure. Given the 31 rank position in New Jersey and a 36.2% price gap between categories, the pattern implies Loud Stash can protect position by adjusting pen price-pack architecture for mid-tier conversion and using Flower as a lower-priced entry to broaden baskets, lowering reliance on a single category while preserving rank defensibility.
Competitive Landscape
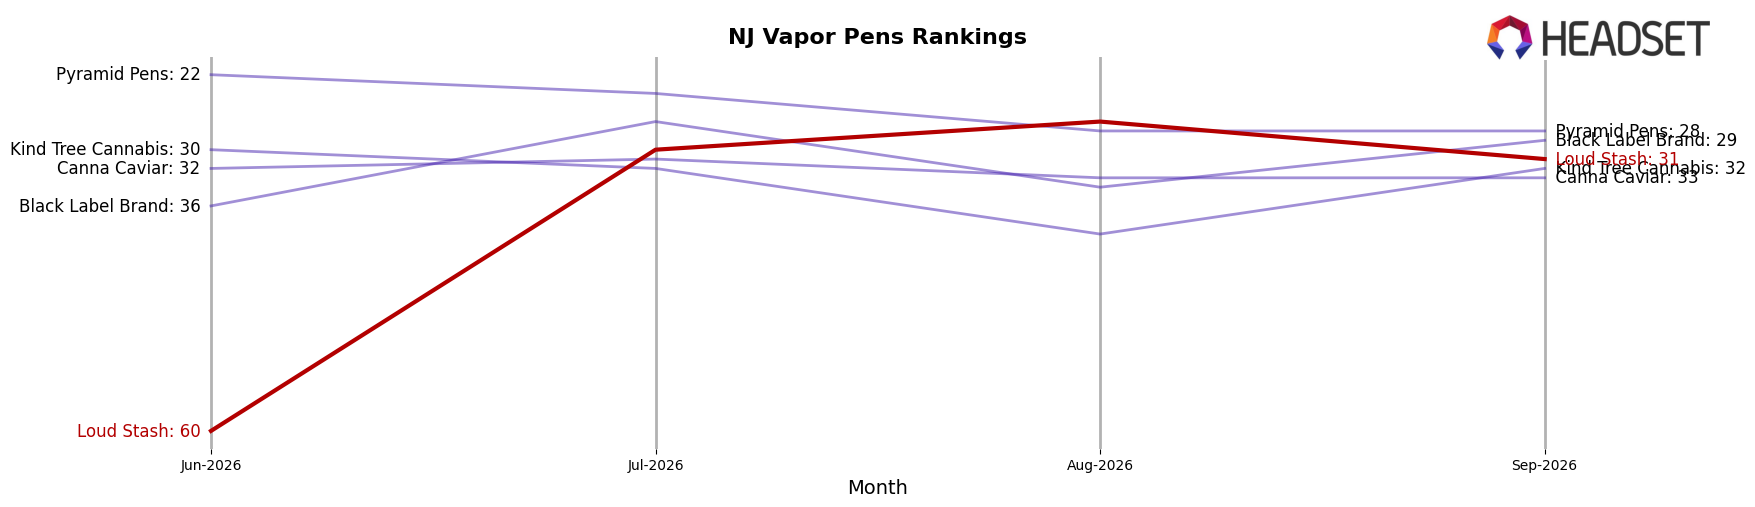
Loud Stash sits at rank #31 in New Jersey Vapor Pens for September 2026, improving 29 positions from #60 in June 2026 and sitting four spots below its peak of #27 reached in August 2026; the absence of a year-over-year rank means the three-month climb of 48% in rank position (from 60th to 31st) is the clearer signal alongside a 13% slide from its August peak to the current slot. Against market leaders, Fernway moved year over year from #2 to #1 with a 19.2% sales increase, while Select dropped from #1 to #2 with a 24.0% sales decline, indicating top-tier volatility that contrasts with Loud Stash’s mid-pack ascent; this divergent pattern implies Loud Stash’s recent rank gains are driven more by short-term execution than structural category shifts, signaling a path to re-test its #27 peak if momentum extends beyond September 2026.
Notable Products
Sour Diesel Live Resin Disposable (2g) posted the steepest decline in September 2026, dropping 30.17% MoM and sliding to rank 8, while Sour Diesel Distillate Live Resin CDT Disposable (2g) fell 18.60% MoM at rank 6. In contrast, White Gummies Live Resin Disposable (2g) rose 20.93% MoM to hold rank 1, outpacing the modest 5.41% MoM lift of Donny Burger Distillate Live Resin CDT Disposable (2g) at rank 2. With eight of the top ten coming from Vapor Pens and the lone Flower entry Super Silver Haze (3.5g) inching up 4.03% MoM at rank 7, the mix tilts toward disposable pen demand even as strain-specific Sour Diesel variants lose traction. The pattern implies SKU concentration in disposables is driving the brand’s share of wallet, but volatility within legacy strain names points to rotation risk that favors novelty-led Vapor Pen line extensions.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

