

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
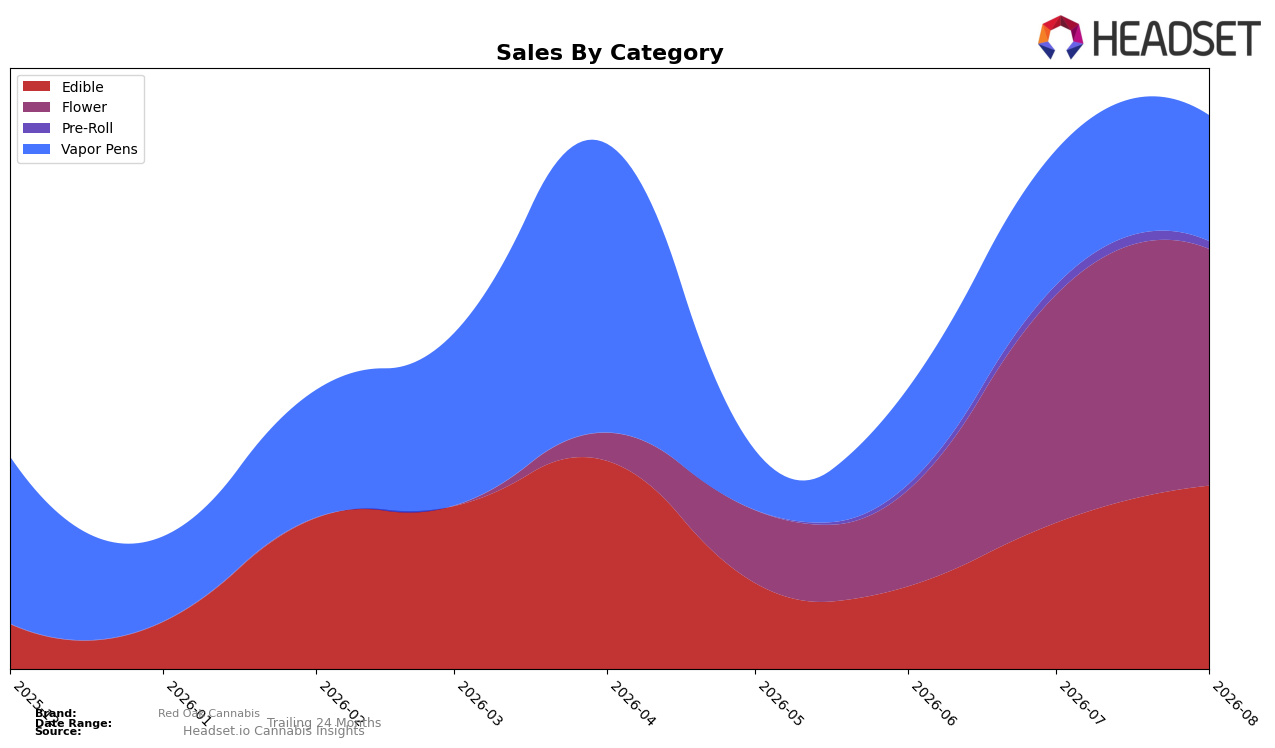
Red Oak Cannabis concentrated over two-thirds of August 2026 sales in Flower and Edible, with Flower at 42.74% share and Edible at 33.17%, while Vapor Pens held 22.72% and Pre-Roll just 1.37%. Month over month, Edible expanded by 25.32% while Flower rose 3.78%, contrasted with a 6.61% decline in Vapor Pens and a 20.51% drop in Pre-Roll; the average ticket sat at $20.91, anchored by Edible at $16.74 and Flower at $25.18. In New Jersey Edible specifically ranked 42 in August 2026, indicating that the brand’s fastest-growing category still sits mid-pack, which implies the current mix shift favors volume growth in Edible but has not yet translated into category leadership.
The rapid Edible mix acceleration (+25.32% MoM) versus declines in Vapor Pens (-6.61% MoM) and Pre-Roll (-20.51% MoM), alongside Flower’s modest +3.78% MoM, suggests Red Oak Cannabis is migrating demand into a lower-priced basket (Edible at $16.74 vs Vapor Pens at $24.30), trading share toward price-accessible formats. With Flower holding the largest share at 42.74% but Edible rising faster and ranking 42 in August 2026, the positioning implication is a pivot toward value-driven, ingestible use occasions that can scale share, while the contraction in inhalable formats signals a need to defend against mix erosion in higher-priced segments if margin preservation is a priority.
Competitive Landscape
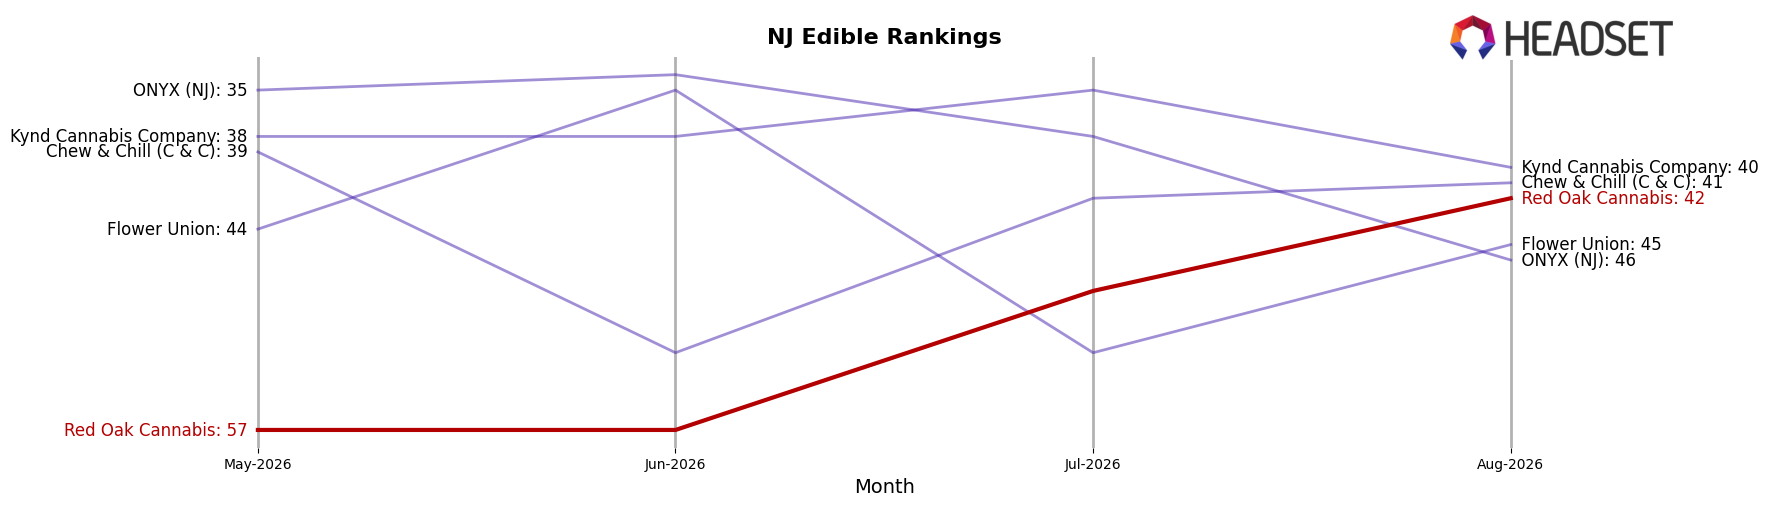
Red Oak Cannabis sits at rank 42 in New Jersey Edible for August 2026, improving 15 positions from rank 57 in May 2026, while still trailing its peak rank of 40 from April 2026; the lack of a published year-over-year rank masks longer-cycle movement, but the 2-spot gap to its April 2026 peak indicates recent gains have nearly closed the spring setback. Among leaders, Gron / Grön holds rank 1 despite a -19.9% YoY sales change, and Wyld maintains rank 2 with a smaller -8.6% YoY decline, suggesting top-tier share is stabilizing at lower volumes even as OGEEZ climbed to rank 4 from rank 7 with +18.0% YoY sales growth; by contrast, Red Oak Cannabis’s rank lift of 15 places over three months points to momentum driven by relative share gains rather than category expansion, implying its trajectory is one of catch-up toward the low-40s with headroom limited unless it converts the April 2026 peak into sustained sub-40 placement.
Notable Products
Blue Zushi Smalls (3.5g) posted the steepest decline at -31.5% MoM while slipping to rank 4, and White Runtz Pre-Roll (1g) fell -20.5% at rank 7, together signaling Flower volatility amid a softening for single-stick Pre-Rolls. Offsetting that, Island Myst Distillate Disposable (0.5g) climbed +36.1% to rank 6 and Strawberry Watermelon Gummies 10-Pack (100mg) rose +35.4% to rank 2, with Blueberry Pomegranate Gummies 10-Pack (100mg) up +30.9% at rank 3, which points to demand rotating toward Edibles and Vapor Pens.
Super Boof Smalls (3.5g) held rank 1 despite no recorded MoM rate, while King Dewie Distillate Disposable (0.5g) edged down -9.9% at rank 9 against Southern Haze Distillate Disposable (0.5g) at +5.3% and rank 5, indicating mixed traction within disposables at different price tiers near $6.4k. With two Edibles in the top three and three Flower SKUs in the top ten, the mix implies Red Oak Cannabis can defend its Flower anchor while leaning into faster-growing Edibles and select disposables to stabilize month-to-month swings.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

