
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change




Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeMarket Insights Snapshot
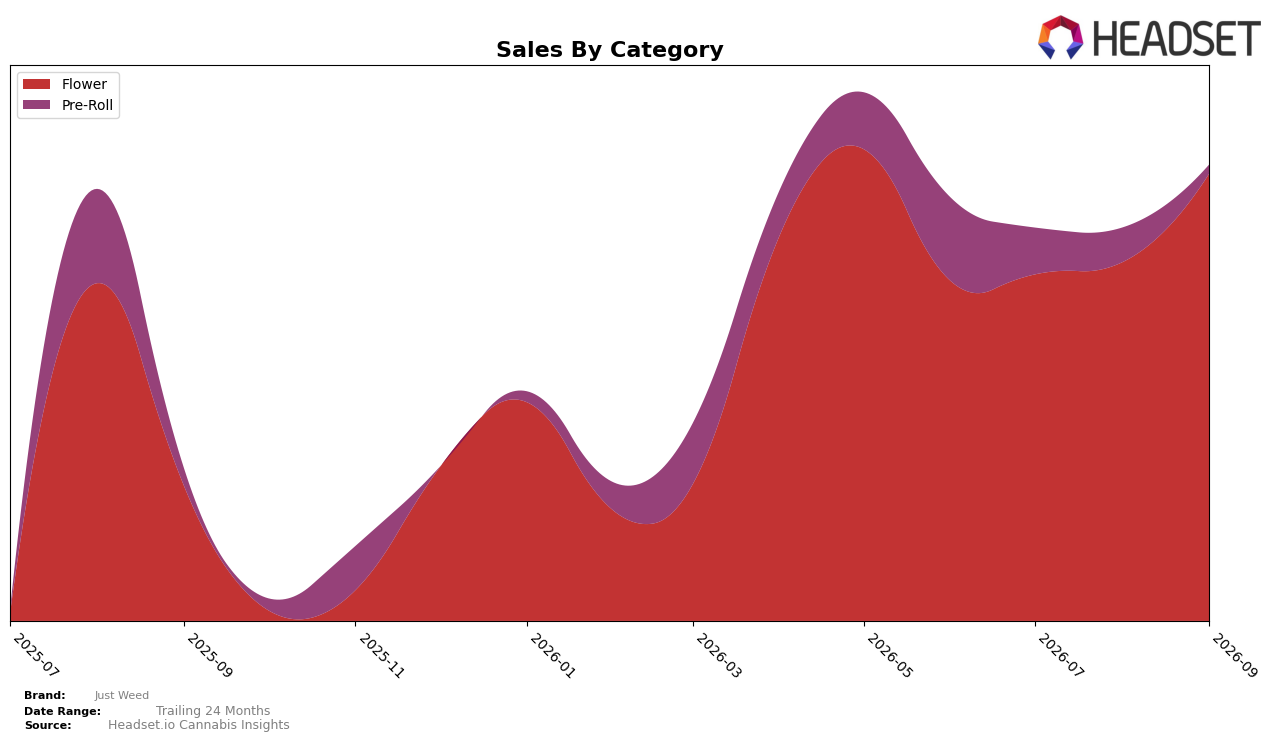
Flower drove 98.10% share in September 2026, up 24.80% month over month and 233.24% year over year, while Pre-Roll fell to 1.90% share with a 74.77% MoM decline and a 49.49% YoY drop; this mix shift coincided with a 66.59% YoY rise in average price to $107.65 and a 201.24% YoY increase in total brand sales. In the Saskatchewan Flower context, a rank of 49 pairs with a category concentration that expanded by 24.80% MoM and 233.24% YoY, implying the brand is consolidating demand into a single format and trading consumers into higher-priced Flower while ceding breadth in Pre-Rolls.
The heavier tilt toward Flower at 98.10% share and the simultaneous 24.80% MoM category growth signal a positioning anchored in premiumized Flower rather than multi-format coverage, reinforced by the 66.59% YoY price lift alongside a 49.49% YoY contraction in Pre-Roll. Holding rank 49 in Saskatchewan Flower while Flower sales grew 233.24% YoY and Pre-Roll fell 74.77% MoM suggests the current advantage is depth in a single category rather than overall market ranking, implying the path forward is to leverage Flower-driven momentum to improve rank efficiency without diluting focus into underperforming Pre-Rolls.
Competitive Landscape
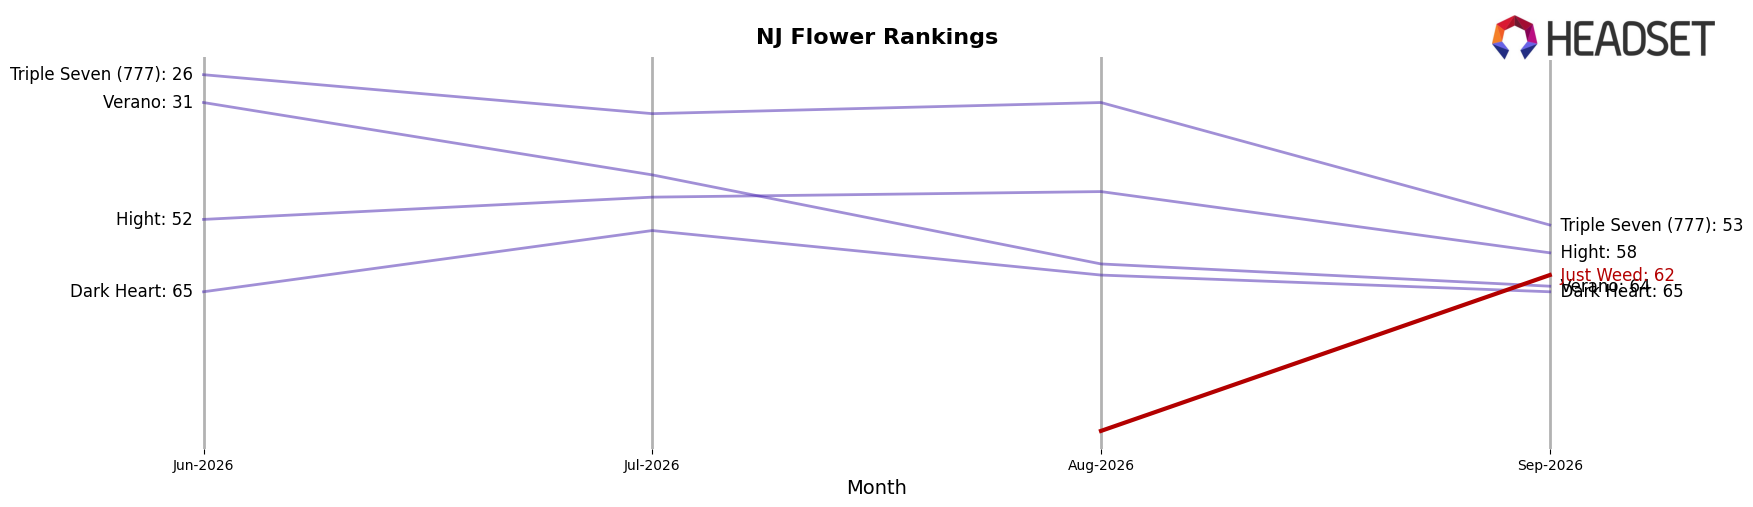
Just Weed sits at rank #62 in New Jersey Flower, with no year-over-year rank reported, but it climbed 39 positions from #101 in June 2026 to its peak #62 in September 2026, indicating a rapid recent ascent; meanwhile, Find. advanced to #1 with a +6 YoY rank change alongside 111.6% YoY sales growth, and Ozone held #2 despite a -2.8% YoY sales decline, signaling that the top tier is mixing expansion and contraction while Just Weed is catching up from below. The juxtaposition of a 39-rank quarter-over-quarter jump for Just Weed against Good Green moving +17 ranks to #3 with 166.7% YoY sales growth suggests a market where rapid laddering is attainable but concentrated among a few leaders, implying Just Weed’s trajectory is momentum-driven and contingent on sustaining recent share capture rather than displacing entrenched top-5 incumbents in the near term.
Notable Products
The steepest decline came from Liquid Imagination (14g), down 78.45% month over month and sitting at rank 8, while Slurricane x Godfather Og (28g) also fell 69.83% to rank 9. In contrast, Honey Banana S1 (28g) surged 130.95% month over month to rank 1, outpacing Dogwalker OG (28g), which dropped 52.84% to rank 4. With eight of the top ten in Flower and Pre-Rolls confined to ranks 7 and 10, the mix points to a pivot toward large-format Flower dominance and away from smaller formats, concentrating demand in a few high-velocity ounces.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

