


Where to Buy
Moment is stocked at 38 licensed dispensaries across Maryland, with the deepest coverage in Baltimore, Annapolis, Hagerstown, Ocean City, and Catonsville. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
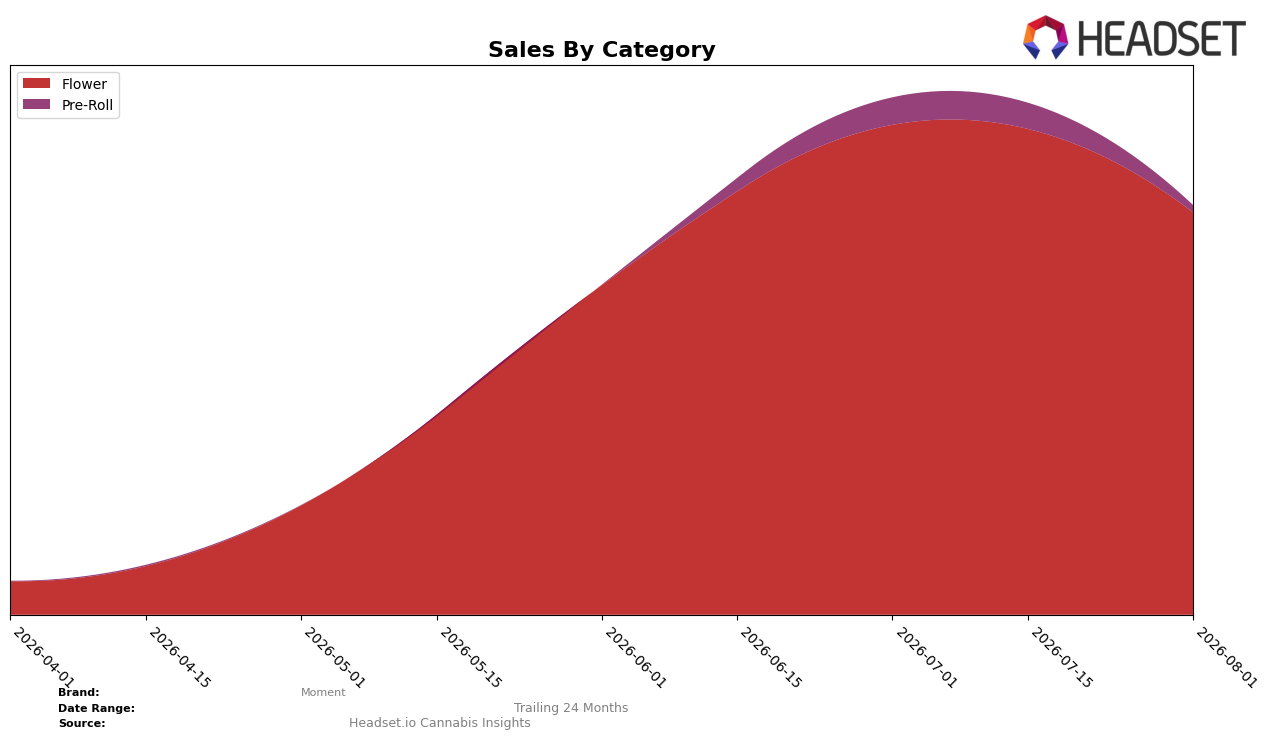
In August 2026, Moment concentrated 98.30% of sales in Flower while Pre-Roll accounted for 1.70%, indicating a narrowed category mix compared to typical multi-category peers. Month over month, Flower declined 17.89% while Pre-Roll fell 74.28%, and the brand’s overall average price of $30.45 sat close to Flower’s $30.87, implying limited price-led mix shifts. With Flower ranked 40 in Maryland, the contraction in Pre-Roll share and the sharper Pre-Roll MoM drop versus Flower point to increasing reliance on a single category, which raises exposure to category-specific volatility rather than broadening demand capture.
The combination of a 17.89% Flower MoM decline alongside a 74.28% Pre-Roll MoM contraction suggests that Moment’s demand elasticity is tethered to Flower dynamics, not diversified by lower-priced Pre-Rolls at a $16.96 average. Holding 98.30% share in Flower while sitting at rank 40 in Maryland indicates the brand is positioned as a niche participant within its core category, and the magnitude gap between category declines implies price or assortment within Pre-Roll is not serving as a traffic hedge; the pattern implies Moment’s positioning benefits from shoring up Flower velocity or selectively rebuilding Pre-Roll to stabilize mix without diluting its Flower-led identity.
Competitive Landscape
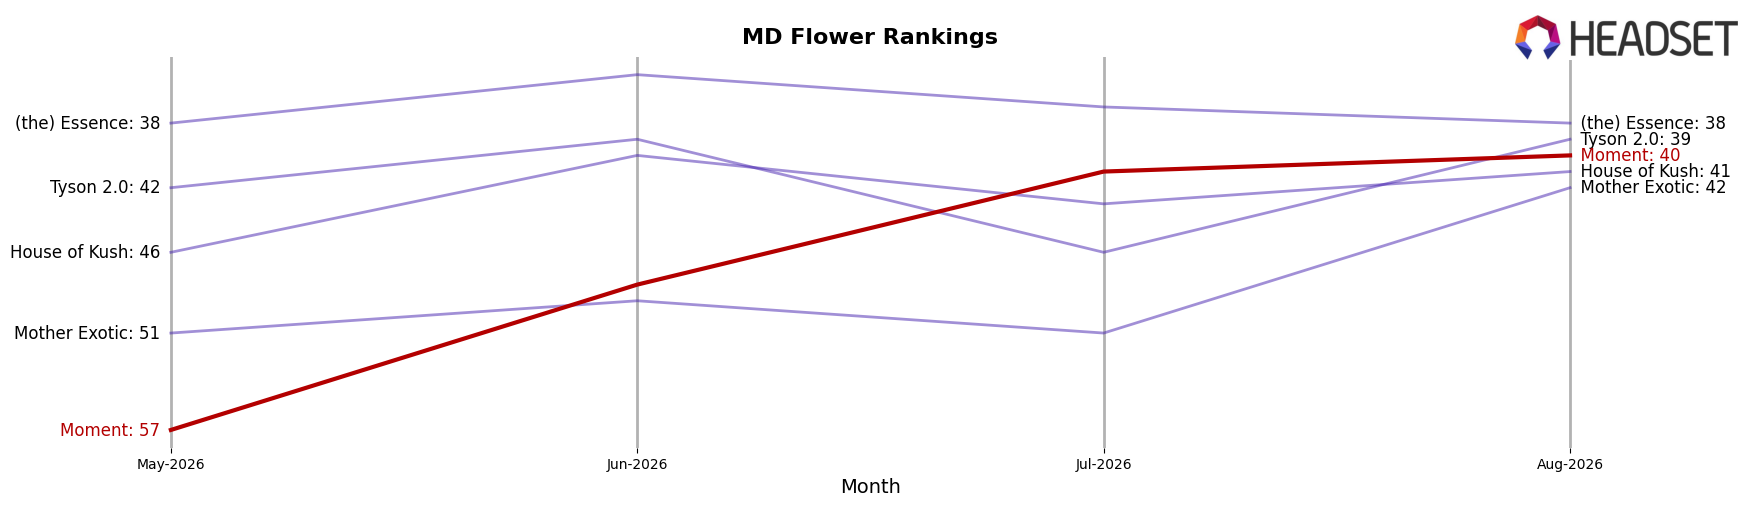
Moment sits at rank #40 in MD Flower in August 2026, a climb of 17 positions from #57 in May 2026, and this new peak rank (#40) marks its best to date. Against leaders, SunMed holds #1 with 1.08% year-over-year sales growth while Find. jumped to #5 with a 29-place rank gain and a 526.50% year-over-year sales increase, indicating share is consolidating quickly at the top even as Moment advances from the mid-pack. The simultaneous step-up from #57 to #40 and the concentration of growth at #1–#5 implies Moment’s trajectory depends on converting recent rank momentum into sustained share capture before upward mobility tightens further.
Notable Products
Oreoz (3.5g) delivered the standout move in August 2026 with a 304% month-over-month gain to rank 1, while Ocean Fruit (3.5g) fell 77% and dropped to rank 4. Blappin Berries (3.5g) slid 34% to rank 2 even as Strawberry Kandy (3.5g) rose 20% at rank 3, and Trap Queen (7g) declined 10% at rank 5. Eight of the top ten SKUs are Flower 3.5g formats, and that concentration alongside one breakout and several double‑digit declines implies a volatile reliance on single-strain 3.5g wins rather than balanced depth across sizes.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

