

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Seaweed is stocked at 10 licensed dispensaries across Maine and New York, 9 of them in Maine, with the deepest coverage in South Portland, Bangor, Baring, Lincoln, and Northport. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
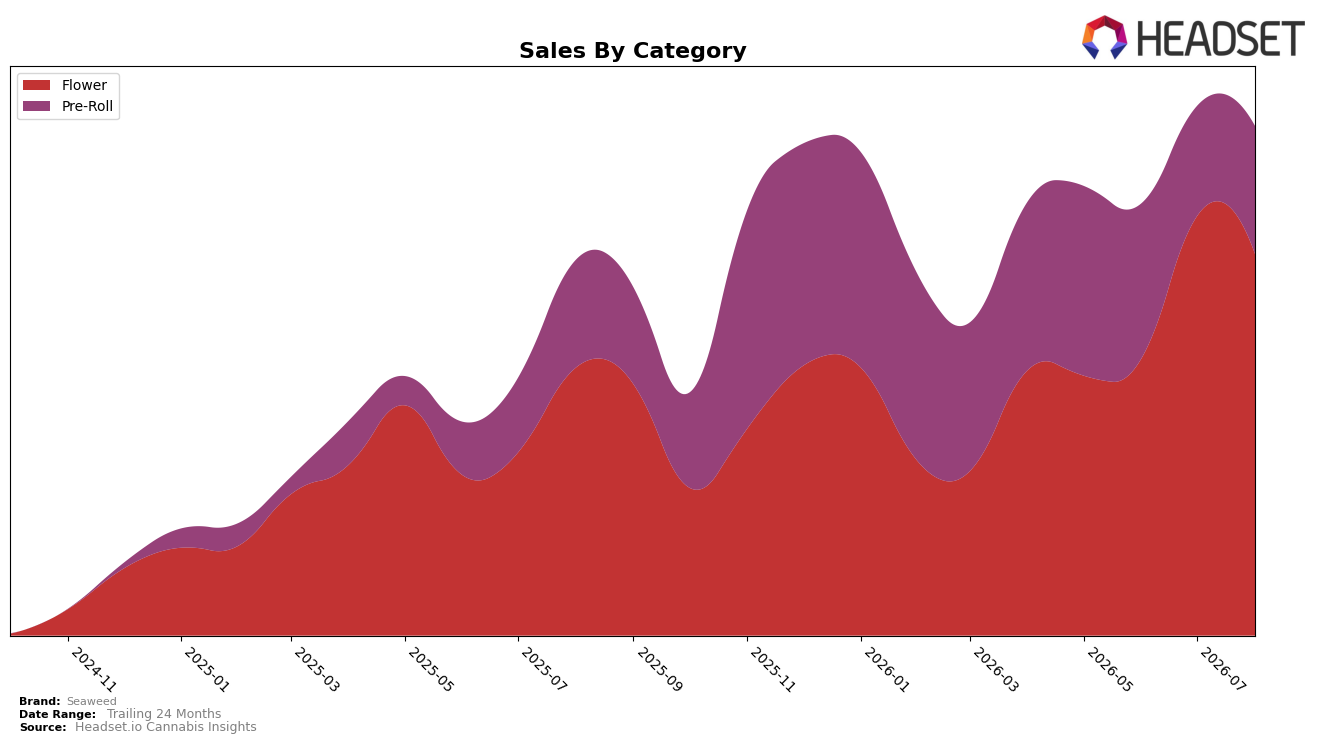
Seaweed’s category mix in August 2026 is concentrated in Flower at 74.90% share with rank 28 in Saskatchewan Flower, while Pre-Roll holds 25.10% share; the mix shifted as Flower grew 42.48% year over year but fell 9.16% month over month, whereas Pre-Roll grew 18.88% year over year and rose 16.40% month over month. The average price rose 9.51% year over year to $30.68, with Flower priced at an average of 35.70 and Pre-Roll at 21.62, and overall brand sales advanced 35.71% year over year even as the month-over-month momentum bifurcated between categories; the pattern implies Seaweed is leaning on a high-priced Flower core while near-term volume is rotating toward faster-growing Pre-Rolls.
The divergence—Flower down 9.16% month over month alongside a 16.40% month-over-month gain in Pre-Roll and rank 28 in Saskatchewan Flower—suggests price-sensitive demand is migrating to lower-priced formats even as the premium Flower strategy sustains year-over-year gains of 42.48%. With Pre-Roll only 25.10% share but accelerating month to month against a 74.90% Flower base, the implication is that Seaweed’s positioning can stabilize near-term revenue by expanding Pre-Roll assortment while using the higher average Flower price to protect margins, thereby balancing a 35.71% year-over-year brand lift with format-level volatility.
Competitive Landscape
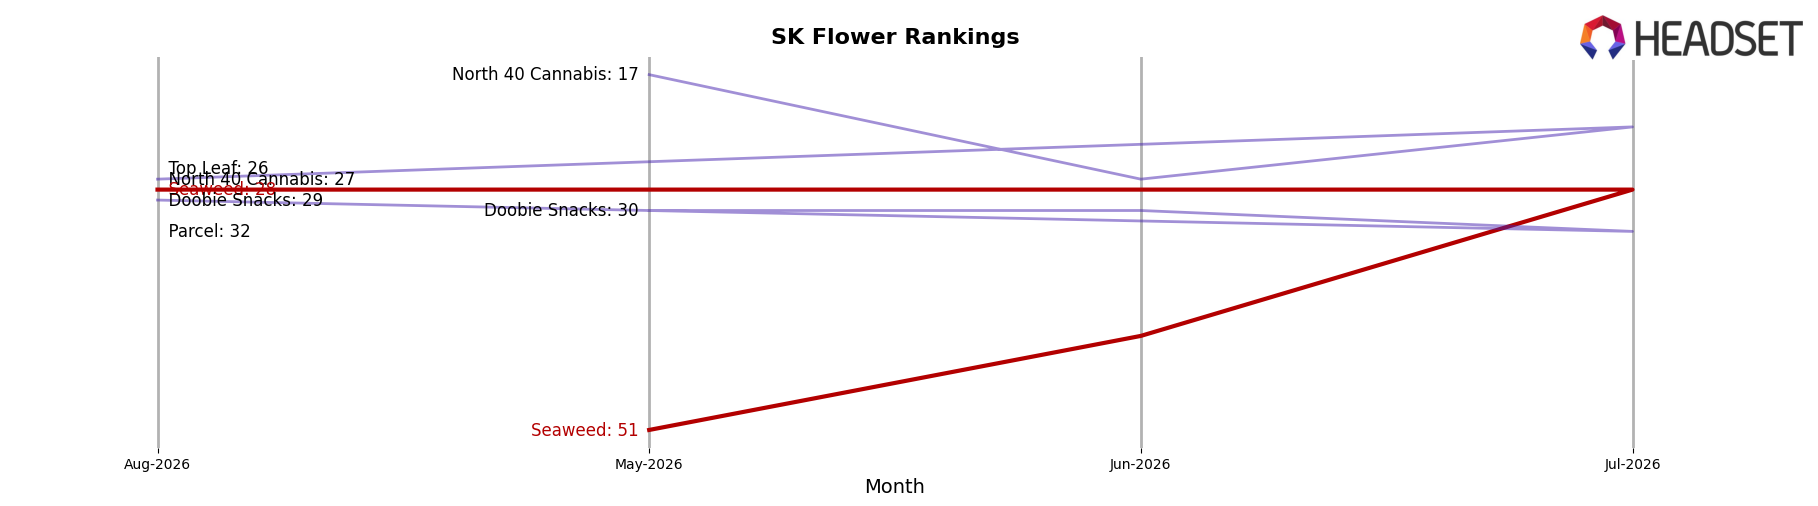
Seaweed is currently ranked #28 in SK Flower, with no year-over-year rank reported, improving from #51 three months ago and setting a peak at #28 in August 2026; this 23-position climb contrasts with Back Forty / Back 40 Cannabis holding #1 with a +3 YoY rank shift and 124.7% YoY sales growth, and Big Bag O' Buds sitting at #2 with a +8 YoY rank change and 171.2% YoY sales growth. Against the broader pack where Spinach is #3 with a +2 YoY rank change and 57.6% YoY sales lift while Weed Me advanced to #5 with a +28 YoY rank surge and 317.1% YoY sales growth, Seaweed’s late jump into the top 30 and new peak in August 2026 imply momentum driven by recent distribution or assortment gains rather than long-cycle brand pull, signaling a trajectory that needs sustained monthly share capture to defend the #28 position.
Notable Products
James Celebration Craft Rotational Hybrid Small Batch (3.5g) delivered the standout move in August 2026 with a 460.4% month-over-month surge into rank 9, while James Celebration Craft Small Batch Rotational Pre-Roll 5-Pack (2.5g) dropped 84.6% to rank 10, signaling volatility within smaller-batch extensions. Red Velvet Ice Cream (7g) held rank 1 with an 8.4% lift as Red Velvet Ice Cream (3.5g) fell 32.9% to rank 5, implying premium pack sizes are consolidating demand even as smaller flower formats retrench. Three of the top ten are Flower SKUs and four are Pre-Roll SKUs, with the Red Velvet Ice Cream Pre-Roll 10-Pack (3.5g) jumping 62.9% to rank 7 alongside The Wave Rosin Infused Pre-Roll 3-Pack (1.5g) up 37.7% at rank 6, suggesting multi-pack and infused formats are gaining traction against single-eighth dynamics. The product mix points to a tilt toward higher-value packs and experimental small-batch launches that can spike quickly but require tighter stewardship to avoid sharp pullbacks.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

