

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
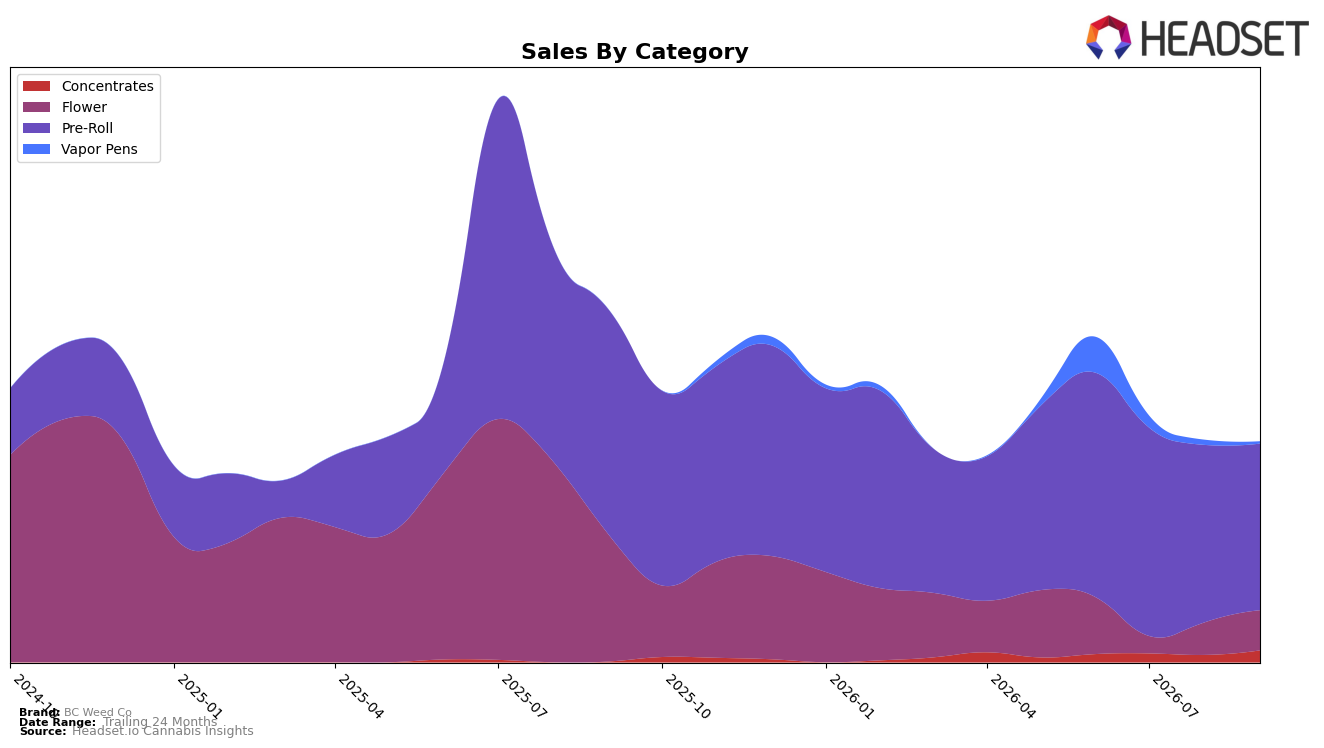
In September 2026, BC Weed Co concentrated 75.56% of sales in Pre-Roll, where sales fell 26.01% year over year and 6.10% month over month, while the brand’s overall sales declined 37.58% year over year and average price rose 3.52%. Flower accounted for 18.10% share with a 68.67% year-over-year drop but a 23.51% month-over-month rebound, and Concentrates expanded to 5.40% share on a 1,538.57% year-over-year surge and 62.03% month-over-month lift; Vapor Pens slipped to 0.94% share with a 57.97% month-over-month decline. With Pre-Roll anchoring the mix yet shrinking faster year over year than price is rising, the pattern implies over-reliance on a weakening core while rapid but small-base gains in Concentrates are beginning to diversify revenue risk.
BC Weed Co’s category shifts point to a pivot opportunity: Pre-Roll dominance at 75.56% share alongside an 80th rank in Pre-Roll in British Columbia indicates limited headroom, while the 23.51% month-over-month Flower recovery and 62.03% month-over-month Concentrates growth offer nearer-term levers. Given average prices at $23.96 and category price dispersion (e.g., Flower at $36.96 vs. Pre-Roll at $21.76), the mix can tilt toward higher-ticket and higher-growth pockets without abandoning Pre-Roll; tactically, leaning into Concentrates’ triple-digit year-over-year expansion and sustaining Flower’s month-over-month momentum would reduce sensitivity to further Pre-Roll declines and reposition the brand toward categories where incremental rank gains are more attainable.
Competitive Landscape
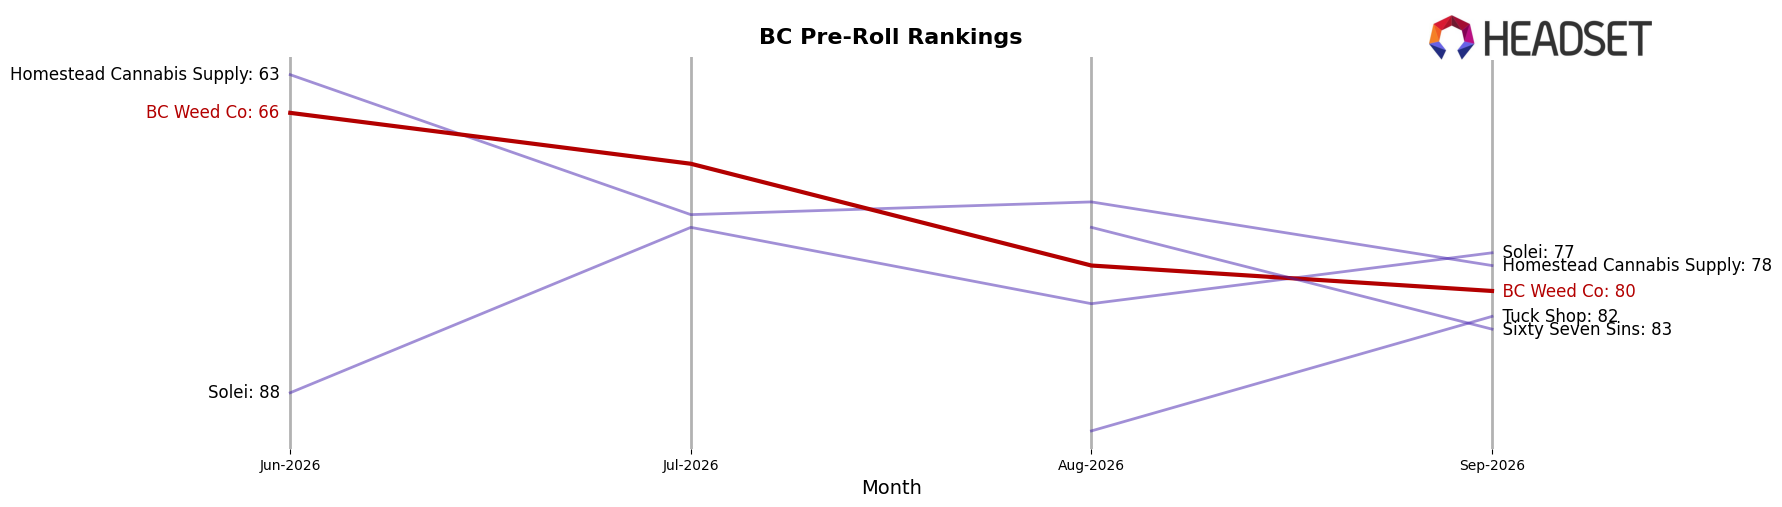
BC Weed Co ranks #80 in BC Pre-Roll in September 2026, sliding 21 positions year over year from #59, and down 14 spots since June 2026 when it was #66; this contrasts with Weed Me advancing to #1 from #2 and Back Forty / Back 40 Cannabis jumping to #2 from #13 with a 197.3% YoY sales lift, while General Admission held near the top at #3 despite an 8.5% YoY sales decline. Against its own history, BC Weed Co is far below its peak of #34 in October 2025 and has trended downward versus the category leaders whose rank deltas range from +1 to +11 at the top, implying a loss of relative shelf traction that, if unaddressed, points to continued share leakage rather than cyclic volatility.
Notable Products
Coco Bamba Pre-Roll (1g) posted the standout move with a 346% month-over-month surge and jumped into rank 6, while Frost THCA Isolate Bowl Topper (1g) rose 62% to rank 5, indicating momentum is shifting toward value-entry novelty formats. At the top, Bubba OG Pre-Roll 10-Pack (5g) fell 11% yet held rank 1, and Sour Amnesia Pre-Roll (1g) slid 9% at rank 2, signaling softness in established pre-roll leaders even as lower-priced or niche options accelerate. Flower showed mixed traction as Zoap (3.5g) climbed 180% to rank 8 and Gastro Pop Smalls (7g) rose 65% to rank 7, while Peanut Butter Breath Smalls (7g) was flat at rank 4; four of the top ten are Flower SKUs, indicating diversification beyond pre-rolls. The pattern implies BC Weed Co is tilting from large-pack pre-roll reliance toward a barbell of experimental small formats and recovering Flower variants, likely reallocating focus from high-volume anchors to growth pockets despite a $36,024 anchor at the top.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

