


Where to Buy
Bonafide Cannabis is stocked at 38 licensed dispensaries across Oregon, with the deepest coverage in Eugene, Medford, Bend, Coos Bay, and Ashland. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
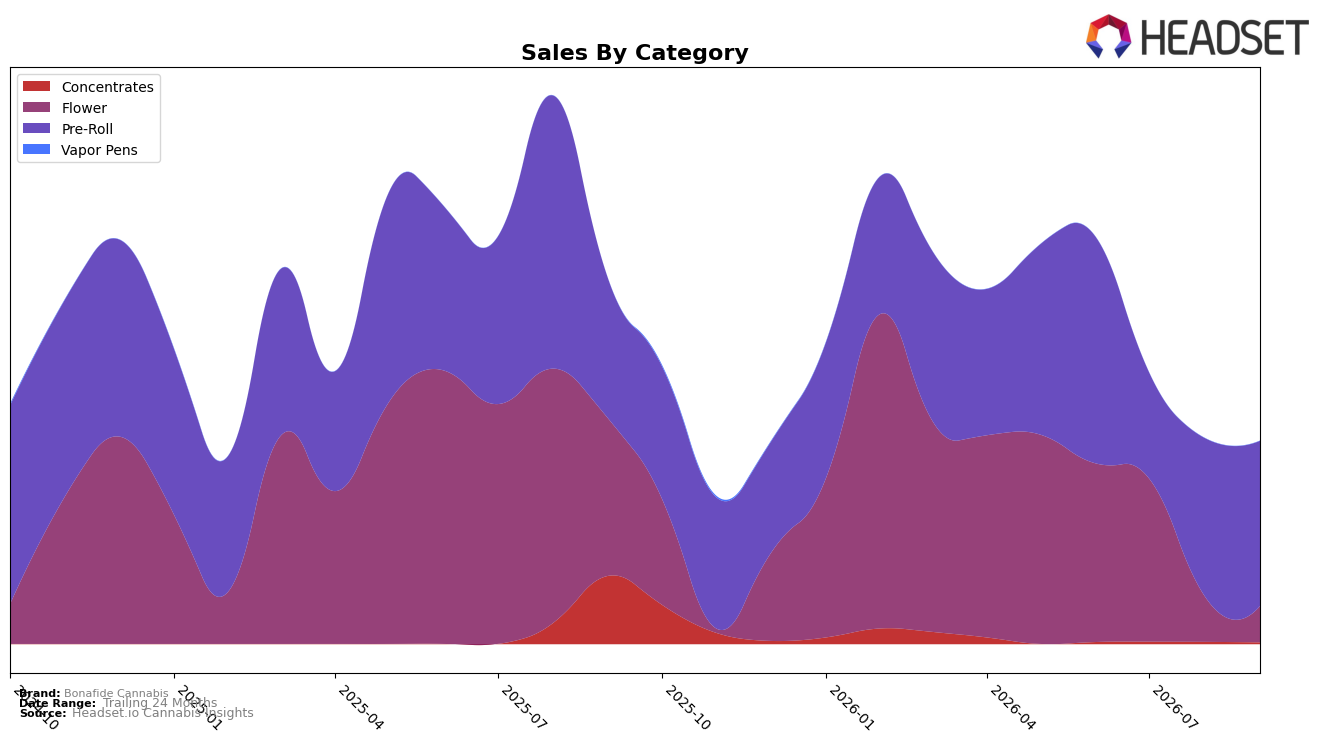
In September 2026, Bonafide Cannabis concentrated 81.45% of sales in Pre-Roll, up 18.46% year over year and 4.50% month over month, while Flower fell 77.08% YoY and 20.83% MoM to a 17.76% share. Concentrates compressed further, down 97.65% YoY and 22.86% MoM, leaving just 0.79% share. Despite a 19.94% YoY drop in average price to $17.02, Pre-Roll volume expansion offset category declines elsewhere, implying the brand is narrowing into a single-category engine as mixed portfolio contribution erodes.
With Pre-Roll ranking 45 in Oregon, the 18.46% YoY Pre-Roll growth and 4.50% MoM uptick contrast with double-digit MoM and YoY contractions in Flower and Concentrates, signaling a trade-off: depth in one lane over breadth across three. The portfolio skew raises exposure to Pre-Roll price and shelf volatility while reducing cross-category insulation, implying that short-term momentum comes from defending and scaling Pre-Roll in Oregon rather than rebuilding share in sharply declining Flower (-77.08% YoY) or Concentrates (-97.65% YoY).
Competitive Landscape
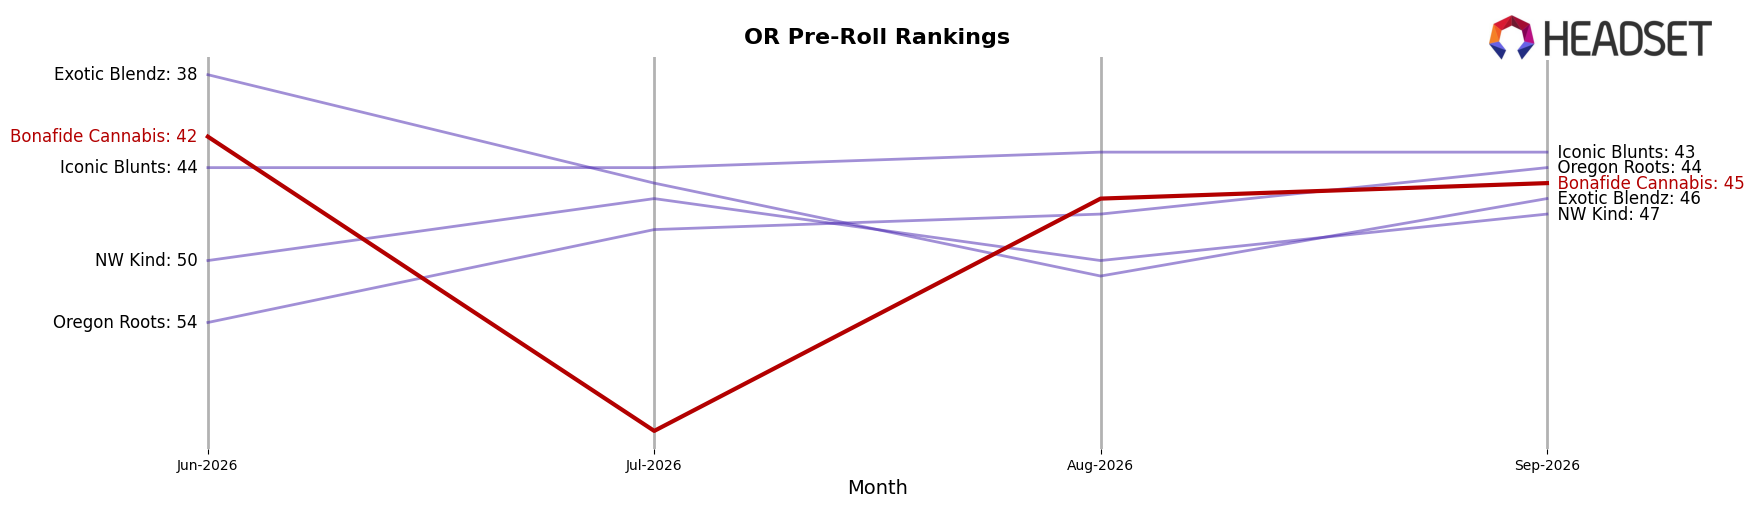
Bonafide Cannabis holds rank #45 in OR Pre-Roll for September 2026, improving 8 positions from #53 year over year, but sliding 3 spots from #42 in June 2026; against this mix, the brand remains 11 places below its peak at #34 in September 2024 and trails the category leaders where STiCKS stayed flat at #1 year over year while growing sales 91.7% and Kaprikorn climbed from #6 to #2 with 160.0% YoY sales growth. This pattern—YoY rank recovery alongside recent quarter slippage and widening gaps to rivals moving up the leaderboard—implies Bonafide Cannabis is stabilizing long term but losing short-term share of attention in late 2026 unless near-term velocity is corrected.
Notable Products
The steepest decline came from GMO Cherry Pie Pre-Roll 10-Pack (5g), down 54.6% month over month and sitting at rank 10, while Grapefruit Starburst Pre-Roll 10-Pack (5g) surged 386.2% MoM to rank 1 with $12,271 in September 2026. Wook Breath Pre-Roll 10-Pack (5g) added a 135.0% MoM gain to reach rank 2, and Sungrown Slims - Peach Slurpee Pre-Roll 10-Pack (5g) climbed 68.2% to rank 7, and eight of the top ten are Pre-Roll SKUs concentrated in multi-pack formats. This pattern implies Bonafide Cannabis is consolidating around pre-roll multi-packs as the commercial engine, accepting volatility at the tail in exchange for outsized rank gains at the top.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

