


Market Insights Snapshot
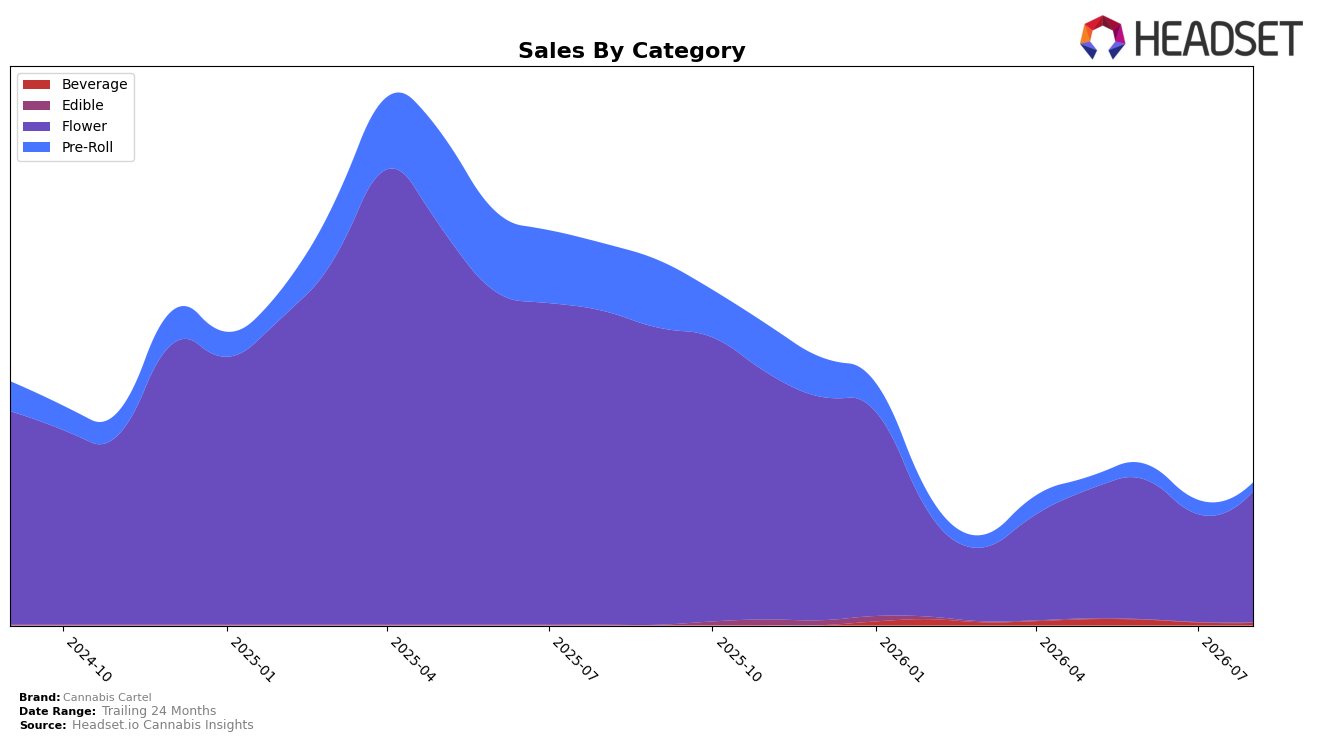
In August 2026, Cannabis Cartel concentrated 92.35% of sales in Flower, with Pre-Roll at 6.06% and Beverage at 1.58%, indicating a tighter mix than a year prior as Flower declined 58.25% YoY while Pre-Roll fell 87.25% YoY. Month over month, Flower grew 21.64% while Pre-Roll contracted 38.38% and Beverage slipped 16.65%, and the brand’s average price rose 21.72% YoY to $29.76. With overall brand sales down 62.79% YoY and a 24‑month contraction of 39.15%, the combination of heavier reliance on Flower and sharper Pre-Roll attrition implies a deliberate reweighting toward higher-ticket Flower to stabilize revenue despite category-level volume compression.
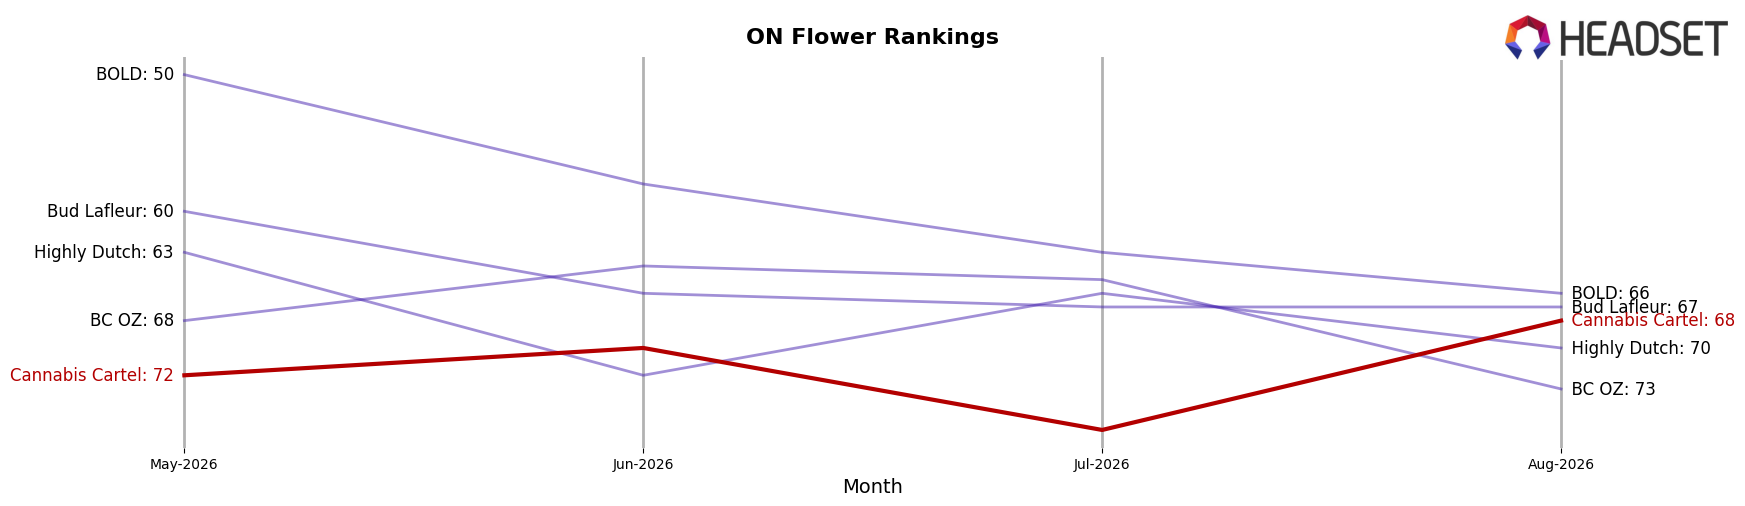
Positioning-wise, anchoring 92.35% of mix in Flower alongside a 21.64% MoM Flower lift, despite a 58.25% YoY decline, suggests the brand is prioritizing depth in a single category over breadth, trading off Pre-Roll share after a 38.38% MoM drop for margin resilience via higher average prices rising 21.72% YoY. In Ontario Flower, the brand sits at rank 68, and with Pre-Roll contracting 87.25% YoY while Beverage remains minimal at 1.58% share and fell 16.65% MoM, the pattern implies a need to defend a mid-pack Flower position through price-pack architecture and strain curation rather than chasing smaller formats that are currently dilutive to share momentum.
Competitive Landscape
Cannabis Cartel sits at rank #68 in ON Flower for August 2026, down 23 positions year over year from #45 and up 4 ranks versus three months ago from #72, indicating a mild recent lift against a longer slide. Against leaders, Shred climbed from #2 to #1 with 18.96% YoY sales growth while Cannabis Cartel moved from a peak of #31 in April 2025 to #68 in August 2026, and Spinach advanced from #4 to #2 with 27.45% YoY growth as Cannabis Cartel fell 23 YoY ranks, marking share migration toward scale brands; the trajectory implies Cannabis Cartel is ceding rank concentration to top performers unless recent quarter-on-quarter stabilization converts into sustained rank recovery.
Notable Products
Motorbreath (3.5g) posted the largest month-over-month gain at 234%, vaulting into rank 8 while Ice Cream Wizard (7g) fell 32% to rank 3. Ice Cream Wizard (3.5g) still held rank 1 with a 41% increase, and Dragon Pendant Pre-Roll (1g) slid 43% to rank 2. Four of the top ten are Flower SKUs, and their mixed trajectory — one up 234% and another down 32% alongside a 41% leader — indicates the brand is concentrating demand into a few standout Flower formats at the expense of underperforming sizes.
Jordan X (14g) declined 20% to rank 9, while the CBG/THC 1:1 Coconut Ice Crm Wizard Soda (10mg CBG, 10mg THC, 12oz, 355ml) dropped 26% at rank 5 even as the Pineapple Sparkling Coconut Water variant rose 37% at rank 10. Ace Ganja Bombers Pre-Roll 3-Pack (1.5g) eased 9% to rank 4, leaving Pre-Rolls split between a 43% decline and a single-digit dip. This divergence — steep Beverage volatility and uneven Pre-Roll momentum alongside rank 1 Flower growth — implies Cannabis Cartel is tilting its commercial focus toward premium Flower while keeping niche beverages as opportunistic add-ons rather than scale drivers.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

