

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
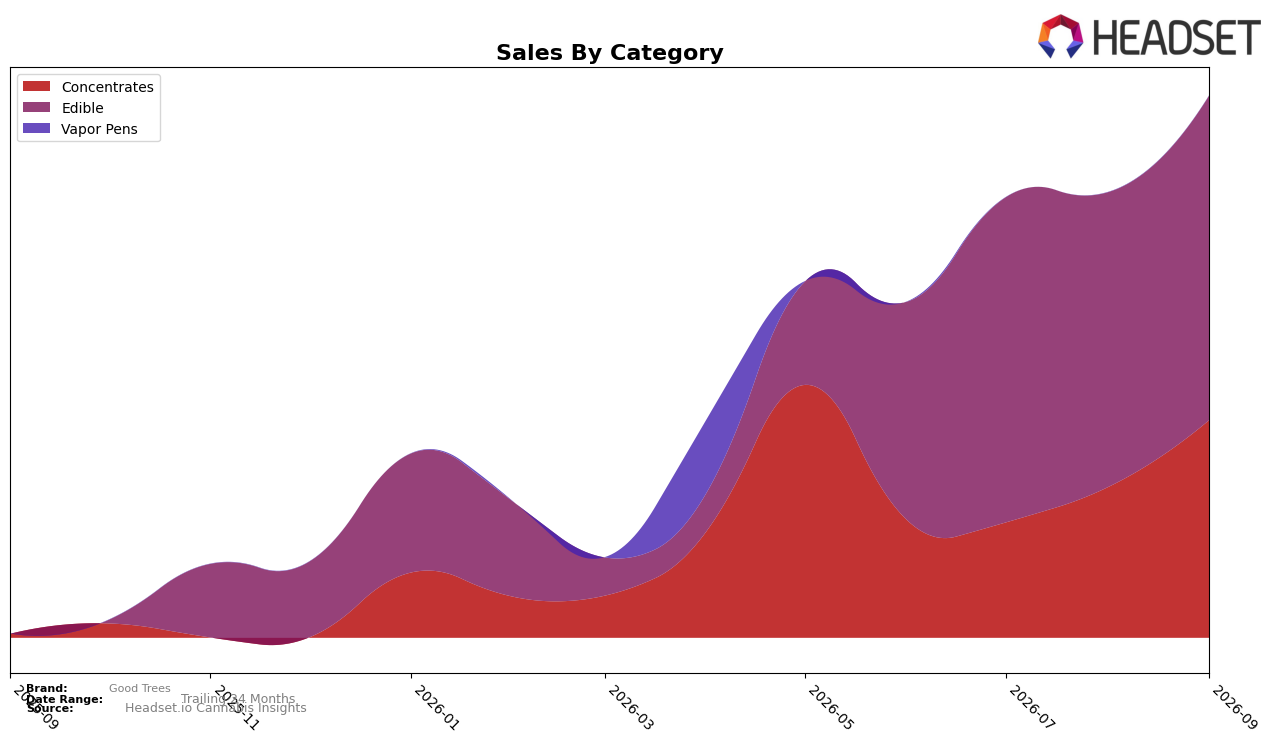
Good Trees concentrated nearly three-fifths of September 2026 sales in Edible at 59.9% share while Concentrates accounted for 40.1% share, a split that shifted month over month as Edible advanced 10.1% MoM but Concentrates accelerated 44.9% MoM. Year over year, Concentrates expanded 5,766.5% while Edible reported no comparable YoY figure, and the brand’s average price fell 62.5% YoY to $13.21 alongside a category-level price point of $9.59 in Edible versus $30.26 in Concentrates. The pattern implies a portfolio tilt toward higher-velocity, lower-priced Edible for volume while rapid MoM gains in higher-priced Concentrates lift revenue mix and widen price tiers.
Within Colorado Edible, Good Trees held rank 30, and the 59.9% Edible share paired with a 40.1% Concentrates share suggests a barbell positioning between value-driven Edible and premium-priced Concentrates. With Concentrates rising 44.9% MoM against Edible’s 10.1% MoM, and the overall brand up 14,517.8% YoY on sharply lower average price, the mix signals a strategy where price-accessible Edible fuels trial and distribution while Concentrates’ faster momentum and 5,766.5% YoY expansion provide the ladder for margin recovery. The thesis is that Good Trees is migrating from a single-category Edible identity toward a two-pillar stance, using Edible scale to anchor shelf presence while Concentrates growth repositions the brand toward a broader, tiered value proposition.
Competitive Landscape
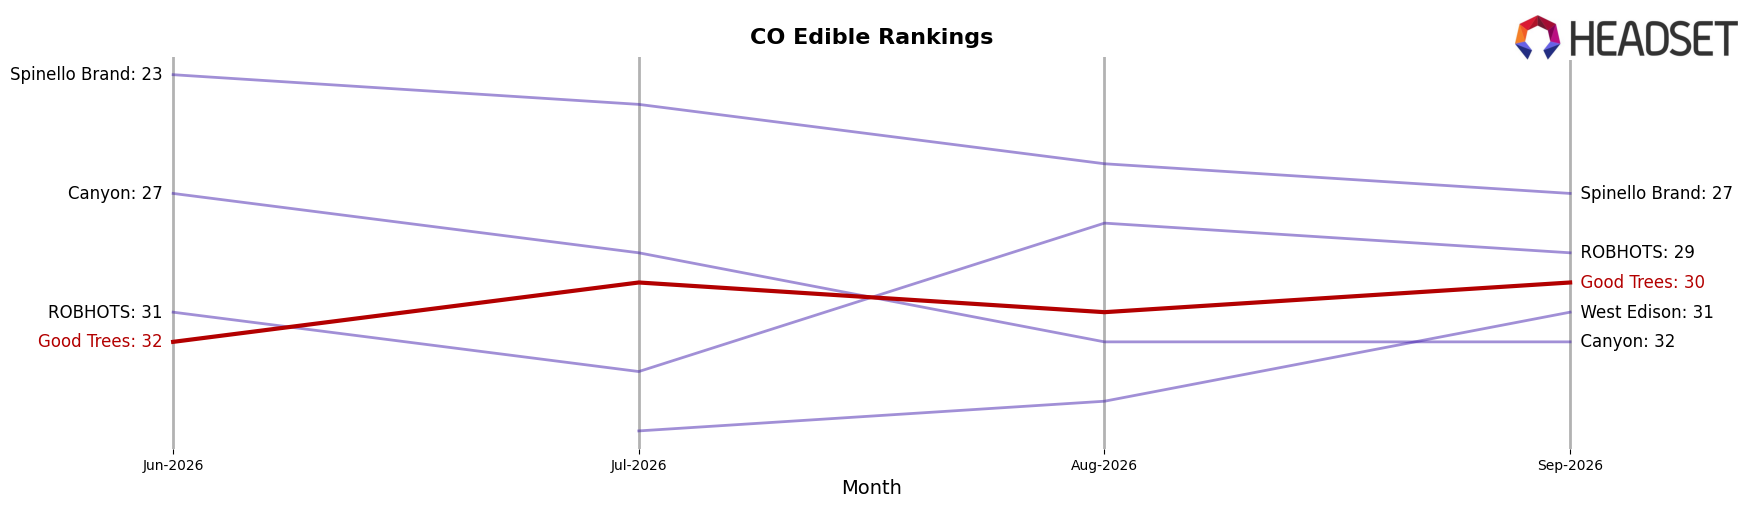
Good Trees sits at rank #30 in Colorado Edible in September 2026, up 2 positions from #32 in June 2026, but with no year-over-year rank reported; this marks a new peak at #30 while the three-month improvement of 6.3% in rank position (from 32 to 30) still leaves a wide gap to leaders. Competitors moved in divergent directions: Wana holds #1 with a +1 YoY rank gain to 2 last year translating to 10.5% YoY sales growth, while Wyld is #2 after sliding from #1 YoY amid a 23.8% YoY sales decline; Dialed In Gummies remains #3 with 30.6% YoY sales growth. The combination of Good Trees’ 2-rank climb since June 2026 and the leaders’ mixed YoY momentum implies an opening: steadier incremental share capture can compound if Good Trees converts from sporadic peaks to sustained monthly rank gains.
Notable Products
Green Apple Gummy (100mg) posted the standout move in September 2026 with a 156% month-over-month surge to $9,128, lifting it to rank 1 while Blue Raspberry Rosin Gummies 10-Pack (100mg) fell 51% to rank 2. Edibles occupy 3 of the top 3 ranks compared with Concentrates occupying ranks 4 through 8, indicating category polarization where one hero edible outpaces a declining peer by over 200 percentage points of MoM spread and holds a one-position lead at the top. This pattern implies Good Trees is leaning into a single high-velocity edible while the rest of the assortment skews toward mid-table Concentrates, steering the product mix toward an anchor-SKU strategy with category depth rather than broad edible parity.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

