


Where to Buy
Grams (NY) is stocked at 21 licensed dispensaries across New York, with the deepest coverage in New York, Brooklyn, Queens, Albany, and Coram. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
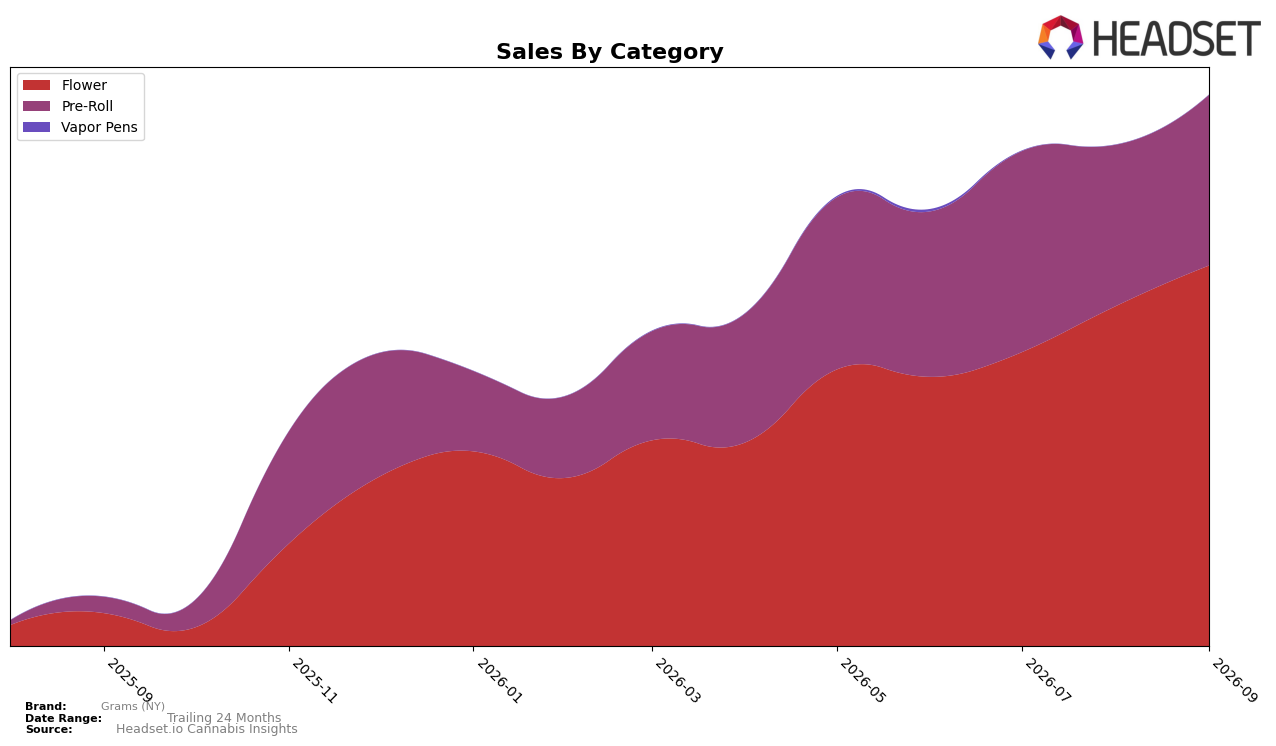
In September 2026, Grams (NY) concentrated 69.07% of sales in Flower with a 12.03% month-over-month lift, while Pre-Roll held 30.93% share with a 5.81% MoM increase; year-over-year, Flower expanded 1054.30% and Pre-Roll advanced 963.14%. Average price across the portfolio fell 17.19% YoY to $20.72, contrasting with a higher Flower average of $39.94, indicating mix weight shifting toward a higher-ticket segment even as price pressure persisted. The pattern implies that demand growth is volume-led with incremental premiumization inside Flower, and that sequential momentum favored Flower over Pre-Roll, tilting the mix toward categories with faster unit velocity despite price deflation.
With Flower ranked 49th in New York and capturing 69.07% of the brand’s mix amid 12.03% MoM growth, Grams (NY) is leaning into a scale-first positioning where Flower drives reach while Pre-Roll (30.93% share, 5.81% MoM) functions as an entry-price feeder. The 1054.30% YoY surge in Flower alongside a 963.14% YoY rise in Pre-Roll, paired with a 17.19% YoY drop in average price, implies the brand is trading down on price to accelerate store and basket penetration, using Flower as the lead engine and Pre-Roll as complementary trial — a setup that prioritizes shelf breadth and unit throughput over premium pricing power.
Competitive Landscape
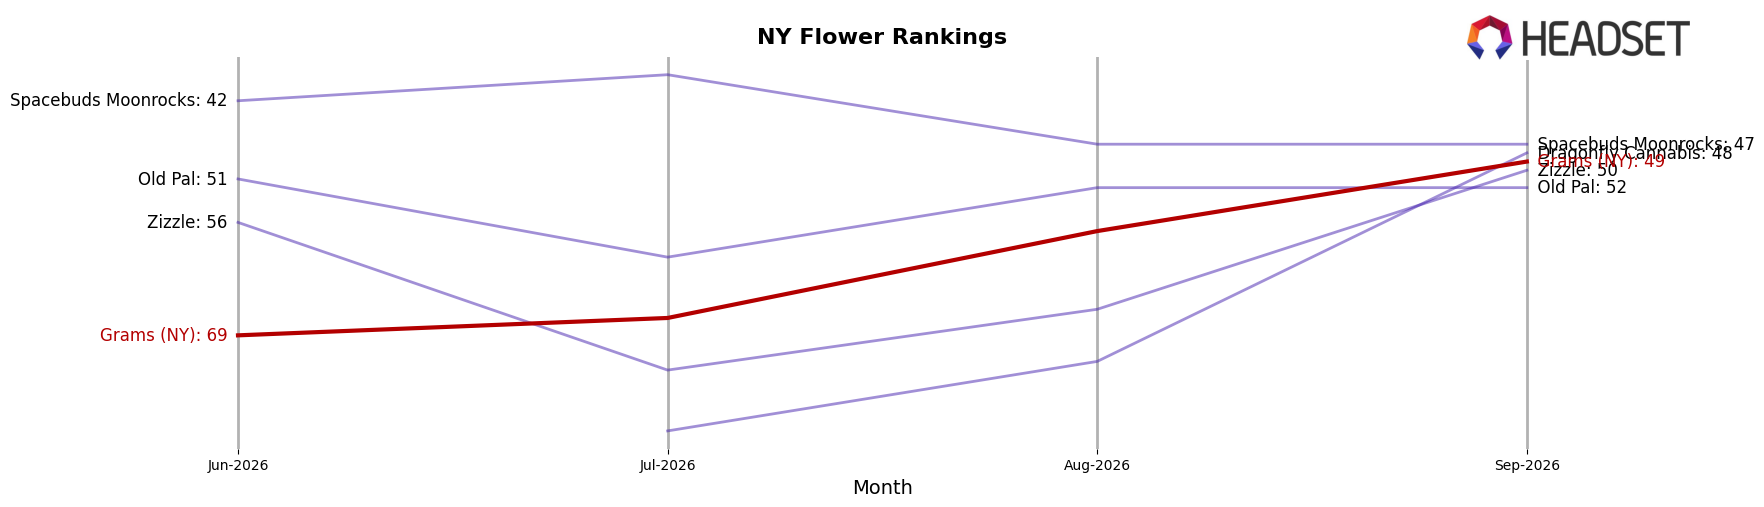
Grams (NY) is ranked #49 in NY Flower in September 2026, improving 137 positions year over year from #186, and rising 20 spots versus June 2026 when it sat at #69; this coincides with reaching a peak rank of #49 in September 2026 and moving closer to category leaders where Find. advanced from #5 to #1 while Grassroots climbed from #15 to #2 alongside a 150.33% YoY sales increase. Against mid-tier movers like Untitled shifting from #9 to #3 with 44.88% YoY growth and RYTHM moving from #8 to #5 with 20.30% YoY growth, Grams (NY)’s 137-place YoY rise and 20-place three-month gain point to distribution or assortment changes translating into sustained share capture rather than a short-lived spike.
Notable Products
Divorcee Cake Pre-Roll (1g) posted the standout move in September 2026 with a 61.3% month-over-month rise to rank 3, while Pastelito Pre-Roll (1g) fell 17.6% to rank 7 and Nepal Diesel Pre-Roll (1g) declined 14.7% at rank 8. Frankenstein Pre-Roll (1g) also surged 56.1% at rank 10, and four of the top ten are Pre-Roll SKUs concentrated between ranks 2 and 8, indicating mix shift within the format. Vanilla Coke (3.5g) held rank 1 as the lead Flower anchor alongside Orange Tiki Cream (3.5g) at rank 9, concentrating category breadth even as Pre-Rolls carry the volatility. The pattern implies Grams (NY) is leaning into a Pre-Roll-led volume engine with episodic winners driving share swings, while a two-item Flower spine stabilizes the ladder.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

