

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Habitat (CA) is stocked at 93 licensed dispensaries across California, with the deepest coverage in Los Angeles, El Monte, Santa Rosa, Modesto, and Lancaster. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
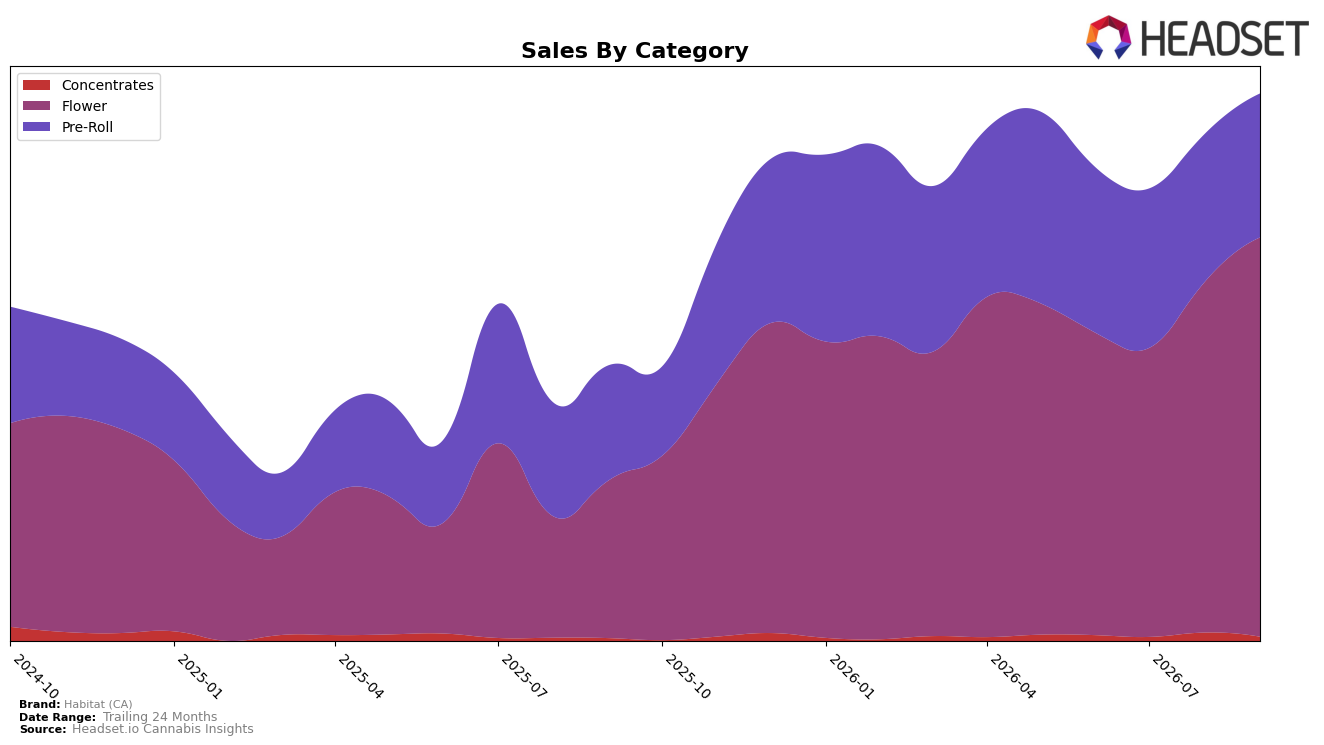
Habitat (CA) concentrated 71.07% of September 2026 sales in Flower with year-over-year growth of 145.58% and month-over-month growth of 13.57%, while Pre-Roll held 26.60% share with 23.12% YoY and a -2.61% MoM dip; Concentrates contributed 2.33% share with 11.66% YoY and a -23.68% MoM slide. Average price rose 14.22% YoY to $23.99, while Flower priced at an estimated $33.99 outpaced the portfolio mix, implying a revenue-weighted tilt toward higher-priced Flower even as Pre-Roll softens; the pattern implies Habitat (CA) is leveraging momentum in Flower to drive overall 90.00% YoY brand growth despite drag from smaller, declining segments.
With Flower ranked 50th in California and commanding 71.07% share of brand sales, the 13.57% MoM lift in Flower versus a -2.61% MoM decline in Pre-Roll indicates a positioning anchored in premiumized Flower rather than breadth across form factors. The 2.33% share and -23.68% MoM in Concentrates, alongside a 26.60% Pre-Roll share with only 23.12% YoY, suggest portfolio concentration risk; the pattern implies Habitat (CA) can defend and potentially improve a 50th rank in Flower by continuing to convert demand at higher price points, but sustained growth will depend on stabilizing Pre-Roll mix and containing volatility in smaller categories.
Competitive Landscape
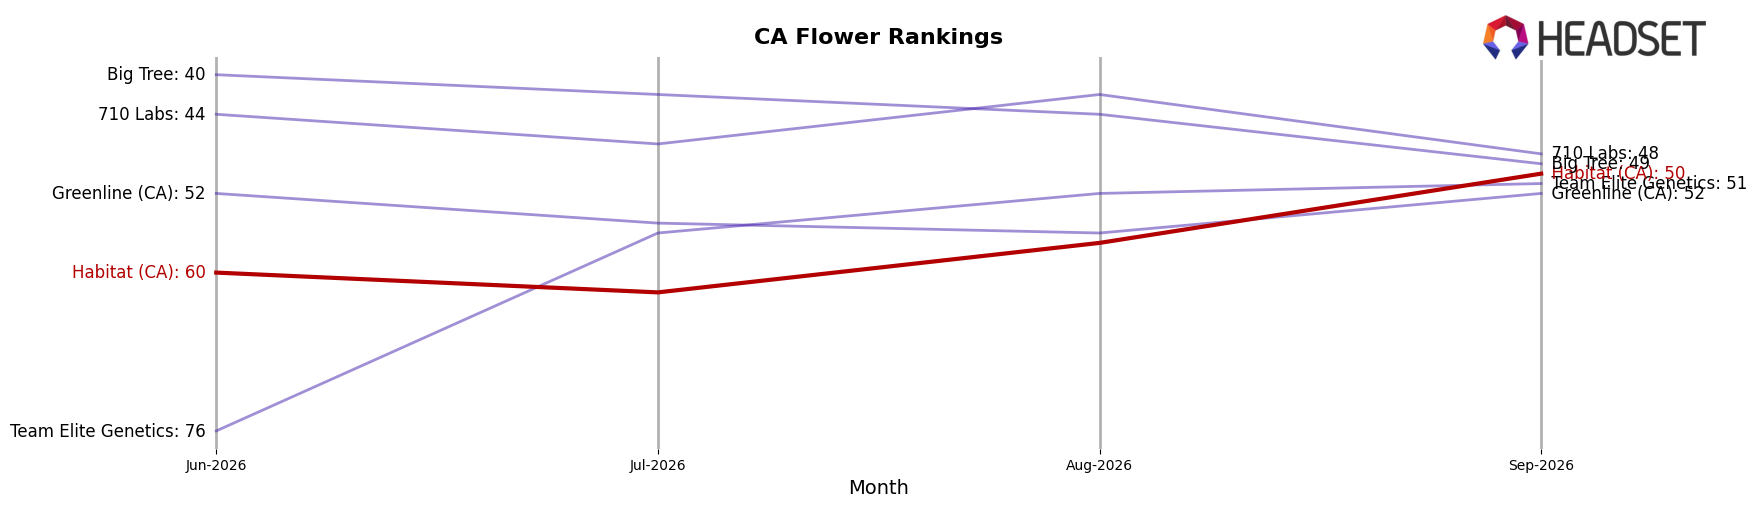
Habitat (CA) sits at rank #50 in California Flower in September 2026, improving 62 positions year over year from #112 while gaining 10 places versus June 2026 from #60, reaching a new peak at #50 in September 2026; by comparison, STIIIZY advanced from #2 to #1 with 47.8% YoY sales growth and CannaBiotix (CBX) slipped from #1 to #3 with a 21.1% YoY sales decline. Oakfruitland’s move from #11 to #5 alongside 73.5% YoY sales growth and CAM edging from #3 to #2 with 28.9% YoY growth indicate a tightening top tier; Habitat (CA)’s climb into the top 50 amid upward pressure from faster-rising peers implies the brand is transitioning from fringe to mid-pack, but sustaining share will require outpacing competitors that are accelerating rankings more rapidly.
Notable Products
Legend OG (3.5g) posted the steepest movement in September 2026 with a -25.95% month-over-month drop while slipping to rank 9, contrasting with Champagne (3.5g) which climbed 38.46% month over month to rank 4. Space Lemonade Pre-Roll (1g) held rank 1 with an 8.28% month-over-month gain and Champagne Pre-Roll (1g) advanced 16.75% to rank 2, indicating momentum concentrated at the top of the Pre-Roll list. Four of the top ten are Pre-Roll SKUs, yet two Flower SKUs within the same Champagne and Roze families sit at ranks 4 and 6, signaling a cross-format franchise effect that shifts mix toward higher-velocity strains rather than a single-category bet.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

