
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
High Ledges Cannabis is stocked at 42 licensed dispensaries across Massachusetts, with the deepest coverage in Boston, Pittsfield, Easthampton, Framingham, and Newton. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
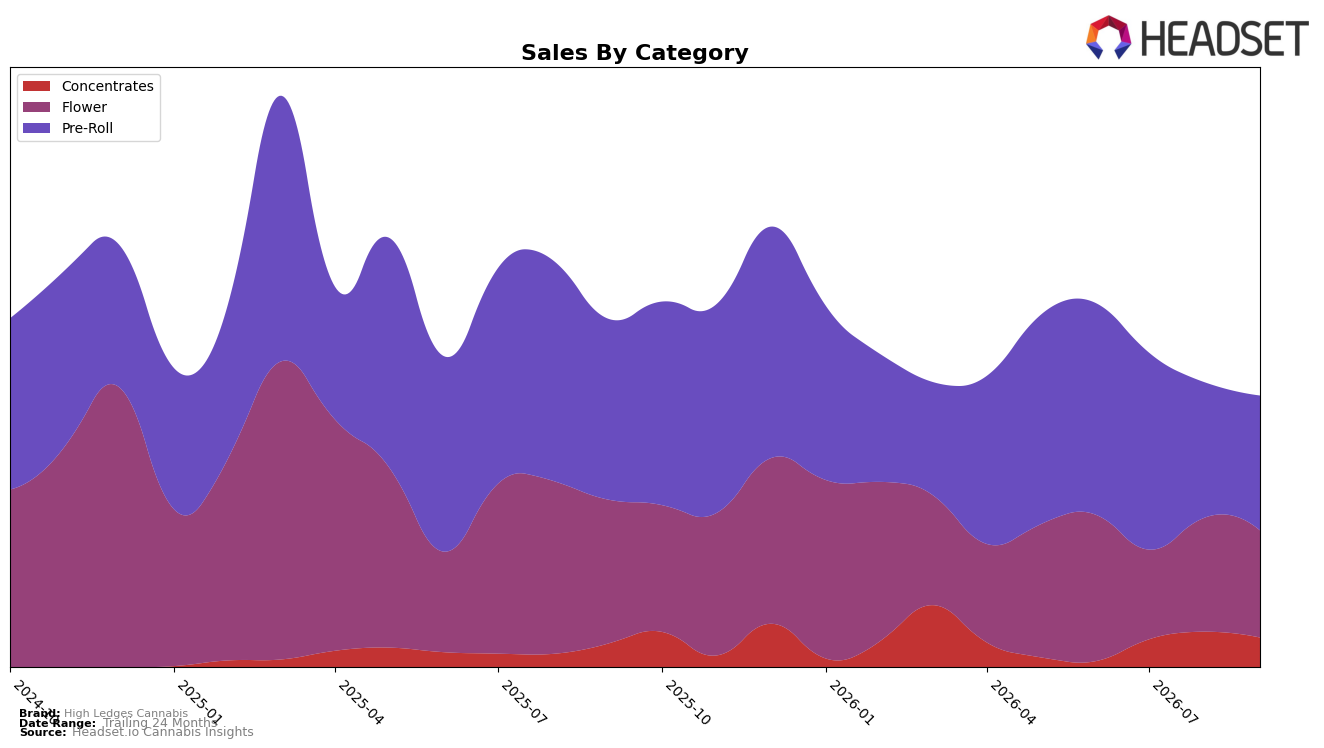
High Ledges Cannabis concentrated nearly half of September 2026 sales in Pre-Roll at 49.65% share, with year-over-year Pre-Roll sales down 25.48% and month-over-month down 0.42%, while Flower held 39.42% share with steeper contractions of 25.60% YoY and 6.04% MoM. Concentrates rose 25.38% YoY but slipped 16.45% MoM, ending at an 10.93% share and the highest category average price at $71.18. With an overall brand sales decline of 22.08% YoY and a 4.39% YoY average price increase to $21.87, the mix skews toward lower-priced Pre-Roll (avg price $15.30) while higher-priced Concentrates remain too small to offset category-level pullbacks, implying the portfolio is overweight categories with larger volume declines and underweight the only YoY growth pocket.
In Massachusetts Pre-Roll, a rank of 89 alongside a 49.65% internal share and a 0.42% MoM dip signals limited velocity within the brand’s primary category, while Flower’s 39.42% share paired with a 6.04% MoM decline indicates the second pillar is dragging momentum more than the core. The 25.38% YoY rise in Concentrates at just 10.93% share suggests a viable premium-led counterweight, but the 16.45% MoM contraction shows inconsistent demand month to month; the positioning implication is to rebalance toward the growing premium subcategory while arresting Flower’s steeper MoM erosion to lift rank from 89 through mix and pricing that convert category presence into sustained velocity.
Competitive Landscape
High Ledges Cannabis sits at rank #89 in MA Pre-Roll for September 2026, down 9 positions year over year from #80, and it is also 9 positions below its three-month mark of #80, while still 38 spots beneath its March 2025 peak at #51; by contrast, Jeeter held #1 both year over year and in September 2026 with a 25.6% YoY sales increase, and Northern Grown advanced from #10 to #5 alongside a 97.6% YoY sales gain, indicating that High Ledges Cannabis is ceding rank to competitors that are consolidating top-tier positions and accelerating, which implies a sustained slide toward the long tail unless distribution or assortment shifts redirect its trajectory.

Notable Products
Blue Zushi Pre-Roll (1g) posted the steepest movement in September 2026 with a -42.7% month-over-month change and sat at rank 6, while GMO Pre-Roll (1g) declined -6.3% at rank 1, indicating pressure within single-count pre-rolls despite top billing. GMO Pre-Roll 5-Pack (2.5g) rose 21.3% month over month at rank 2, whereas GMO (3.5g) in Flower inched up 2.4% at rank 3, and seven of the top ten products were Pre-Roll SKUs, concentrating demand in ready-to-smoke formats. With one multi-pack pre-roll gaining double digits alongside a sharp drop in a single, the mix implies a pivot toward value and convenience packs as the defensible lane for High Ledges Cannabis.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

