

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Home Grown is stocked at 115 licensed dispensaries across California, Mississippi, and Vermont, 111 of them in California, with the deepest coverage in San Diego, Los Angeles, Sacramento, Santa Ana, and La Mesa. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
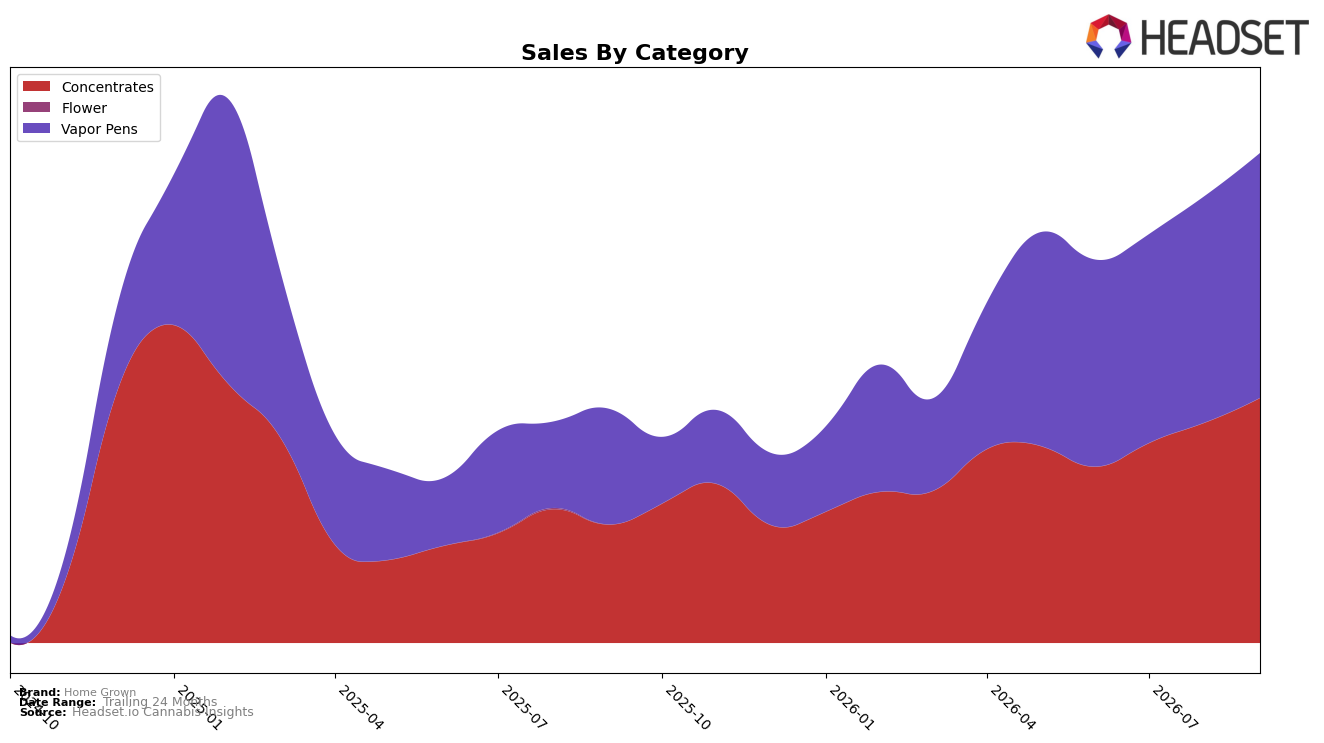
Home Grown split its September 2026 mix almost evenly between Vapor Pens at 50.0% share and Concentrates at 50.0% share, with Vapor Pens up 111.8% year over year and 8.1% month over month while Concentrates rose 107.1% year over year and 11.2% month over month. Despite a 13.5% year-over-year drop in average price to $18.60, total brand sales grew 109.4% year over year, indicating volume expansion outpacing price compression; the thesis is that a balanced category portfolio with dual triple-digit YoY lifts is amplifying unit throughput even as pricing trends down.
With Vapor Pens ranked 95th in California within its category and carrying 50.0% of the brand mix, the 8.1% MoM gain versus Concentrates’ 11.2% MoM suggests incremental share-of-growth is leaning to Concentrates while Vapor Pens anchors distribution. The implication is that Home Grown’s positioning benefits from maintaining Vapor Pens for placement and discovery while using faster MoM growth in Concentrates to pull overall rank upward in California; the thesis is that near-term share wins will likely accrue from Concentrates-led velocity while Vapor Pens sustains baseline shelf presence.
Competitive Landscape
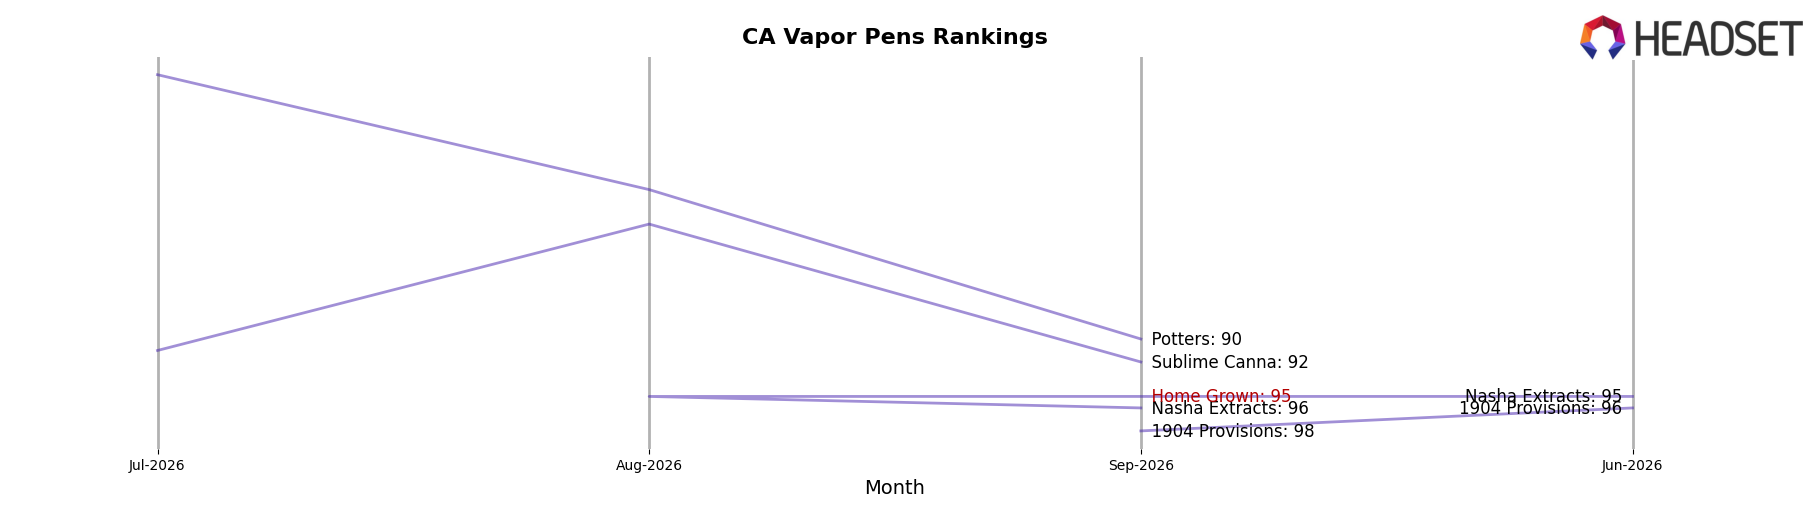
Home Grown ranks #95 in CA Vapor Pens in September 2026, improving 31 places from #126 year over year and rising 15 positions from #110 in June 2026; however, it remains below its #84 peak from February 2025. At the top end, STIIIZY held #1 year over year despite a -16.7% sales change, while Jetty Extracts climbed from #4 to #3 with +45.2% YoY sales growth, indicating that category gains are concentrating among leaders as mid-tier brands like Home Grown advance by double-digit rank steps but still trail the pace of the frontrunners; the trajectory implies Home Grown is transitioning from fringe to lower mid-tier, with further share capture dependent on sustaining quarter-on-quarter rank gains of roughly 10–20 positions.
Notable Products
Lemon Runtz Live Resin FSO (1g) posted the standout move in September 2026 with a +69.4% MoM surge to rank 2, while Private Reserve OG Live Resin FSO (1g) fell -22.4% and slipped to rank 5, indicating a decisive shift within the same format tier. Bubblegum Kush Live Resin FSO (1g) rose +26.5% and held rank 1, and Purple Octane Cured Resin Applicator (1g) climbed +57.5% at rank 6, so three of the top six are Concentrates with double-digit gains that outpace the Vapor Pens cluster sitting at ranks 7–9. With Concentrates occupying ranks 1–6 except for a Vapor Pens pocket at 7–9 and four of the top ten coming from Concentrates’ FSO/applicator family, the mix points to Home Grown consolidating around resin-based formats rather than expanding pen-led breadth.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

