


Where to Buy
Hotbox Farms (OR) is stocked at 14 licensed dispensaries across Oregon, with the deepest coverage in Portland, Eugene, Bend, Brookings, and Lincoln City. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
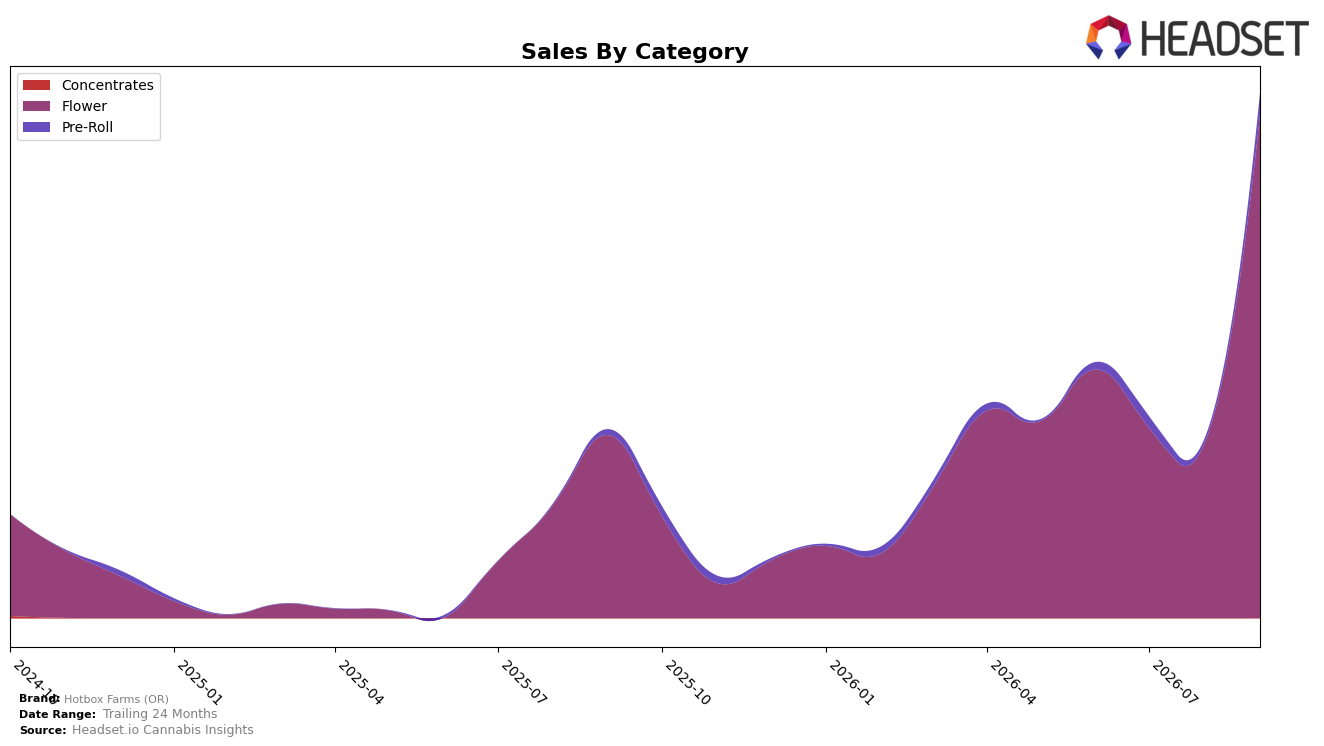
In September 2026, Hotbox Farms (OR) concentrated 96.03% of sales in Flower with the remaining 3.97% in Pre-Roll, while Flower grew 175.94% year over year and 188.38% month over month; Pre-Roll expanded even faster at 275.02% YoY and 383.50% MoM. Despite an average price of $14.62 across the portfolio and a 26.72% YoY price decline, category-level pricing diverged, with Flower averaging $16.33 and Pre-Roll at $4.15. The pattern implies a volume-led expansion centered on Flower in OR, with an early-stage push in value-priced Pre-Roll accelerating mix breadth without yet shifting the core reliance on Flower.
Given a 178.86% brand-level YoY sales increase alongside a 25.87% 24‑month gain, the surge concentrates in recent months as Flower’s 188.38% MoM outpaces long-horizon growth, while Pre-Roll’s 383.50% MoM signals a rapid trial-and-scale dynamic. Coupled with a category rank of 46 in Flower in Oregon and a 96.03% mix share, the skew indicates positioning as a Flower-first operator using low-price Pre-Roll to acquire baskets; the implication is that sustaining share gains will depend on translating Pre-Roll’s 3.97% mix into repeat contribution while maintaining Flower momentum within OR.
Competitive Landscape
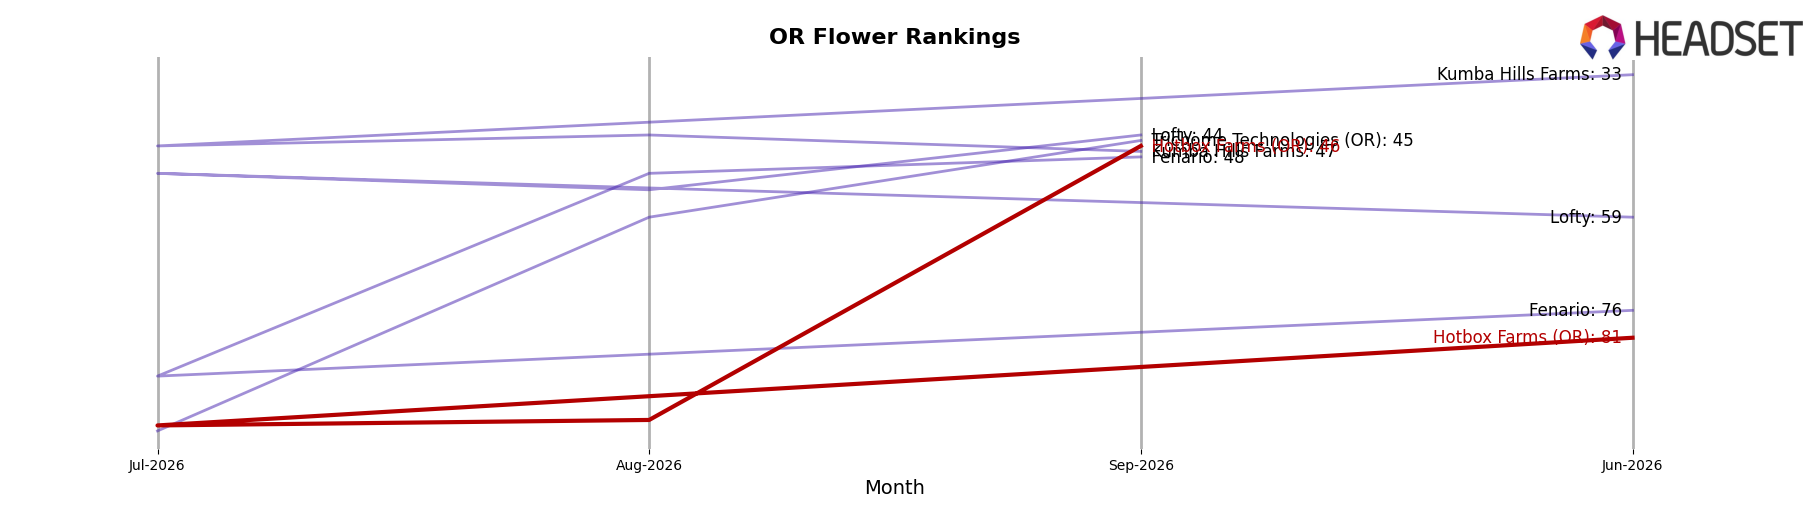
Hotbox Farms (OR) sits at rank #46 in OR Flower in September 2026, climbing 57 positions year over year from #103 while improving 35 ranks since June 2026 from #81, marking its peak rank to date at #46 in September 2026. Against this backdrop, Grown Rogue advanced to #1 from #3 with 63.8% YoY sales growth, and Oregrown rose to #3 from #16 with 169.7% YoY growth, indicating that Hotbox Farms (OR)’s upward movement is occurring in a ladder where leaders are accelerating faster; the trajectory implies share recovery via rank gains, but the gap to the top tier is widening unless recent momentum converts into sustained, above-market penetration.
Notable Products
With no SKU posting a month-over-month swing above +50% or below -10% in September 2026, the subtler movement is led by Jack Herer (Bulk), which climbed to rank 9 with a +39.34% MoM increase while Acai Gelato (Bulk) slid to rank 10 with a -5.92% MoM change. Top spots are anchored by Flower, with 100 Racks (3.5g) at rank 1 and The Soap (3.5g) at rank 2, and four of the top five ranks are Flower SKUs, indicating category concentration alongside mid-tier volatility. Permanent Lee Hi (Bulk) at rank 7 gained +23.56% MoM, while The Soap (28g) held rank 4 with $23,717 in September 2026 sales, suggesting that higher-quantity Flower formats sit just behind eighths as volume drivers. The pattern implies Hotbox Farms (OR) is consolidating around Flower dominance while using Bulk gains to backfill growth under the flagship eighths.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

