

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
The Network is stocked at 33 licensed dispensaries across Oregon, with the deepest coverage in Portland, Salem, McMinnville, Astoria, and Corvallis. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
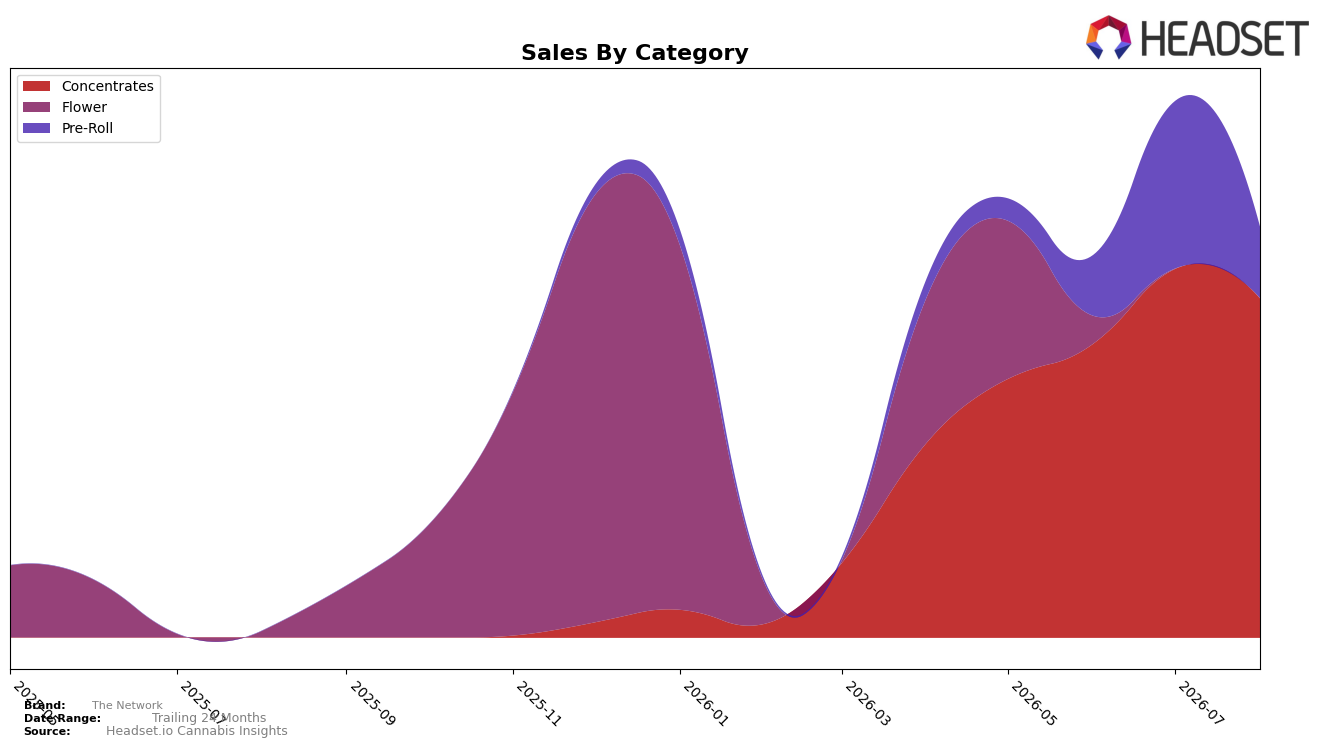
In August 2026, The Network remained heavily concentrated in Concentrates at 82.68% share while Pre-Roll held 17.32%, with Concentrates declining month over month by 8.00% and Pre-Roll falling by 57.54%. The average price spread between categories was wide, with Concentrates at $13.68 and Pre-Roll at $1.67, and the brand’s overall average price at $6.09 implies mix-driven compression as Pre-Roll volume contracted alongside the 8.00% Concentrates pullback. In Oregon Concentrates, The Network sat at rank 27, and the combination of an 82.68% mix weight and a rank in the high 20s indicates that overreliance on one category is limiting share capture in that market.
The 57.54% month-over-month decline in Pre-Roll against an 8.00% dip in Concentrates suggests that tactical reductions are falling disproportionately on lower-price items, which, paired with an 82.68% Concentrates mix, positions the brand as a specialist rather than a balanced portfolio. Sitting at rank 27 in Oregon while carrying 82.68% of sales in Concentrates implies headroom comes from deepening within that category rather than diversifying immediately, but the 17.32% Pre-Roll share and its steep month-over-month decline warn that dependency on one segment raises volatility risk if rank pressure intensifies.
Competitive Landscape
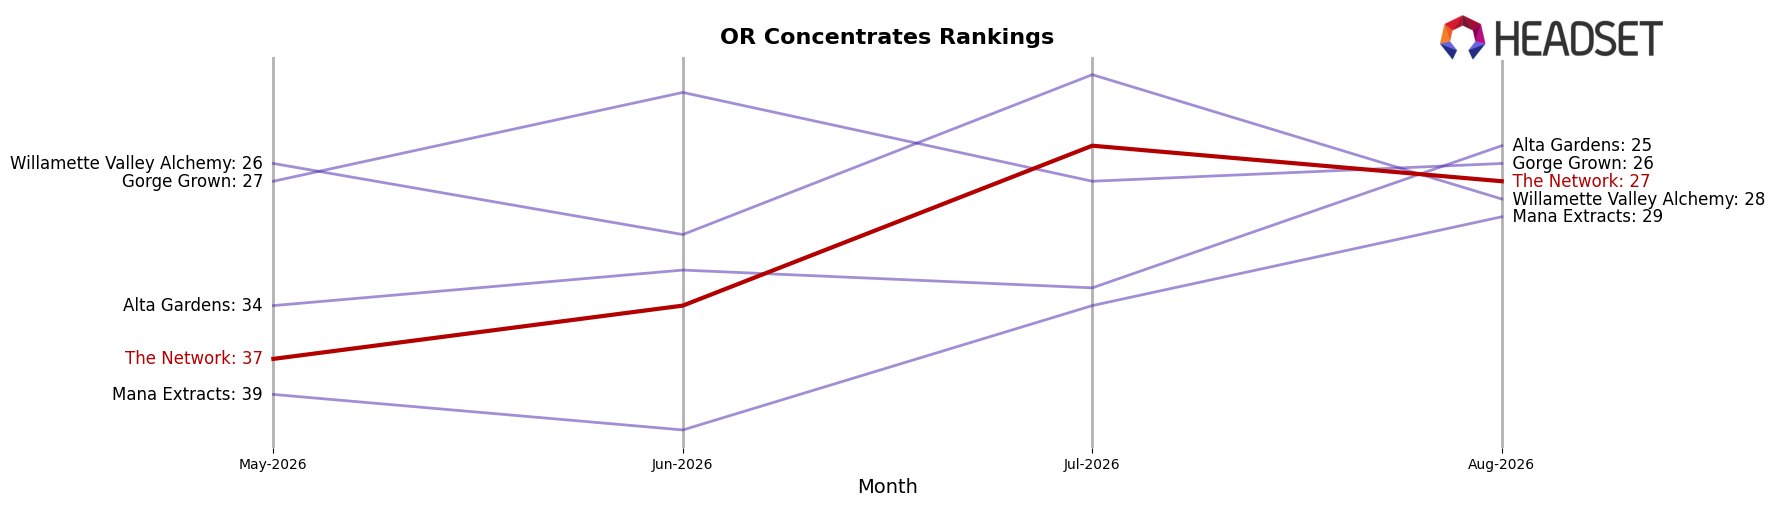
The Network sits at rank 27 in Oregon Concentrates for August 2026, improving 10 positions from rank 37 in May 2026 and sitting two spots below its peak rank of 25 reached in July 2026; year-over-year rank is unavailable, but the three-month climb of 27% of the table (from 37 to 27 within a 100-brand context) coincides with top-tier stability where Altered Alchemy held rank 1 while Oregrown advanced from rank 3 to rank 2. Compared with Red Eye Extracts (OR) sliding from rank 2 to rank 3 and posting a -22.1% year-over-year sales change, The Network’s rise from 37 to 27 over three months indicates momentum against softening incumbents, yet the gap to leaders—where White Label Extracts (OR) remains at rank 4 despite a -2.2% year-over-year result and Buddies sits at rank 5 with +8.8%—implies that sustaining mid-pack gains will require translating recent rank wins in July 2026 and August 2026 into consistent share capture against stable top-5 anchors.
Notable Products
Bling Blao Pre-Roll (1g) posted the sharpest movement in August 2026 with a -57.3% month-over-month drop while holding rank 1, and Critical Mass Pre-Roll (1g) also contracted by -41.4% at rank 7. In contrast, Gelato 45 Pre-Roll (1g) rose +24.1% at rank 2, yet three of the top ten are Pre-Roll SKUs, signaling demand concentration despite volatility. The pattern implies The Network is leaning on a narrow Pre-Roll core that is sensitive to supply or promotional swings, pointing to near-term risk in maintaining leadership via a single format.
Across concentrates, Jamaican Dream Cured Resin (2g) slid -26.8% at rank 3 and Amnesia Gold Cured Resin (2g) fell -18.8% at rank 5, with Ice Cream Cake Cured Resin (2g) down -47.3% at rank 6, while four of the top ten are Concentrates SKUs. With two categories dominating ranks 1 through 9 and one SKU at $8,382 anchoring category revenue, the skew suggests a portfolio heavy in mid-rank concentrates that are losing MoM momentum, implying a need to rebalance mix toward steadier, higher-conversion items.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

