

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change




Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeMarket Insights Snapshot
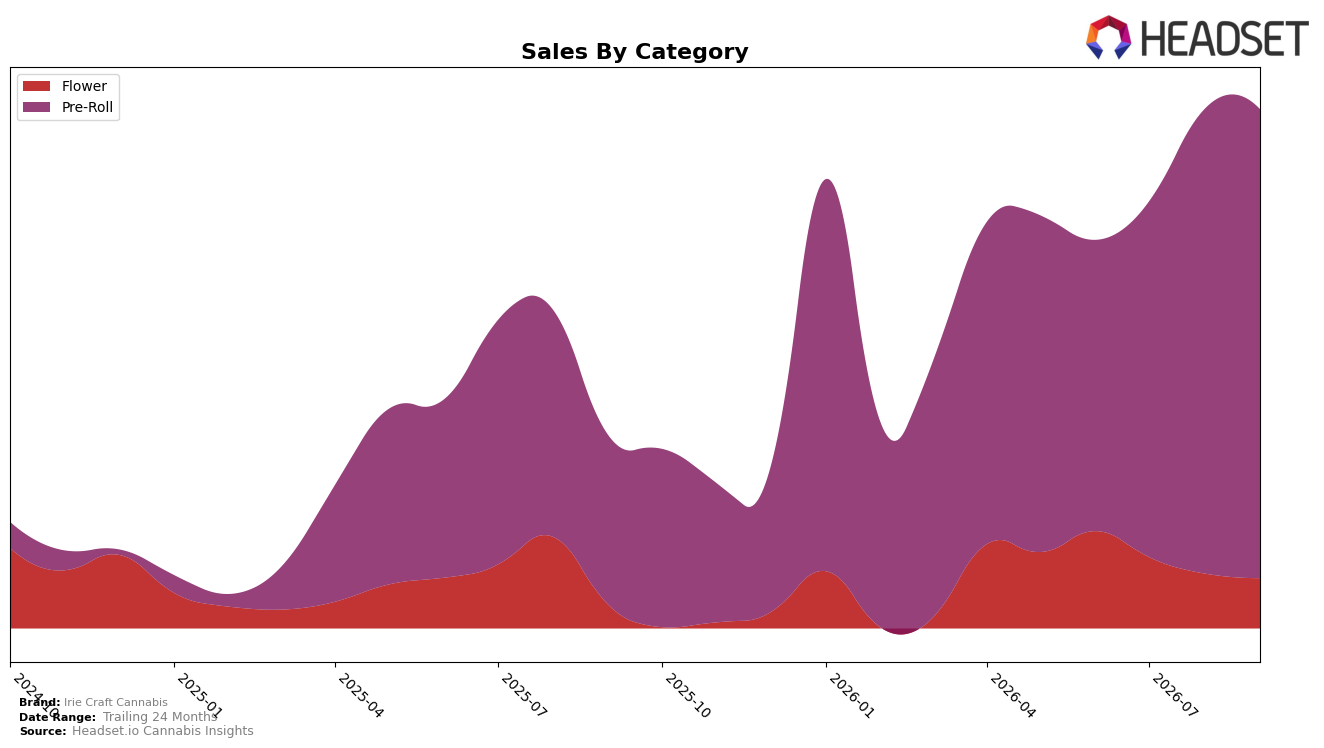
In September 2026, Irie Craft Cannabis concentrated 84.99% of sales in Pre-Roll with a 143.38% year-over-year increase and a 0.87% month-over-month uptick, while Flower held 15.00% share with 41.90% year-over-year growth but a -4.85% month-over-month decline. The brand’s average price moved down 6.06% year over year to $23.72, with Pre-Roll pricing at 22.10 and Flower at 40.51, indicating a price-led mix tilt toward lower-ticket units as volume scales. With Pre-Roll ranked 73 in Ontario and Pre-Roll share at 84.99% versus Flower at 15.00%, the balance of a rising Pre-Roll and softening Flower implies a channel where incremental gains come disproportionately from Pre-Roll velocity rather than cross-category expansion.
The divergence between a 0.87% month-over-month rise in Pre-Roll and a -4.85% month-over-month decline in Flower, alongside a 143.38% versus 41.90% year-over-year split, signals that Irie Craft Cannabis is reinforcing a value-accessible, repeatable purchase lane anchored in Pre-Roll while ceding near-term premium trade-up in Flower. Given the 73rd Pre-Roll rank in Ontario and an 84.99% Pre-Roll mix, the path forward implies brand positioning as a depth player in Pre-Roll focused on incremental unit share gains through pricing efficiency, with Flower acting as a secondary, margin-accretive niche rather than a scale driver.
Competitive Landscape
Irie Craft Cannabis sits at rank #73 in ON Pre-Roll for September 2026, up 38 positions year over year from #111, but only 15 spots better than June 2026’s #88, and still three ranks below its January 2026 peak at #70; meanwhile, Back Forty / Back 40 Cannabis moved from #2 to #1 with a 46.6% YoY sales increase while General Admission slipped from #1 to #2 on a 38.2% YoY decline, and Spinach climbed from #17 to #4 with 141.2% YoY growth, indicating that Irie Craft Cannabis’s rank recovery is occurring amid rapid share consolidation at the top and implies the current trajectory is stabilization rather than a breakout without a shift in mix or velocity.

Notable Products
Irie Pre-Roll 3-Pack (1.5g) posted the steepest decline in September 2026 at -58.7% and fell to rank 5, while RS-11 (3.5g) also dropped -56.2% at rank 9. Offsetting the slide, CYOA (7g) surged +51.5% to rank 7 and Irie Pre-Roll 10-Pack (5g) rose +16.5% to hold rank 1, whereas Irie Pre-Roll 5-Pack (2.5g) slipped -7.5% at rank 2. With seven of the top ten SKUs in Pre-Roll, the mix tilts toward multi-pack formats that are consolidating share at the top, implying a push toward higher-count value packs over smaller pack sizes.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

