

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Orchard (Canada) is stocked at 26 licensed dispensaries across Montana and Colorado, 22 of them in Montana, with the deepest coverage in Bozeman, Great Falls, Missoula, Big Sky, and Billings. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
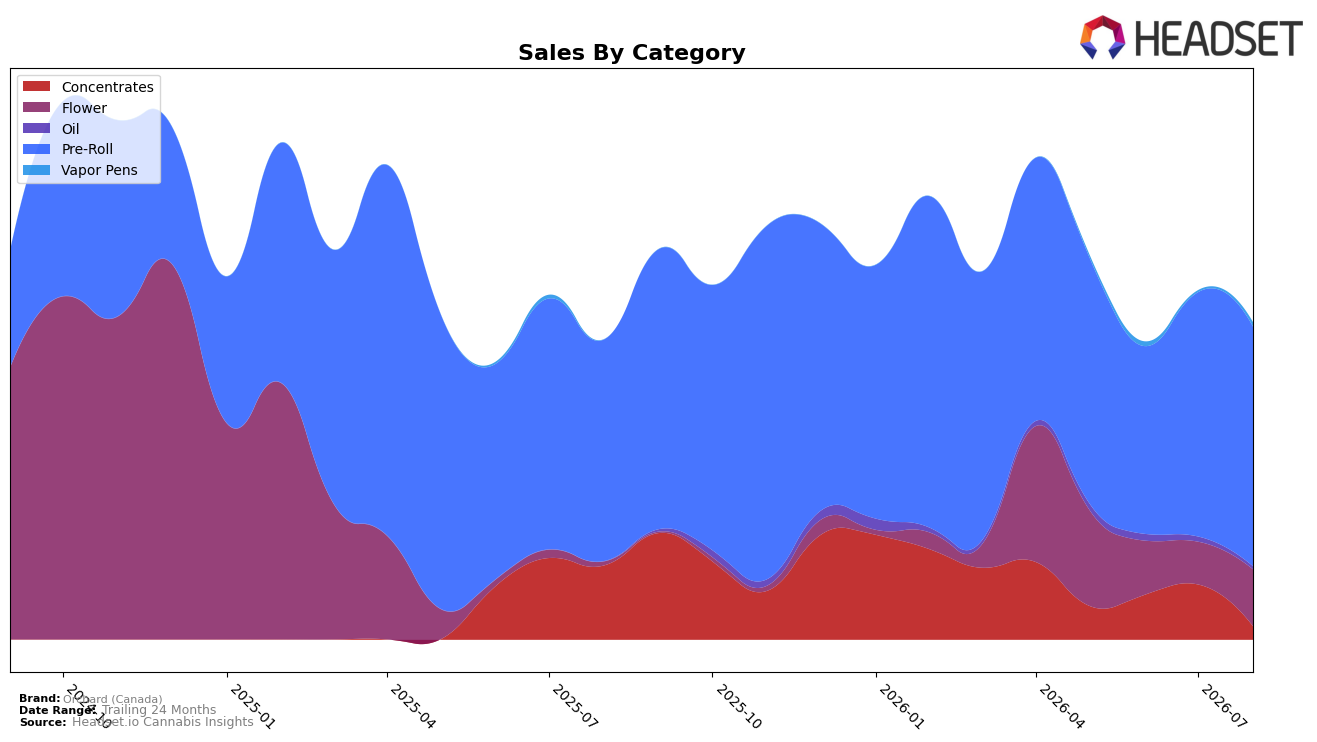
Orchard (Canada) concentrated 75.74% of August 2026 sales in Pre-Roll, where year-over-year sales rose 8.12% but month-over-month slipped 1.92%, indicating a stable anchor with slight intra-quarter softness; by contrast, Flower expanded to a 17.92% share with a 1,431.62% year-over-year surge and a 33.35% month-over-month uptick, shifting the mix toward higher-ticket formats at a $69.92 average price versus $17.43 in Pre-Roll. The steep retrenchment in Concentrates to a 4.16% share, with sales down 82.27% year-over-year and 76.14% month-over-month, alongside Vapor Pens growing 139.08% month-over-month to 1.32% share and Oil contracting 43.62% month-over-month to 0.86% share, implies Orchard (Canada) is reallocating assortment and price points toward Flower and maintaining Pre-Roll scale while exiting lower-velocity Concentrates SKUs.
These shifts position Orchard (Canada) to trade customers up without abandoning its volume engine: the brand-wide average price fell 5.83% year-over-year while total sales rose 5.65%, suggesting mix-driven unit gains, yet the elevation of Flower (+1,431.62% year-over-year; +33.35% month-over-month) creates headroom for targeted premiumization even as Pre-Roll posts only a 1.92% month-over-month dip. With a Pre-Roll rank of 86 in British Columbia and category share at 75.74%, the near-term path is to leverage Flower’s momentum to improve rank while using Vapor Pens’ 139.08% month-over-month rebound as a testbed for incremental baskets, implying a barbell between high-velocity Pre-Roll and higher-margin Flower that can offset Concentrates’ 82.27% year-over-year decline.
Competitive Landscape
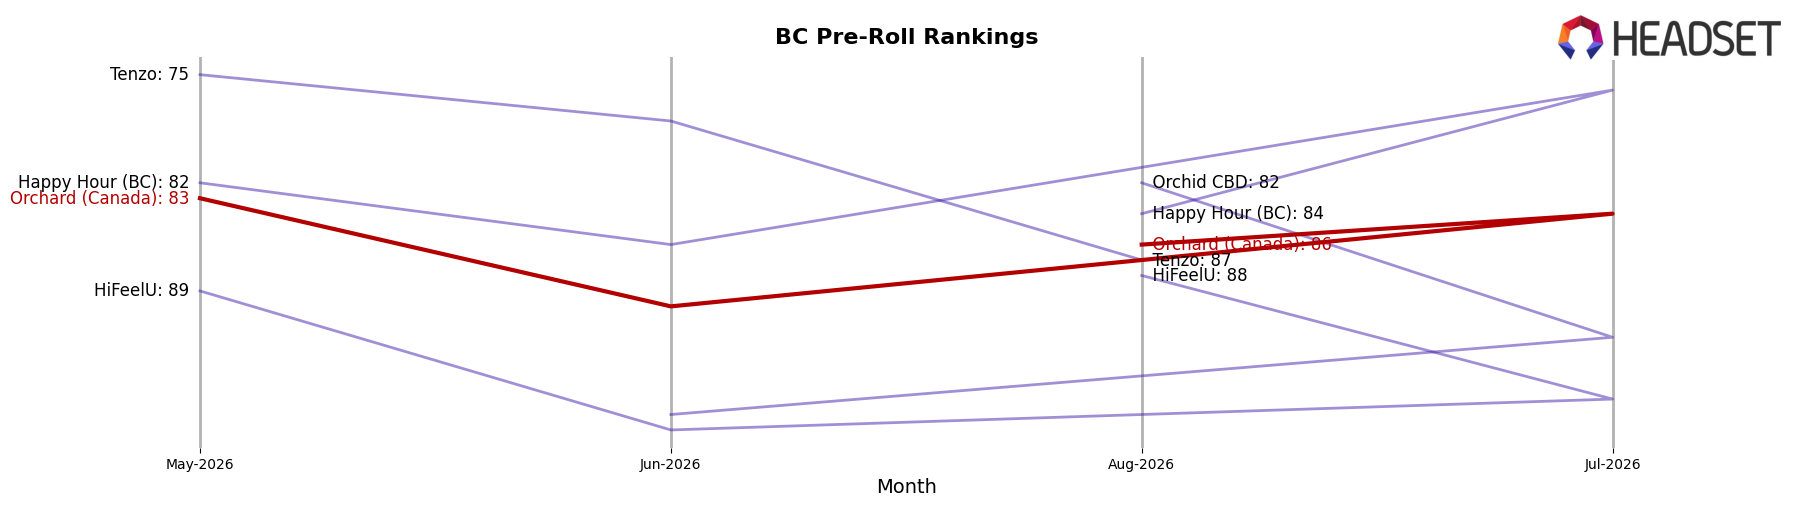
Orchard (Canada) sits at rank #86 in BC Pre-Roll for August 2026, improving 5 positions from #91 year over year but slipping 3 spots from #83 since May 2026; relative to a prior peak at #54 in October 2025, the brand is 32 ranks lower, while category leaders are moving in the opposite direction as Back Forty / Back 40 Cannabis climbed from #17 to #1 and Good Supply advanced from #7 to #5 with a 47.3% YoY sales increase. This combination of a modest YoY rank gain alongside quarter-over-quarter slippage, set against competitors accelerating upward, implies Orchard (Canada) is stabilizing but losing relative velocity, and without a shift in mix or activation cadence its position is likely to drift further from the top-50 cohort.
Notable Products
Blackberry THCv Pre-Roll 7-Pack (3.5g) delivered the standout movement in August 2026 with a 158.7% month-over-month surge to rank 2, while Fractals Full Cannabinoid Spectrum Diamond (1g) fell 76.1% to rank 4. Granddaddy Gelatti Pre-Roll 3-Pack (1.5g) held rank 1 with a -1.9% dip, and Grape Galena Pre-Roll 7-Pack (3.5g) climbed 67.5% to rank 3. With three of the top five positions occupied by Pre-Roll SKUs, the pattern implies Orchard (Canada) is concentrating velocity in multi-pack Pre-Rolls as the anchor of its lineup.
Flower showed split momentum, with Pucker Up (14g) up 139.2% at rank 3 versus Tropical Cherry (14g) down 58.7% at rank 9, while Pre-Roll Apple Flapjacks Pre-Roll 3-Pack (1.5g) slid 44.5% at rank 5. The lone Concentrates entry sat at rank 4 despite the 76.1% decline, and Vapor Pens entered at rank 7 with $1,176 in August 2026 sales. The cross-category divergence and concentration of gains in high-count Pre-Rolls imply the commercial direction is skewing toward value-oriented inhalables with selective Flower bets rather than breadth across formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

