

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
In September 2026, Flow State Cannabis (CT) concentrated 59.08% of sales in Pre-Roll while 40.92% came from Flower, a two-category split that tilts nearly 18.17 percentage points toward Pre-Roll; within this mix, average prices diverged, with Pre-Roll at $25.06 and Flower at $30.64, a 22.3% premium for Flower. With Pre-Roll as the top category and a state-category rank of 15 in Connecticut Pre-Roll, the positioning skews toward volume-led formats, and the spread between a 59.08% Pre-Roll share and a 40.92% Flower share implies merchandising and promotional levers are likely aligned to preserve rank cadence in Pre-Roll rather than expand premium Flower penetration.
The 59.08% Pre-Roll share alongside rank 15 in Connecticut Pre-Roll suggests the brand anchors traffic on accessible pack sizes and price points, while the 22.3% Flower price premium versus Pre-Roll and a 40.92% Flower share indicate headroom to trade up without eroding the core Pre-Roll base. This mix—nearly three-fifths Pre-Roll and just over two-fifths Flower—implies the near-term path is to defend Pre-Roll rank density while selectively pushing higher-margin Flower batches, using the price gap to segment buyers and to shift a targeted 2–4 percentage points of share toward Flower without sacrificing the anchor provided by Pre-Roll.
Competitive Landscape
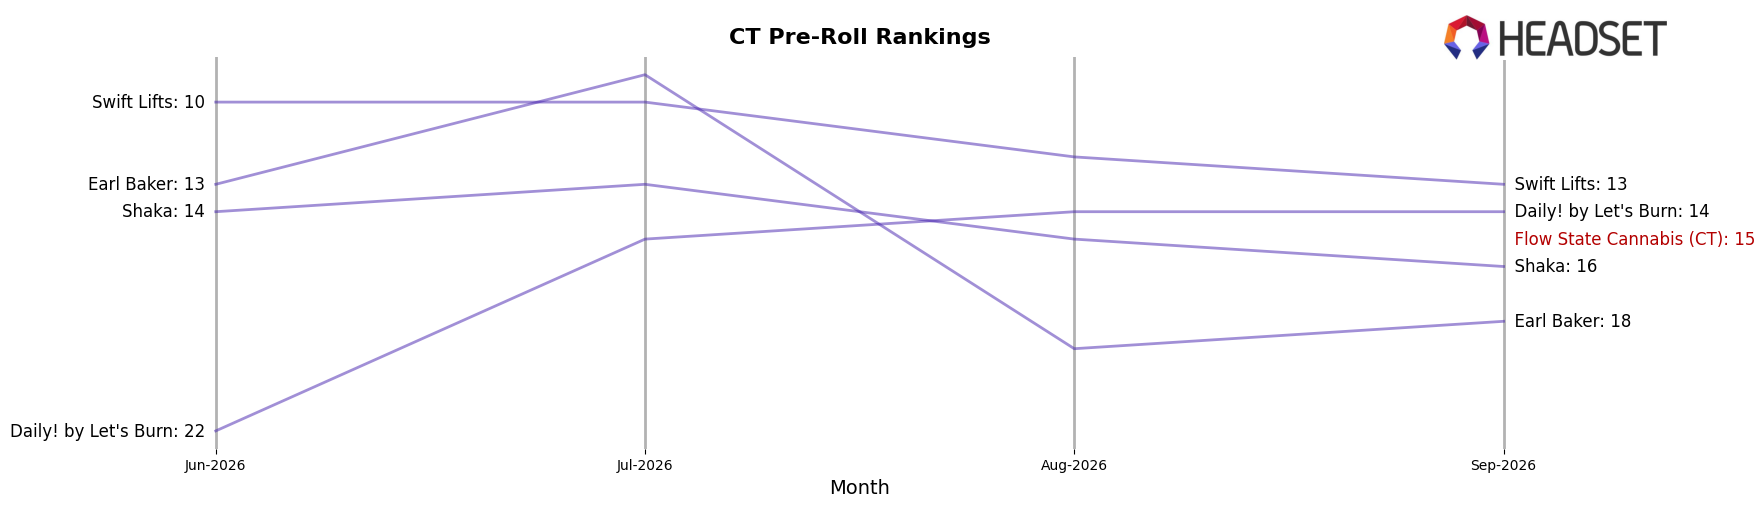
Flow State Cannabis (CT) sits at rank #15 in CT Pre-Roll in September 2026, marking its peak to date at #15 while lacking a recorded year-over-year rank comparison, which contrasts with Theraplant moving from #2 to #1 and Dogwalkers climbing from #12 to #3 alongside a 548.6% sales increase; meanwhile, Comffy improved from #8 to #2 with a 54.3% sales gain as Flow State Cannabis (CT) reached its first top-15 entry. The directional gap—competitors advancing multiple rank positions (e.g., +11 for Dogwalkers and +6 for Comffy) while Flow State Cannabis (CT) registers its initial #15 peak—implies a late-cycle entry that must convert peak visibility into share capture before entrenched leaders widen the spread.
Notable Products
Sour Haze Pre-Roll 8-Pack (4g) holds rank 1 while I-95 Ckies Pre-Roll 8-Pack (4g) is at rank 2, and Cinnamon Toast Rntz Pre-Roll 8-Pack (4g) sits at rank 3, indicating a 1–3 sweep by Pre-Roll formats that outpace Flower entries at ranks 4 and 5. Four of the top ten are Pre-Roll SKUs and four are Flower SKUs, but Pre-Rolls occupy the entire top-three tier and the next Pre-Roll appears again at rank 6, implying a tilt toward multi-pack convenience over single-eighth purchases.
Sour Haze (3.5g) is the highest-ranking Flower at rank 4 while I-95 Ckies (3.5g) follows at rank 5, with Cinnamon Toast Rntz (3.5g) and Lemon Shiv (3.5g) down at ranks 7 and 8, signaling that Flower trails Pre-Roll counterparts across the same strain families. With the top SKU generating $37,949 and all three lead positions belonging to Pre-Rolls, the mix points to prioritizing scaled Pre-Roll production and marketing over expanding standalone Flower as the near-term commercial lever.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

