

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Phyra is stocked at 29 licensed dispensaries across Connecticut, with the deepest coverage in Norwalk, Bristol, Danbury, Stamford, and West Hartford. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
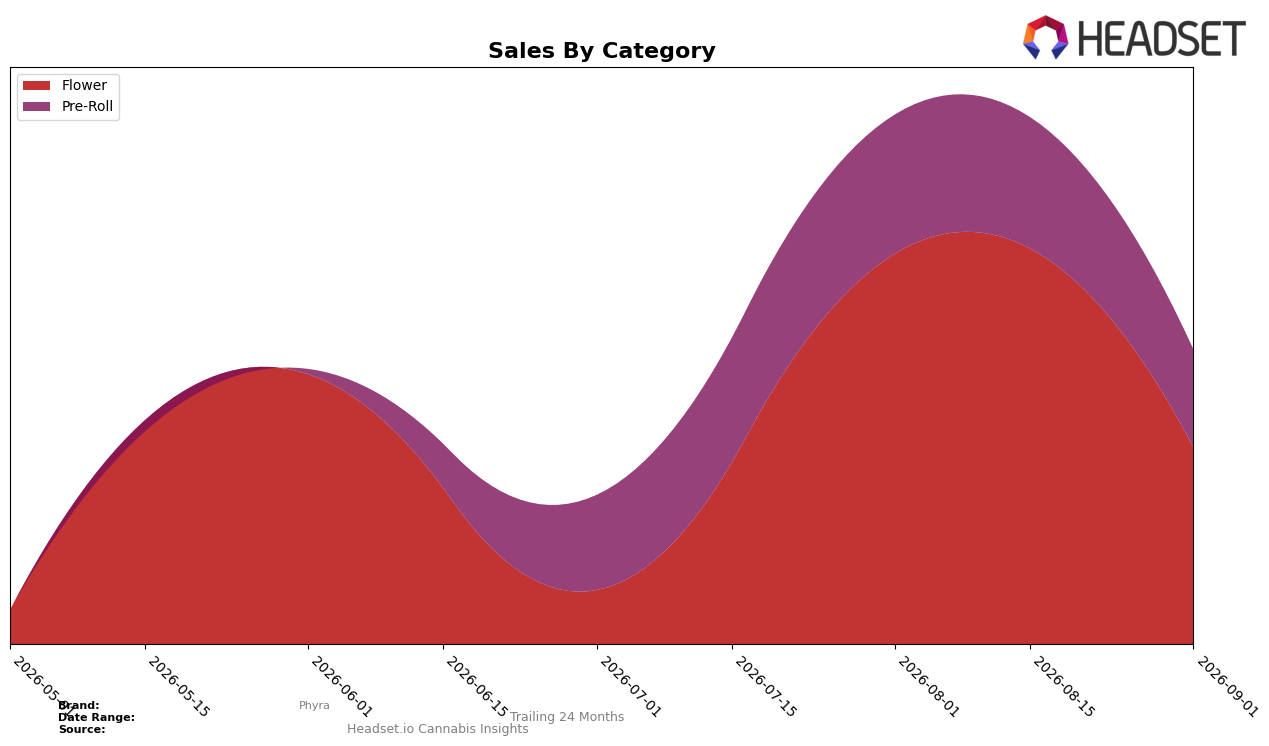
Phyra concentrated solely on Flower and Pre-Roll in September 2026, with Flower holding 66.79% share and Pre-Roll at 33.21%. Month over month, Flower declined 49.68% while Pre-Roll fell 29.65%, a gap that widened category concentration toward lower-price units as average prices diverged at 29.60 vs 9.18. With Flower ranked 20th in Connecticut and Flower’s steeper contraction versus Pre-Roll, the mix indicates a rebalancing where volume protection increasingly relies on Pre-Roll despite its smaller share, implying that September 2026 pressure pushed the brand toward a more value-leaning basket.
The 33.21% Pre-Roll share against a 49.68% Flower pullback and a milder 29.65% Pre-Roll decline suggests price-sensitive demand is cushioning overall volatility, while the 20 rank in Connecticut Flower sets a ceiling on premium-led recovery near term. With a 66.79% dependence on Flower and a near 20-point price delta between categories, September 2026 dynamics imply that stabilizing rank will require either arresting the Flower decline or accelerating Pre-Roll to 35–40% share, positioning Phyra to lean into formats with faster repeat and lower basket risk.
Competitive Landscape
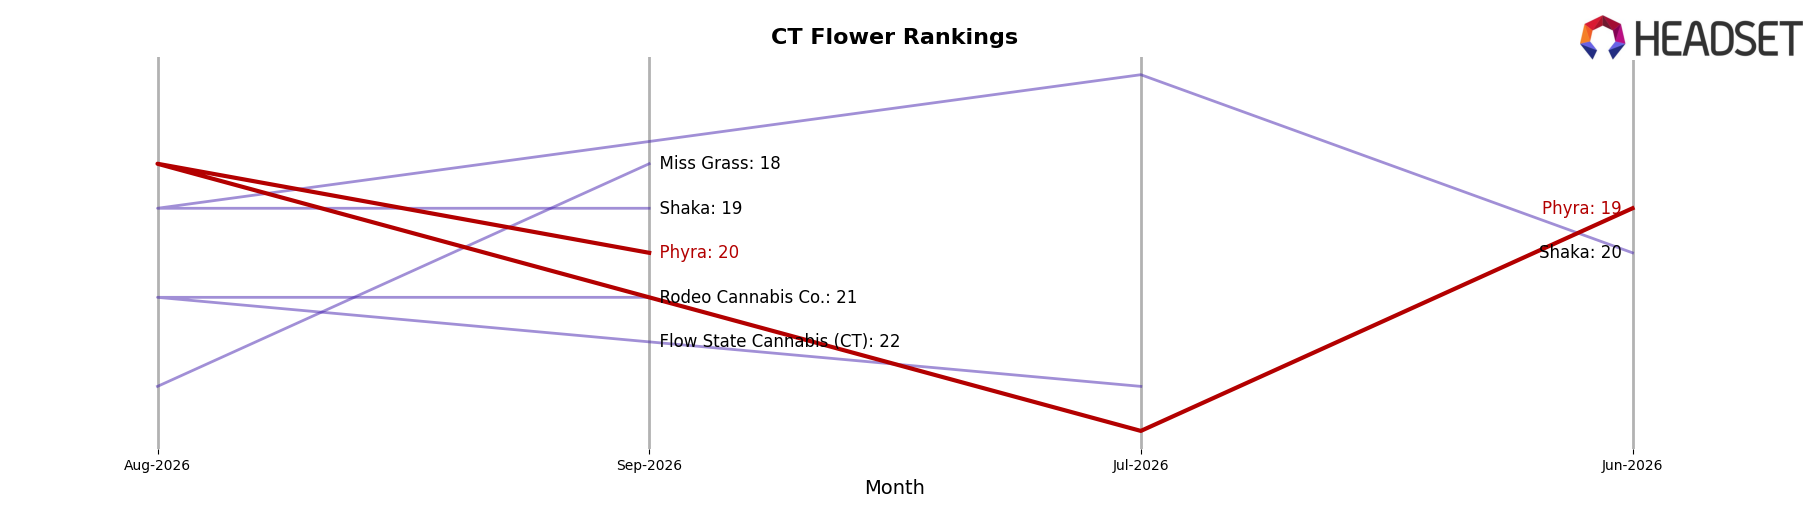
Phyra ranks #20 in CT Flower in September 2026 after sliding 1 place from #19 in June 2026, and sits 2 spots below its peak of #18 reached in August 2026; against this backdrop, Let's Burn holds #1 while Find. climbed 12 positions year over year to #3, and RYTHM advanced 8 ranks to #5, outpacing Phyra’s quarter-over-quarter dip by wider margins. With Savvy sitting at #2 despite a 26.8% YoY sales decline and Brix Cannabis (CT) at #4 after a 6-rank YoY rise but a 4.7% YoY sales contraction, the mix of upward rank mobility and negative sales deltas among leaders indicates that Phyra’s recent rank softness is more about relative share shifts than category expansion, implying that without a near-term share capture move, the brand’s late-summer peak near #18 risks reverting toward the low-20s.
Notable Products
Hella Jelly (3.5g) posted the steepest movement in September 2026 with an -80.4% month-over-month drop while holding rank 3, contrasting with Blue Lagoon Pre-Roll (1g) at rank 2 sliding -11.8% and Sky-walker 2.0 (3.5g) at rank 1 rising 31.2%. With Flower occupying 4 of the top 10 ranks and Sky-walker 2.0 (3.5g) anchoring the lineup at rank 1 despite a sharp collapse from another Flower SKU, the mix points to concentration risk within Flower even as one hero SKU offsets broader volatility. Pre-Roll positions at ranks 2, 4, 5, 6, 7, and 9 include two double-digit declines of -39.8% and -15.2%, and the cluster of new or zero-history Pre-Rolls suggests pipeline refresh rather than organic momentum; the single disclosed revenue figure of $47,626 for Sky-walker 2.0 (3.5g) indicates outsized reliance on one product. The pattern implies Phyra is leaning into a winner-take-most Flower strategy while backfilling Pre-Roll breadth, a direction that raises exposure to single-SKU swings and tempers category balance.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

