
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Growing Pains is stocked at 199 licensed dispensaries across Michigan, with the deepest coverage in New Buffalo, Detroit, Monroe, Flint, and Grand Rapids. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
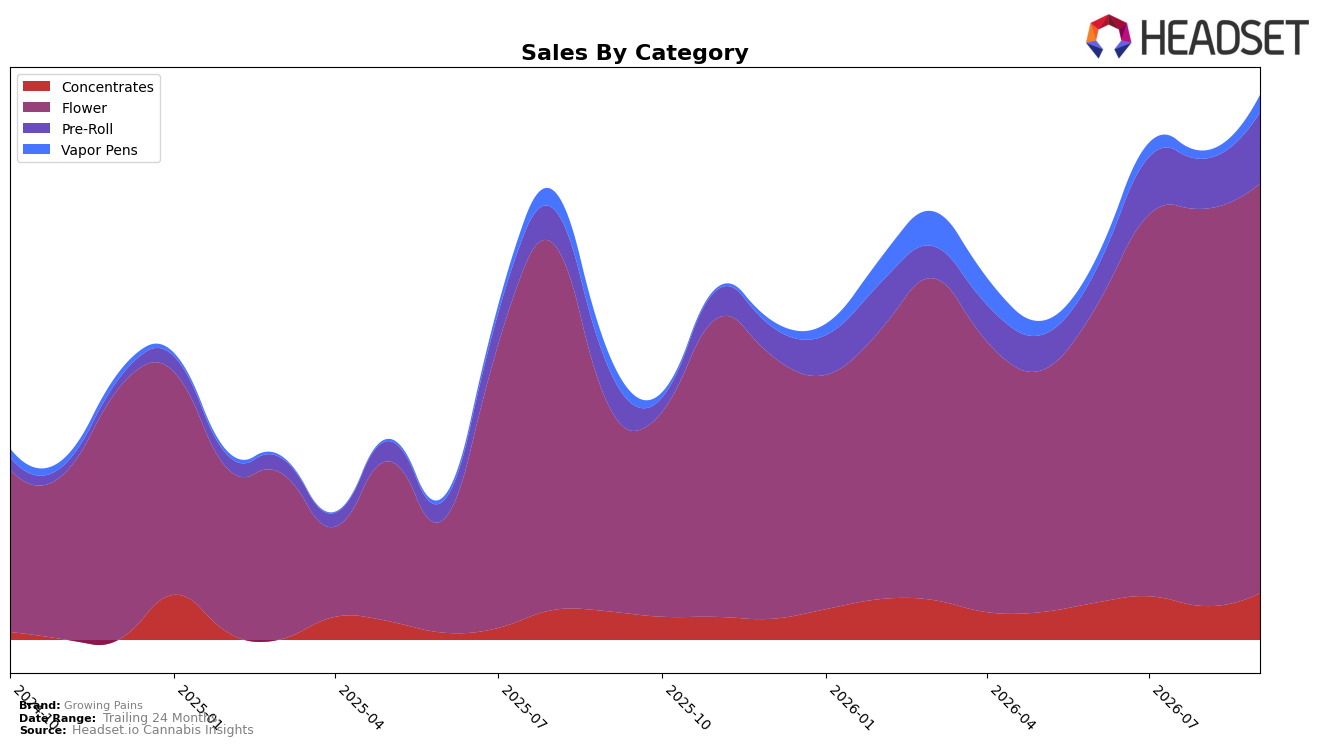
In September 2026, Growing Pains concentrated 75.27% of sales in Flower, up 3.09% month over month and 98.48% year over year, while Pre-Roll held 13.01% share with a 42.36% MoM surge and 89.79% YoY growth. Concentrates represented 8.55% share with 38.53% MoM and 64.43% YoY growth, and Vapor Pens, though just 3.17% share, spiked 119.53% MoM alongside an 18.30% YoY lift. With overall brand sales up 89.90% YoY and average price up 2.41% YoY to $13.24, the pattern implies the brand is expanding beyond its core while maintaining price discipline, using rapid MoM gains in smaller categories to complement Flower scale.
These mix shifts imply a positioning pivot: reliance on Flower volume remains, yet the 119.53% MoM rise in Vapor Pens and 42.36% MoM in Pre-Roll suggest portfolio breadth is becoming a demand lever even as Flower grew 3.09% MoM. The 64.43% YoY rise in Concentrates alongside a 98.48% YoY climb in Flower, paired with a rank of 38 in Flower in Michigan, implies the path to higher visibility leans on reinforcing Flower competitiveness while accelerating attach and trial in the faster-moving peripheral formats.
Competitive Landscape
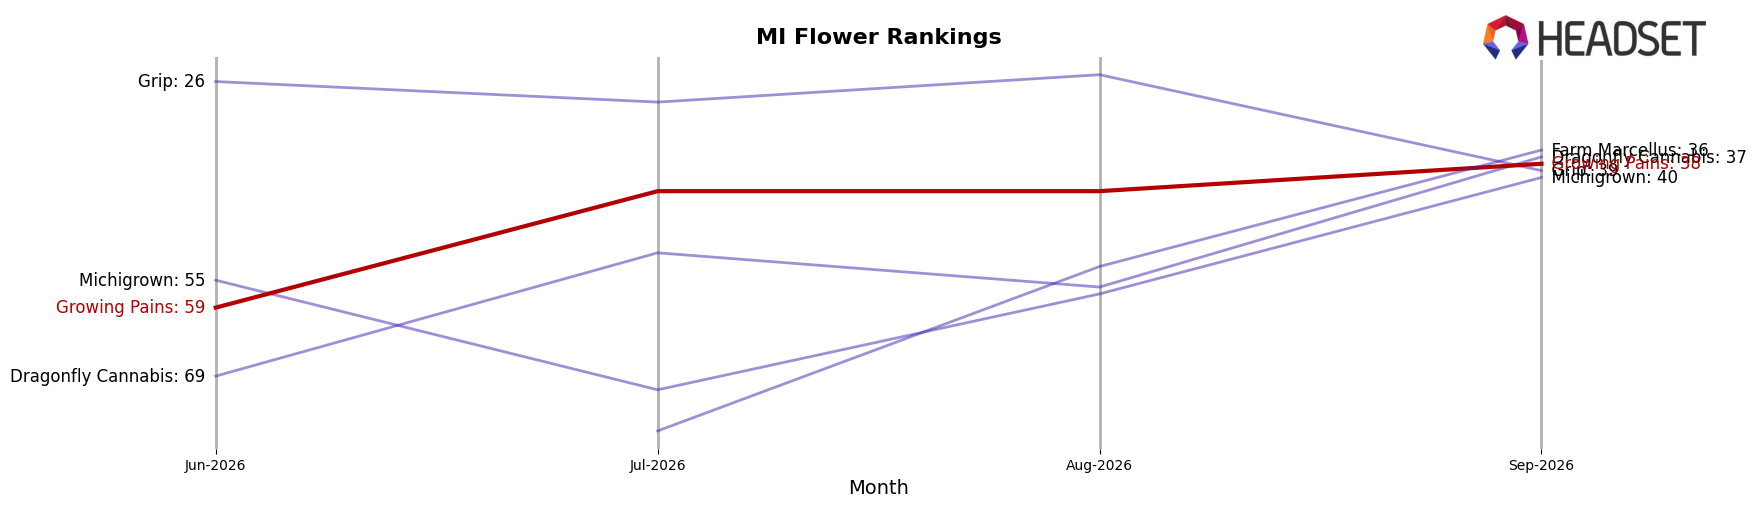
Growing Pains is ranked #38 in Michigan Flower in September 2026, improving 42 positions year over year from #80 and rising 21 spots since June 2026 from #59 to a new peak at #38 in September 2026; meanwhile, High Minded held #1 with a 0-position YoY change while its sales declined 3.3% YoY, and Play Cannabis climbed from #7 to #2 with 33.3% YoY sales growth, indicating that Growing Pains’ upward rank trajectory is catching late-stage momentum but still lags the pace of leaders concentrating share at the very top.
Notable Products
Bubblegum Gelato (Bulk) posted the steepest decline in September 2026 at -72.96% MoM while sitting at rank 9, contrasting with Burnout OG (Bulk) jumping +102.98% MoM to rank 2; the split signals volatility within Flower as Permanent Marker (Bulk) also surged +103.50% MoM at rank 4. Lantz (Bulk) held rank 1 while Candy Crush (Bulk) fell -40.18% at rank 5, and four of the top ten are Flower SKUs concentrated in Bulk formats, indicating reliance on a few fast-scaling strains despite sharp downside risk in others. The top three ranks are all Flower with Lantz (Bulk) at $107,819 and Crunch Berries (Bulk) at rank 3, implying a pivot toward high-volume Bulk Flower leadership even as underperformers get rapidly deprioritized.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

