


Where to Buy
HiRoller is stocked at 44 licensed dispensaries across Maryland and New Mexico, 43 of them in Maryland, with the deepest coverage in Baltimore, Hagerstown, Rockville, Silver Spring, and Annapolis. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
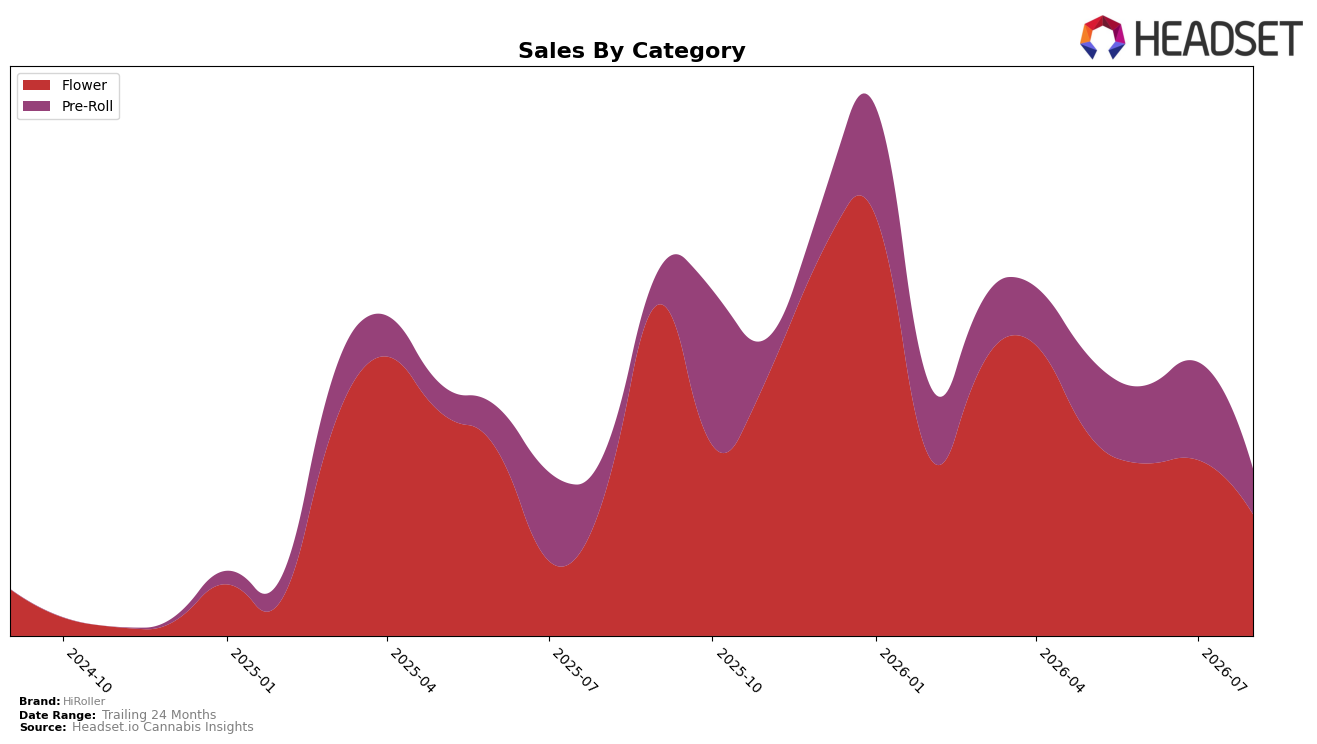
In August 2026, HiRoller concentrated 72.84% of sales in Flower and 27.16% in Pre-Roll, with Flower down 12.70% year over year and 30.99% month over month, while Pre-Roll rose 5.15% year over year but fell 53.74% month over month. Average price declined 2.87% year over year to $52.98, and within the mix Flower averaged $54.53 versus $49.23 in Pre-Roll, implying a shift away from higher-priced Flower as its share remained high yet pressured by faster month-over-month contraction. The 45th rank in Flower in Maryland paired with a 30.99% month-over-month drop signals underperformance versus category momentum at the state level, and the divergent year-over-year directions between Flower (-12.70%) and Pre-Roll (+5.15%) indicate category exposure, not pricing alone, is pulling total sales down 8.48% year over year.
The mix suggests HiRoller is over-indexed to a contracting anchor: a 72.84% Flower dependence with a 12.70% year-over-year decline and a 30.99% month-over-month slide, while the smaller 27.16% Pre-Roll segment cannot offset a 53.74% month-over-month decline despite its 5.15% year-over-year gain. With the brand positioned 45th in Maryland Flower and carrying a higher average item price in Flower ($54.53 vs. $49.23 in Pre-Roll), the pattern implies that rebalancing toward Pre-Roll or sub-lines priced closer to the $49 range could mitigate volatility, because the sharper month-over-month contractions are concentrated where HiRoller holds both the most share and the higher ticket.
Competitive Landscape
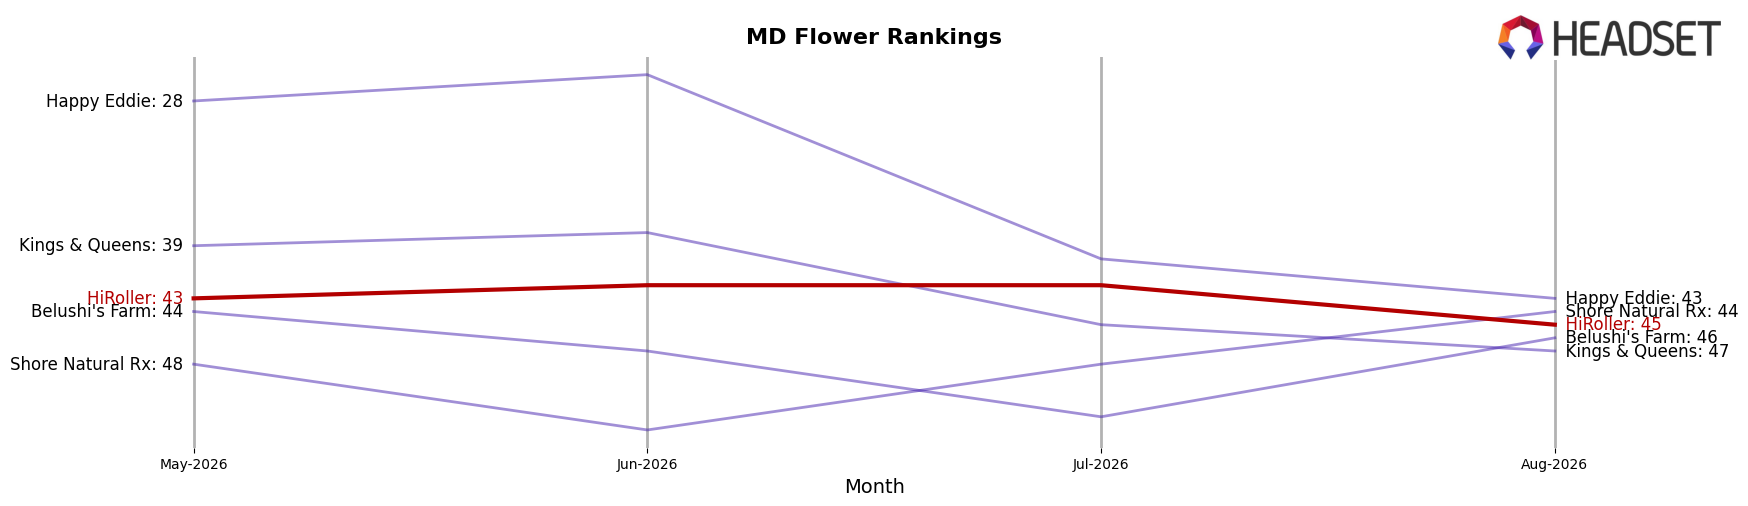
HiRoller is currently ranked #45 in MD Flower for August 2026, slipping 2 positions year over year from #43, and down 12 positions from its peak of #33 in January 2026; over the last three months the brand also softened from #43 to #45, indicating a gradual loss of footing while SunMed held at #1 year over year and Find. jumped from #29 to #5. With Fade Co. steady at #2 and RYTHM steady at #3, HiRoller’s relative decline of 2 ranks YoY and 12 ranks from peak implies that incumbents and fast risers are compressing mid-tier mobility, and absent a reversal the brand’s trajectory points to continued share erosion against faster-moving rivals.
Notable Products
Blueberry Cruffin Infused Roll Out Ready (7g) posted the steepest August 2026 slide at -83.7% MoM while dropping to rank 8, and Cherry Paloma Infused Pre-Roll (7g) fell -20.7% MoM to rank 3, implying demand rotated away from legacy pre-rolls toward fresh flower formats. Znow Flakes Infused Roll Out Ready (7g) surged +178.0% MoM to rank 1 with approximately $23,367 in sales, as McRuntz Infused Ground (7g) contracted -31.6% MoM to rank 6, a divergence pointing to consumers favoring roll-out-ready SKUs over traditional infused ground. With four of the top ten in Flower and three in Pre-Roll, the category mix skew suggests HiRoller’s momentum is concentrating in Flower-led convenience formats at higher ranks while older pre-rolls cede share, signaling a near-term pivot toward scalable Flower innovation.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

