
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
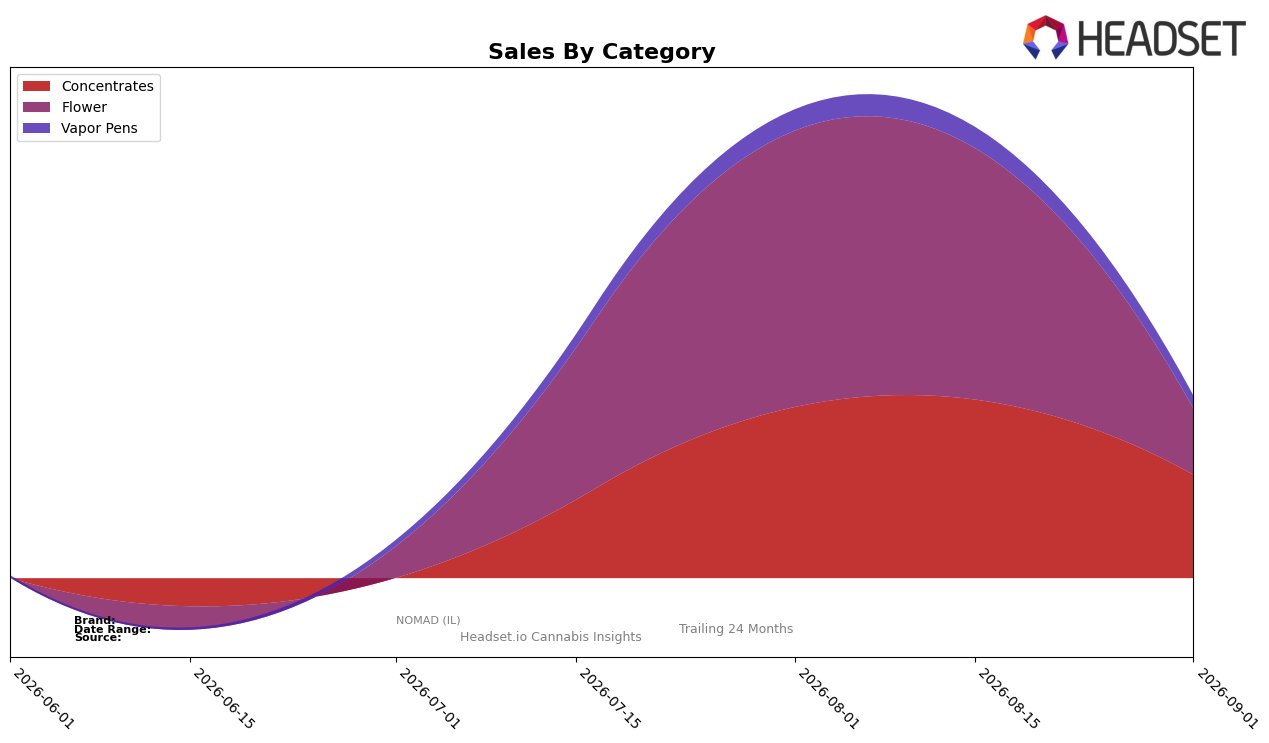
In September 2026, NOMAD (IL) concentrated 56.7% of brand sales in Concentrates while Flower represented 36.3% and Vapor Pens 7.0%, with Concentrates holding rank 30 in Illinois and Vapor Pens declining month over month by 40.0%. Concentrates fell month over month by 39.6% and Flower contracted by 76.1%, while the brand’s average price sat at $62.28 and Concentrates priced higher at an average of 72.6. The pattern indicates a tightened focus on higher-priced Concentrates despite steep month-over-month declines across all three categories, implying reliance on category depth over breadth.
Given a 56.7% sales share in Concentrates alongside a rank of 30 in Illinois and simultaneous month-over-month declines of 39.6% in Concentrates and 76.1% in Flower, the brand is positioned as a Concentrates-led player rather than a balanced portfolio. With Vapor Pens contributing 7.0% at a 40.0% month-over-month decline and Flower’s sharper contraction, the mix suggests prioritizing margin and price laddering in Concentrates (average price 72.6 versus brand average $62.28), implying that stabilization efforts should anchor on Concentrates while Flower and Vapor Pens act as secondary volume levers.
Competitive Landscape
NOMAD (IL) sits at rank #30 in Illinois Concentrates, with no year-over-year rank reported, after peaking at #26 in August 2026 and sliding four positions into September 2026; in contrast, Aeriz holds #1 with a 12.9% YoY sales increase while IC Collective advanced from #5 to #3 alongside a 90.0% YoY sales gain. The #2 spot remains with RYTHM (steady at #2 with 17.3% YoY growth), and Nature's Grace and Wellness moved from #8 to #4 with 32.8% YoY growth, indicating that while top-tier competitors are consolidating share through upward rank shifts of 1–4 places, NOMAD (IL)'s drop from #26 to #30 over one month implies a vulnerability to faster-moving rivals and a need to counter accelerating momentum at the top of the table.

Notable Products
Fugazi Funk (7g) posted the steepest decline in September 2026 at -78.3% MoM, dropping to rank 4, while Peach Daquiri #5 Live Rosin Disposable (0.5g) fell -50.9% to rank 5, signaling acute pressure on larger Flower packs and a vulnerable entry in Vapor Pens. Peach Destiny (7g) slid -42.7% to rank 2 as Lunch Money (7g) sank -73.2% to rank 9, and four of the top ten are Concentrates SKUs clustered in ranks 1, 3, 7, and 8. Rainbow Guave #5 Live Rosin Jam (1g) led at rank 1 and Rainbow Slushers Live Rosin Jam (1g) held rank 3 despite a -27.6% MoM decline, indicating relative stability in jam-format rosins compared to Flower volatility. The pattern implies NOMAD (IL) is pivoting toward Concentrates leadership while de-emphasizing bulk Flower as demand consolidates in smaller, premium extracts.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

