

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Zone is stocked at 20 licensed dispensaries across New Jersey and Pennsylvania, 19 of them in New Jersey, with the deepest coverage in Newton, Atlantic City, Bridgeton, Edgewater Park, and Elmwood Park. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
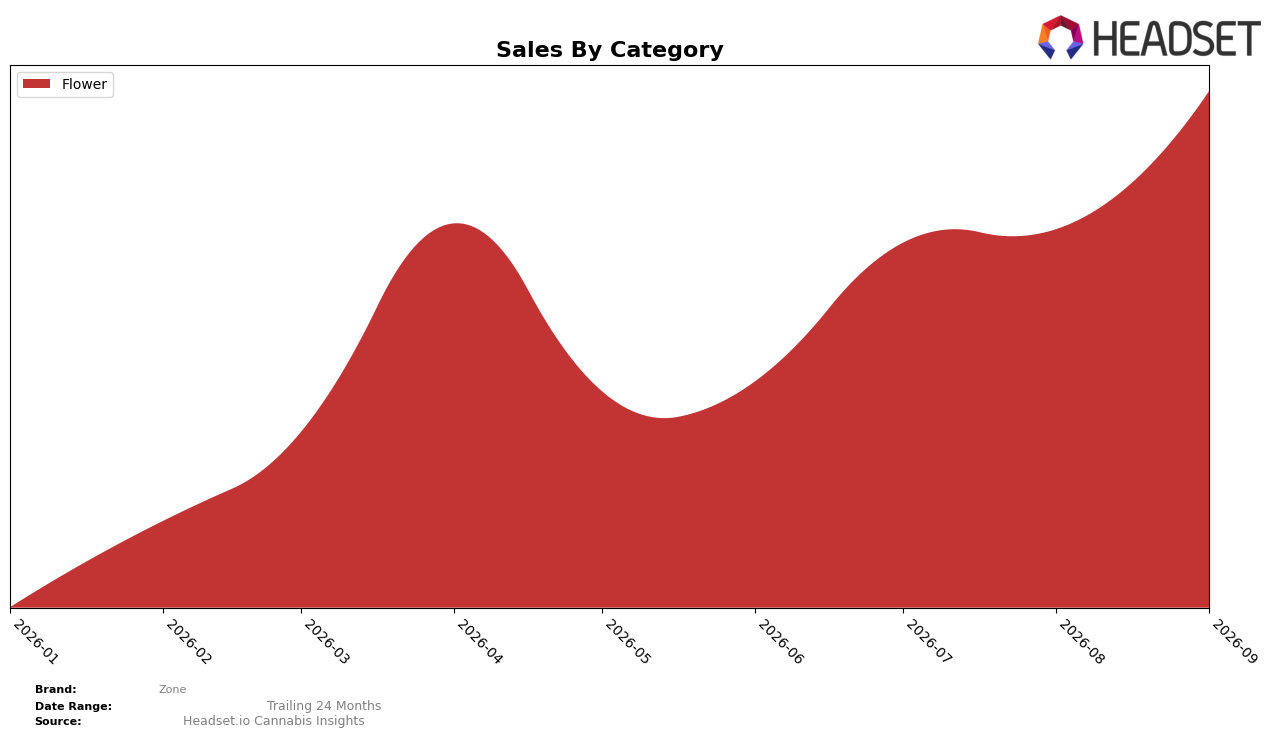
Zone operated as a single-category brand in September 2026, with Flower comprising 100.0% of sales and averaging $44.33, while month-over-month sales in Flower increased by 33.11% and category rank in Connecticut Flower stood at 11. The concentration in one category paired with a 33.11% MoM lift and a rank position of 11 implies that near-term gains are coming from depth within Flower rather than diversification, and that incremental share capture is more likely to come from improving efficiency and velocity inside Connecticut Flower than from spreading into additional categories.
With 100.0% of volume tied to Flower and a rank of 11 in Connecticut, the 33.11% MoM expansion suggests headroom within the middle tier where small share shifts can move rank positions quickly, but the lack of diversification raises exposure to category-specific volatility. This pattern implies Zone’s positioning is that of a focused Flower specialist aiming to convert recent 33.11% MoM momentum into a climb toward the top-10 in Connecticut Flower, using pricing and assortment moves to improve unit velocity rather than diluting attention across new categories.
Competitive Landscape
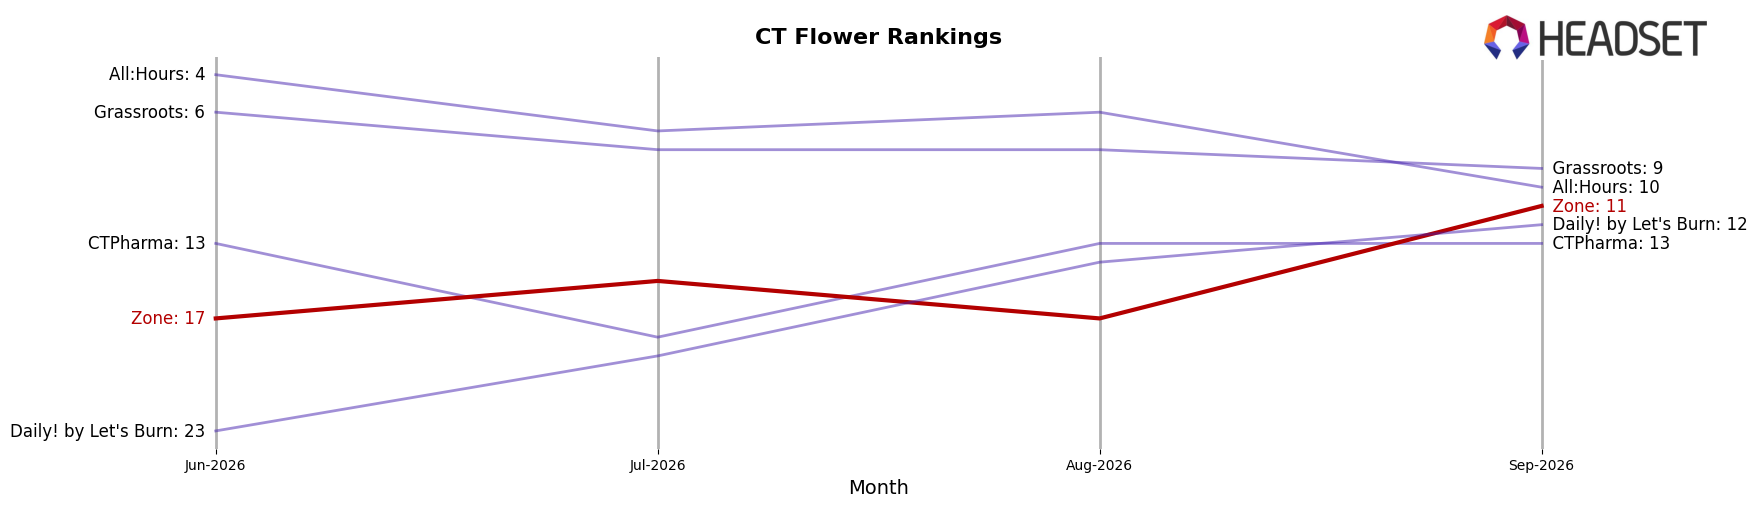
Zone is ranked #11 in CT Flower in September 2026, improving 6 positions from #17 in June 2026, and hitting a new peak rank of #11 while the year-over-year rank change is unavailable; in contrast, Savvy moved to #2 with a +2 YoY rank change despite a -26.8% YoY sales decline, and Find. climbed to #3 with a +12 YoY rank jump alongside +124.1% YoY sales growth, indicating Zone’s short-term rank momentum is improving against mixed competitor trajectories and implies a path to the top 10 if the 6-rank, three-month ascent persists.
Notable Products
Don Mega (7g) posted the standout month in September 2026 with a +35.4% MoM lift while rising to rank 3, and TGK (14g) trailed with a +34.9% MoM increase but remained outside the top three at rank 5. In contrast, Governmint Oasis (7g) slipped by -0.7% MoM at rank 9, and Sub Zero (7g) gained only +4.6% MoM at rank 7 despite Sub Zero (14g) holding rank 2, indicating mixed traction within the same family. Four of the top ten are Flower SKUs in 7g formats, and the top two ranks are occupied by larger formats (14g) including Sub Zero (14g) at rank 2 with $49,556 in sales, implying a tilt toward value-oriented pack sizes alongside selective 7g momentum. The product mix suggests Zone is consolidating around Flower with heavier reliance on 14g value packs to anchor share while using a few 7g SKUs to generate incremental velocity.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

