

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Status is stocked at 33 licensed dispensaries across California, with the deepest coverage in Los Angeles, Sacramento, Fresno, Marysville, and Aptos. Search by ZIP code or city below to find the closest one.
Market Insights Snapshot
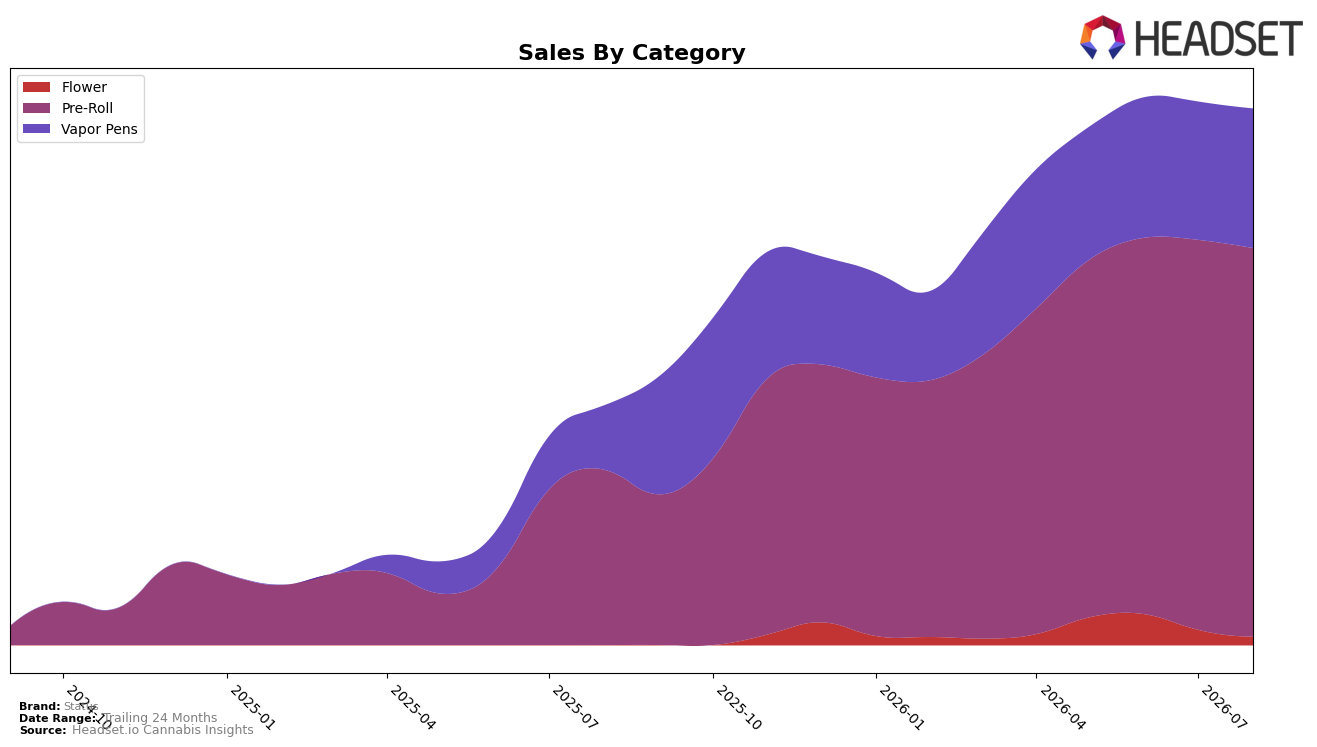
Pre-Roll held 72.41% share in August 2026 with year-over-year sales up 121.85% and month-over-month down 0.39%, while Vapor Pens accounted for 25.99% share with 117.15% YoY growth and 0.96% MoM growth. Flower was 1.59% share with a steep 43.94% MoM decline and no YoY baseline, and the brand-wide average price rose 6.75% YoY to $24.29. The mix concentrates further in value-forward inhalables, with Pre-Roll scale counterbalanced by incremental Vapor Pens momentum, implying Status is optimizing depth in Pre-Roll while selectively expanding a higher-price Vapor Pens wedge to stabilize monthly volatility.
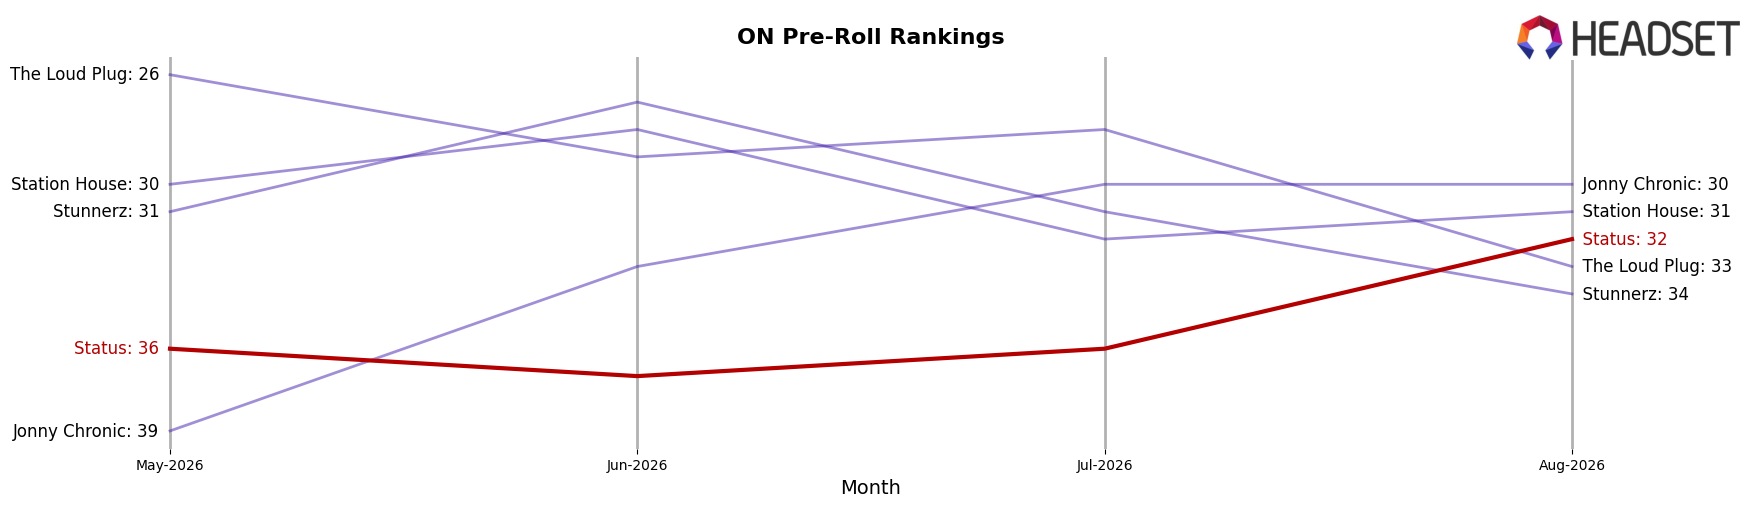
Status ranked 32 in Pre-Roll in Ontario, and Pre-Roll’s 72.41% mix paired with a 0.39% MoM dip versus Vapor Pens’ 0.96% MoM gain signals reliance on a category where small monthly pullbacks can move total sales, while a 117.15% YoY in Vapor Pens can diversify risk. The 121.85% YoY in Pre-Roll alongside a 6.75% YoY price increase indicates price tolerance within the lead category, but the 43.94% MoM contraction in Flower and its 1.59% share suggests limited traction for value-entry formats; together, this pattern implies Status’s positioning skews toward scaled Pre-Roll penetration with a premium-leaning Vapor Pens adjunct, rather than a three-category portfolio.
Competitive Landscape
Status is currently ranked #32 in ON Pre-Roll in August 2026, improving 42 positions from #74 year over year and rising 4 spots from #36 since May 2026; the current #32 also marks a peak rank matched in August 2026. Competitively, Back Forty / Back 40 Cannabis advanced from #2 to #1 while General Admission slipped from #1 to #2, and Spinach climbed from #14 to #5, indicating leaders are tightening the top tier even as mid-pack mobility increases. Against that backdrop, Status’s 42-rank YoY climb alongside a 4-rank improvement over the latest three months implies a late-entry surge into the crowded middle that, if sustained, positions it to challenge the low-20s cohort rather than oscillate in the 30s.
Notable Products
Mix Pack Liquid Diamond Kief Infused Blunt 5-Pack (2.5g) posted the standout move with an 81.9% month-over-month increase, jumping into rank 3 while the Lamborkiwi Liquid Diamond Infused Blunt (1g) fell 20.8% to rank 4. Bubble Bubble Infused Pre-Roll 5-Pack (1.25g) held rank 1 with a 10.3% MoM lift as the Bubble Bubble Liquid Diamonds Disposable (1g) slipped 1.0% at rank 2. With seven of the top ten in Pre-Roll and multiple single‑gram infused blunts dropping between 12.3% and 20.8% while multi-pack pre-rolls rose 10.3% to 81.9%, the mix points to Status consolidating demand around higher-count, value-forward Pre-Rolls rather than single sticks.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

