

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Zips! OG is stocked at 70 licensed dispensaries across New York, with the deepest coverage in New York, Staten Island, Queens, Brooklyn, and The Bronx. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
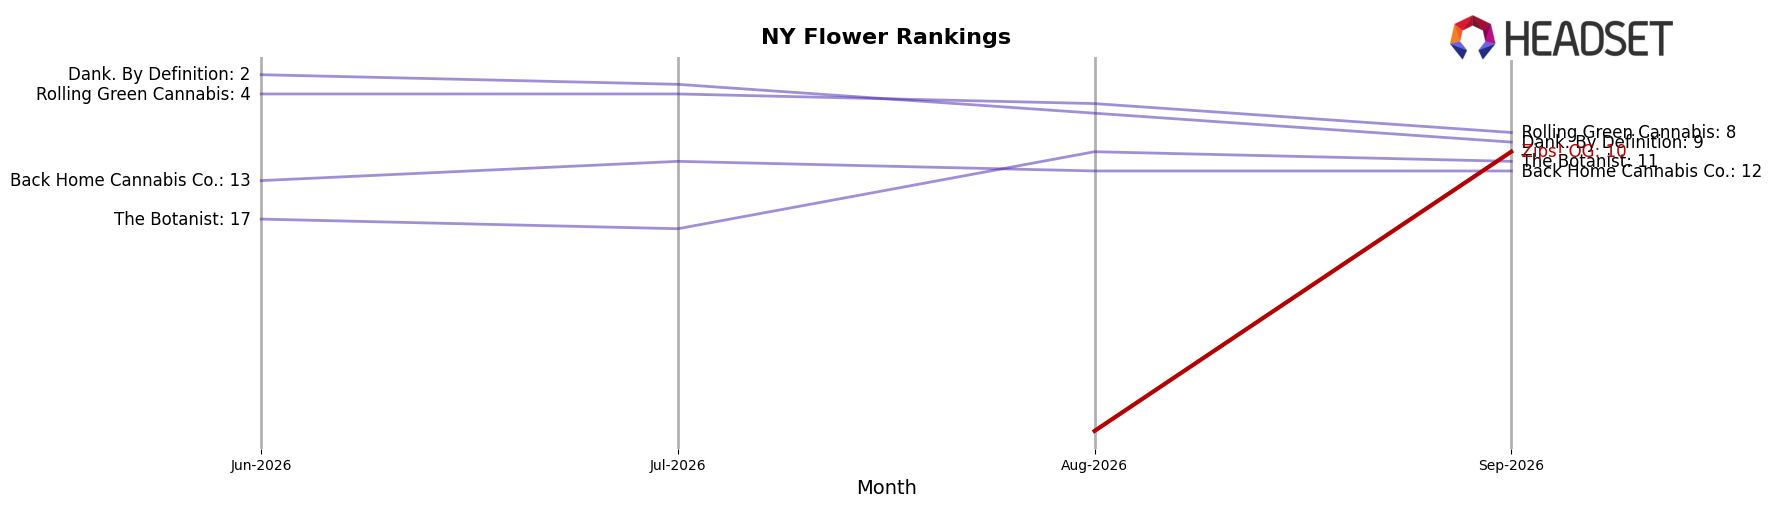
In September 2026, Zips! OG concentrated 76.29% of sales in Flower with a 295.75% month-over-month surge, while Vapor Pens held 12.38% share on a sharper 513.06% month-over-month jump and Pre-Roll captured 11.34% on a 238.36% month-over-month rise. The average price across the brand was $49.95, versus category-level averages of $72.86 in Flower and $52.80 in Vapor Pens, indicating a price ladder that sits below the dominant segment while the brand ranked 10 in Flower within New York. The pattern implies that September 2026 growth was driven by rapid re-entry or distribution expansion across all three categories, with outsized velocity in Vapor Pens repositioning mix risk away from a single-category dependence.
The combination of a 76.29% Flower share alongside a 12.38% Vapor Pens share and 11.34% Pre-Roll share, paired with month-over-month growth of 295.75%, 513.06%, and 238.36% respectively, suggests that Zips! OG is tilting from a Flower-led footprint toward a multi-format portfolio that can convert at lower price points ($49.95 brand average vs. $72.86 in Flower). Holding rank 10 in Flower in New York while Vapor Pens scales faster than the core indicates an opportunity to trade shoppers across form factors, implying positioning as a value-anchored gateway into the brand that can support incremental penetration without eroding the flagship Flower rank.
Competitive Landscape
Zips! OG sits at rank #10 in New York Flower in September 2026, with year-over-year rank movement unavailable, while the category’s leaders moved materially: Find. climbed from #5 to #1 and Grassroots jumped from #15 to #2 as its sales grew 150.33% year over year; meanwhile, RYTHM rose from #8 to #5 on 20.30% YoY sales growth, and Leal advanced from #6 to #4 despite only 4.86% YoY sales growth. With Zips! OG peaking at #10 in September 2026 while rivals moved up 4–13 rank positions, the pattern implies Zips! OG’s gains are constrained to a late-entry peak rather than a sustained climb, signaling a need to convert presence into share against brands accelerating up the table.
Notable Products
Maui Wowie (3.5g) posted the largest month-over-month surge at 263.3% to rank 8, while Girl Scout Cookies (3.5g) jumped 239.3% to rank 3, indicating demand is coalescing around revived Flower strains rather than incremental Pre-Roll gains. Mimosa (3.5g) rose 185.4% to rank 1 and Green Crack (14g) held rank 10 with a larger pack size anchoring dollar mix at $85,959, while four of the top ten are Pre-Roll SKUs concentrated between ranks 2 and 7 with growth ranging from 64.8% to 213.0%. The pattern implies Zips! OG is tilting toward Flower-led velocity spikes complemented by a Pre-Roll bench that drives breadth but not the top rank, suggesting assortment should prioritize high-momentum Flower refreshes with selective Pre-Roll support.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

