

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Market Insights Snapshot
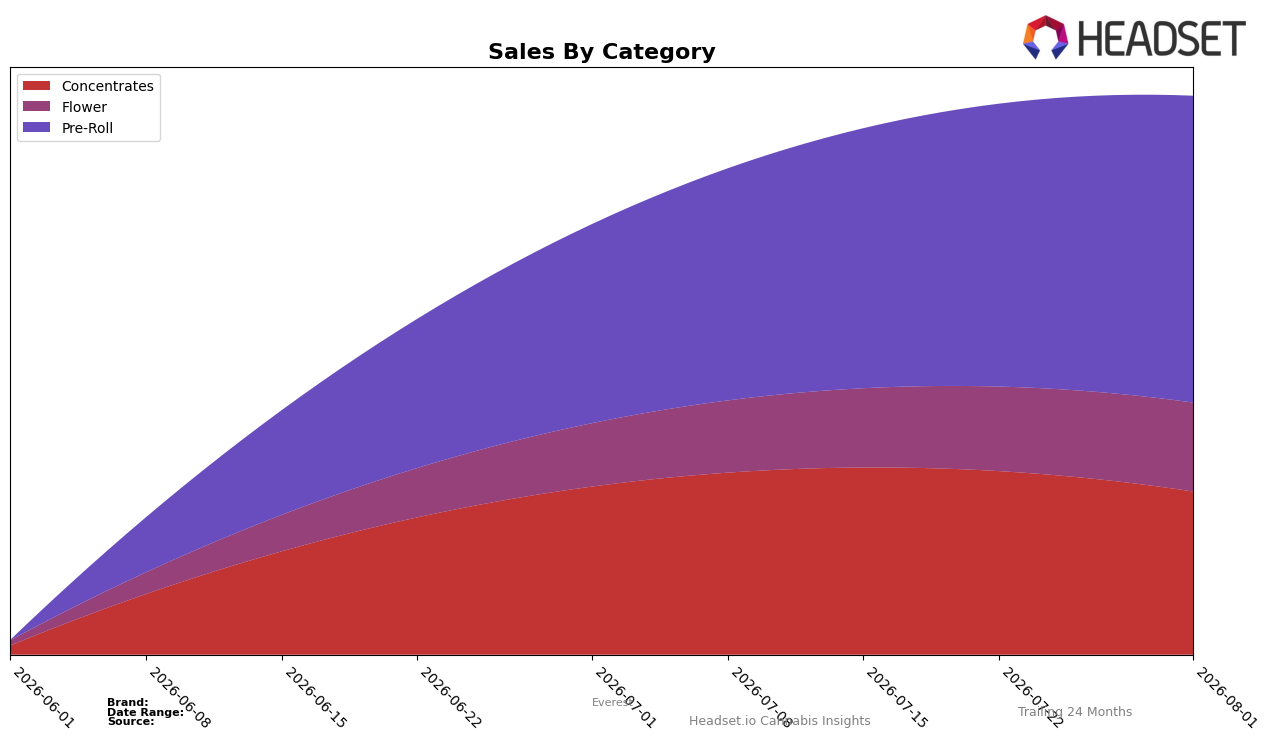
Everest’s category mix in August 2026 tilted toward Pre-Roll at 54.77% share and rank 83 in Alberta Pre-Roll, while Concentrates held 29.22% and Flower 16.01%. Month over month, Pre-Roll expanded 53.84% and Flower rose 39.65%, whereas Concentrates declined 2.89%; average prices spanned $20.37 in Pre-Roll and $73.91 in Flower. The pattern implies a rotation into lower-priced volume via Pre-Roll and a recovery in Flower, with Concentrates losing mix, setting Everest up for scale-led units over premium basket depth.
The mix shift toward a 54.77% Pre-Roll share alongside a 39.65% Flower lift suggests Everest is consolidating demand in faster-turn formats while easing reliance on the 29.22% Concentrates tier. With rank 83 in Alberta Pre-Roll and a 53.84% MoM surge in that category, the brand’s near-term positioning favors traffic capture and trial over high-ticket upsell. The implication is that Everest can leverage Pre-Roll momentum to seed cross-sell into Flower while insulating against volatility in Concentrates, using price gaps ($20.37 vs. $73.91) to ladder shoppers across tiers without eroding unit velocity.
Competitive Landscape
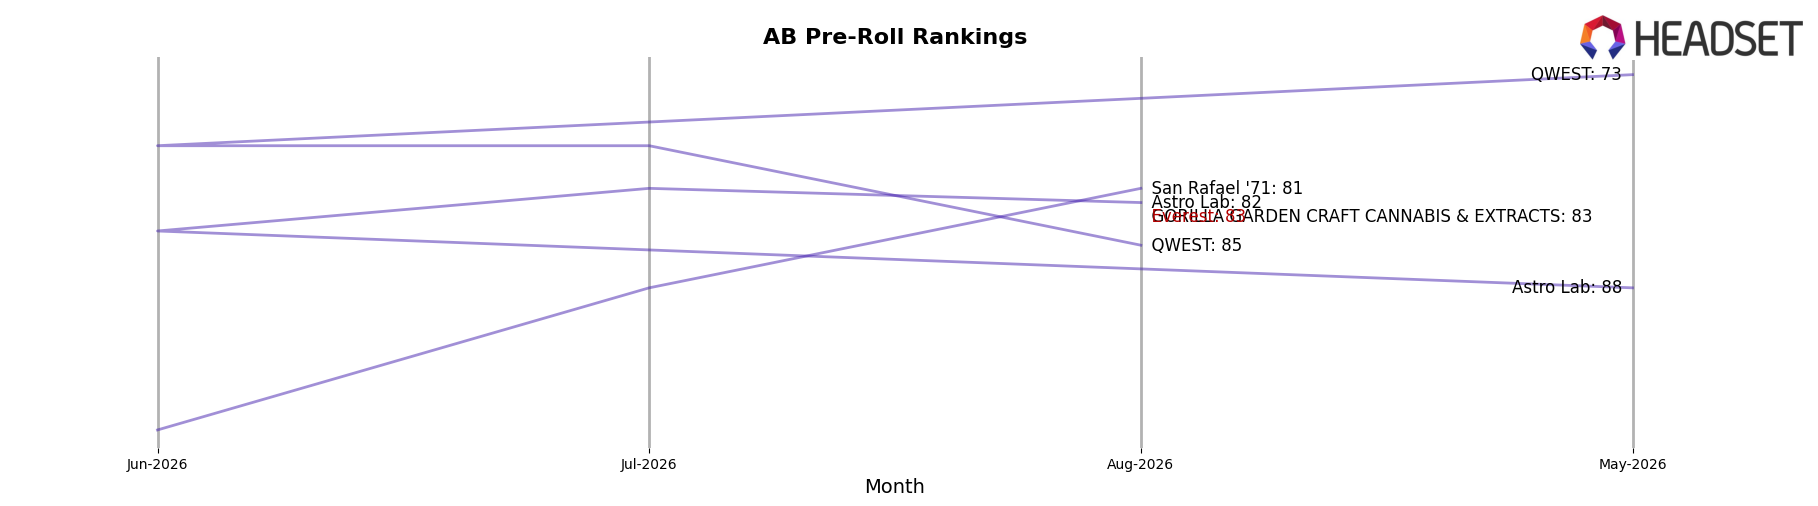
Everest sits at rank #83 in AB Pre-Roll in August 2026, with a year-over-year rank change unavailable, while the category leader landscape shifted as Back Forty / Back 40 Cannabis climbed from #5 to #1 and General Admission slipped from #1 to #2 alongside a -20.8% YoY sales change; further, Space Race Cannabis moved from #2 to #3 with -25.2% YoY sales, while Thumbs Up Brand jumped from #18 to #4 on 135.1% YoY growth, indicating a reorder of top positions that leaves Everest debuting at its peak rank of #83 in August 2026 and implying that, without rapid share capture, Everest’s late entry is more likely to be boxed into lower-tier placement than to ascend meaningfully in the near term.
Notable Products
Iced Peach Pre-Roll 10-Pack (5g) posted the standout move in August 2026 with a 167.6% month-over-month jump and a rank of 5, while Zeclair Live Hash Rosin (1g) slid 32.1% to rank 6. Ego Checker Live Hash Rosin (1g) climbed 74.9% to rank 4, outpacing Grape Gas Pre-Roll 3-Pack (1.5g) at rank 1 with 45.8% growth and $27,477 in sales. Four of the top ten are Pre-Roll SKUs, and Grape Gas (14g) in Flower advanced 59.9% to rank 9, indicating that momentum is coalescing around value-forward multi-pack Pre-Rolls with a halo effect boosting select Grape Gas formats.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

