

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Flawless is stocked at 82 licensed dispensaries across Washington, California, and 2 other states, 40 of them in Washington, with the deepest coverage in Seattle, Tacoma, Bellevue, Everett, and Auburn. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
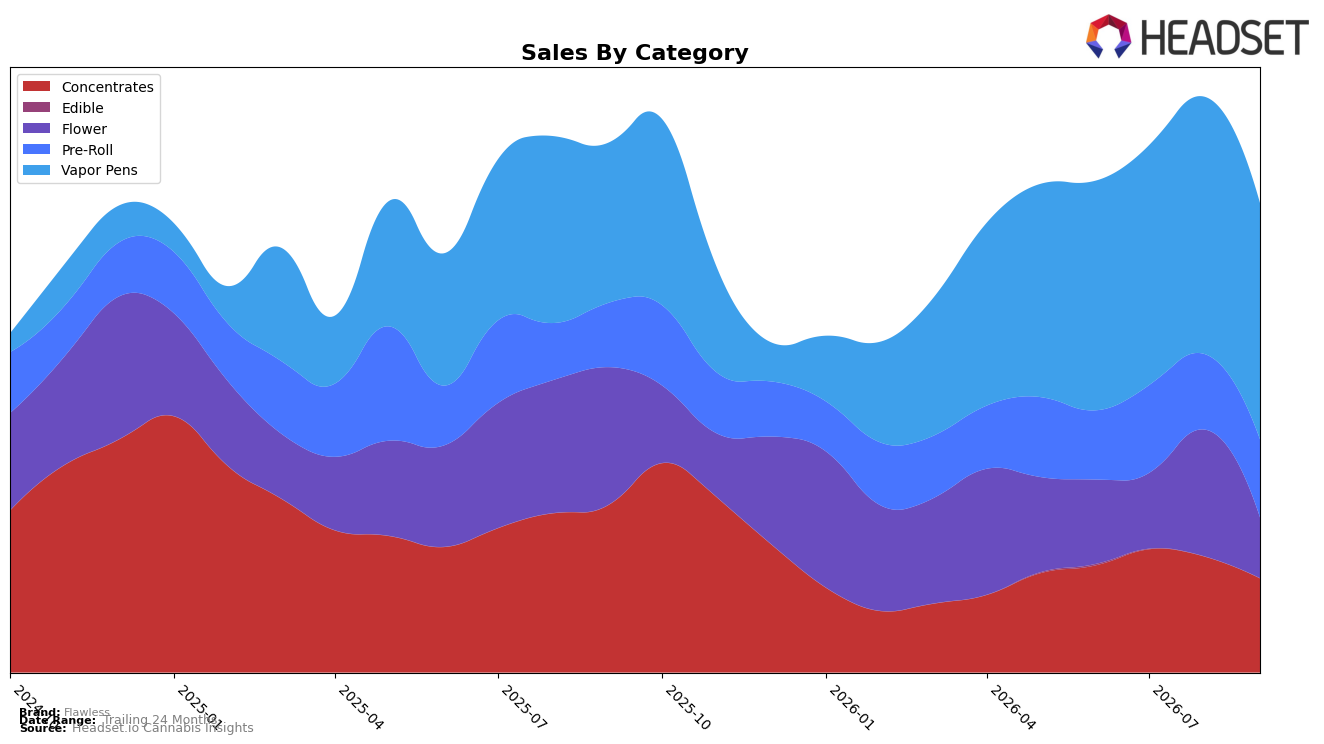
In September 2026, Flawless concentrated over half of sales in Vapor Pens at 50.40% share, with that category up 47.57% year over year despite an 8.18% month-over-month dip, while Pre-Roll rose 21.64% YoY and 3.43% MoM to 16.62% share. Offsetting those gains, Concentrates fell 43.80% YoY and 18.83% MoM to 20.05% share, and Flower contracted 56.00% YoY and 52.17% MoM to 12.92% share; combined with an average price decline of 12.42% YoY to $14.13 and a brand-level sales change of -11.41% YoY, the pattern implies a deliberate pivot toward higher-velocity inhalables while exiting or deprioritizing low-yield Flower.
With Vapor Pens leading but ranked 60 in Washington, the 47.57% YoY growth there alongside a MoM pullback of 8.18% suggests share capture is occurring through price-accessible positioning rather than rank-driven dominance, while Pre-Roll’s 3.43% MoM uptick partially buffers volatility from Concentrates’ 18.83% MoM slide. The simultaneous 25.75% 24‑month brand growth and the September 2026 category mix—67.02% of sales in Vapor Pens plus Pre-Roll—imply Flawless is migrating toward an inhalables core where frequency supports volume, accepting rank middle-tier status in Vapor Pens to trade margin for throughput.
Competitive Landscape
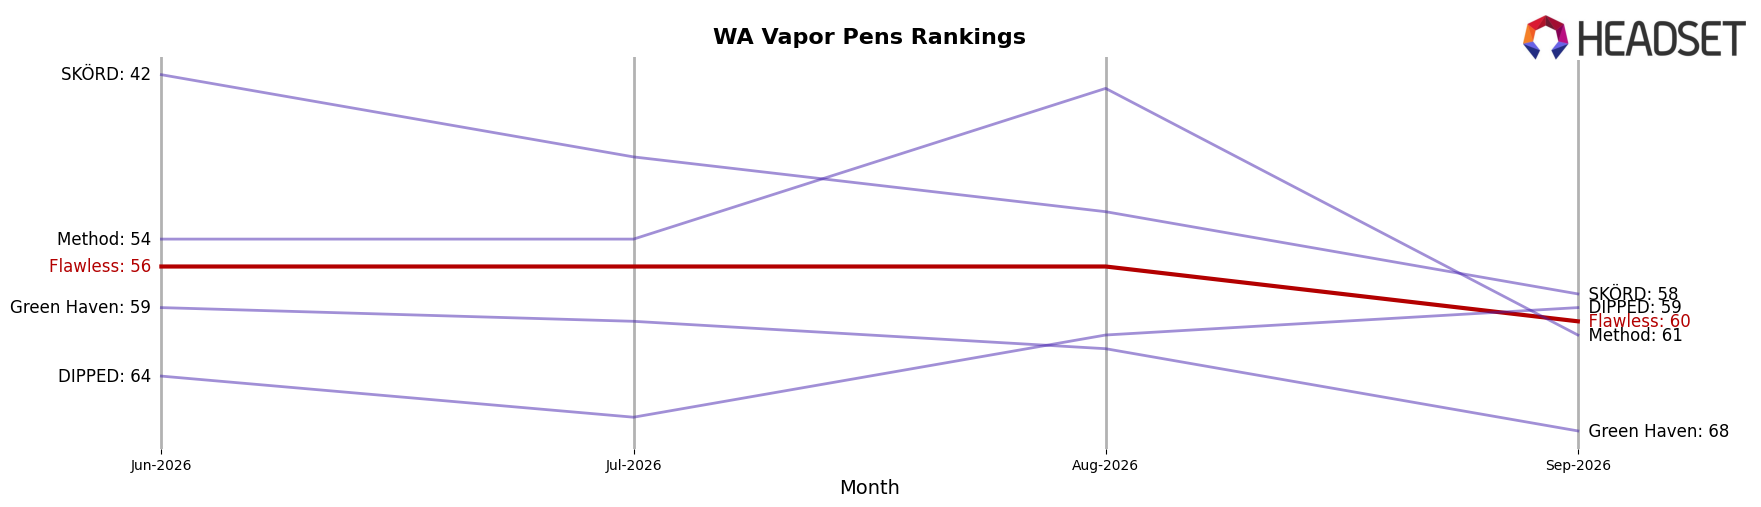
Flawless is ranked #60 in Washington Vapor Pens in September 2026, improving 9 positions from #69 year over year, but slipping 4 spots from its peak #56 in August 2026 and 4 positions from #56 in June 2026, indicating short-term softening against a longer-term climb. Competitive context tightened at the top: Crystal Clear climbed from #3 to #1 while growing sales 26.44%, and Mfused fell from #1 to #2 with a 30.94% sales decline, signaling that upward mobility is available for brands accelerating share even as leaders rotate. With Plaid Jacket moving from #6 to #3 on 23.34% sales growth and Phat Panda sliding from #2 to #5 alongside a 25.08% sales drop, the mix shift favors rank volatility; the implication for Flawless is that its year-over-year rise to #60 sets a floor, but month-to-month slippage from #56 suggests it must convert the broader turnover into consistent rank gains to avoid reversion.
Notable Products
Oil Tanker Infused Pre-Roll 2-Pack (1g) posted the steepest decline at -22.9% and slid to rank 3, while Cleo Infused Pre-Roll 2-Pack (1g) also fell -11.6% to rank 4. In contrast, ATF Pre-Roll 3-Pack (1.5g) surged +53.5% to rank 2, narrowing the gap with White Cherries Pre-Roll 3-Pack (1.5g) at rank 1 with +14.6% growth and $3,961 in September 2026 sales. Five of the top ten are Pre-Roll SKUs concentrated in both value 3-packs and infused 2-packs, pointing to a barbell within the segment where entry multi-packs gain share as some infused formats retrench.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

