

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Herb - Made in New York is stocked at 100 licensed dispensaries across New York, with the deepest coverage in New York, Brooklyn, Queens, Staten Island, and The Bronx. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
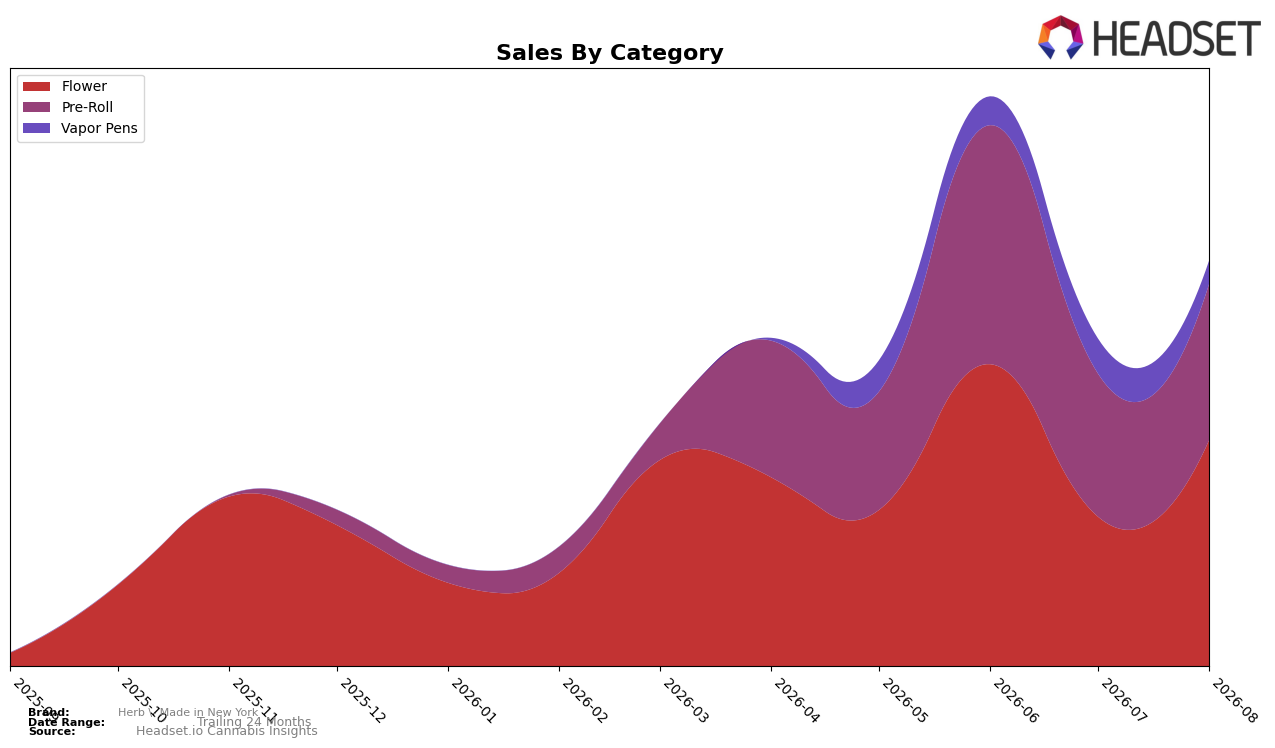
In August 2026, Herb - Made in New York concentrated 55.77% of sales in Flower with a 50.99% month-over-month lift, while Pre-Roll held 38.52% share on a 9.11% MoM increase; Vapor Pens fell to 5.72% share on a -33.50% MoM decline. The Flower push aligns with a category rank of 33 in New York and a current average price of $14.22 against category-level average price points of $25.36 (Flower) and $8.31 (Pre-Roll), implying a deliberate volume-led mix that leans into Flower momentum while de-emphasizing Vapor Pens exposure. Thesis: the brand is pivoting toward higher-share, faster-growing Flower and steady Pre-Rolls while intentionally sacrificing Vapor Pens share to consolidate rank in core inhalables.
The mix shift—up 50.99% MoM in Flower alongside a 9.11% MoM rise in Pre-Roll, versus a -33.50% MoM contraction in Vapor Pens—positions Herb - Made in New York to compete more directly on Flower depth where it sits at rank 33, while keeping a price ladder that spans $8.31 to $29.36 but concentrates volume near $14.22. With 94.28% of sales now in Flower and Pre-Rolls and only 5.72% in Vapor Pens, the brand signals a focus on accessible inhalables over premium Vape spend, implying future gains will depend on sustaining Flower share above 55% and nudging rank upward through repeat-driven assortment rather than breadth expansion. Thesis: the brand is trading premium-adjacent Vape variability for scale in Flower and Pre-Rolls to improve rank efficiency in New York.
Competitive Landscape
Herb - Made in New York sits at rank #33 in August 2026, up 9 positions from #42 in May 2026, while still 9 spots below its peak of #24 in June 2026; this places the brand outside the top 30 as Find. holds #1 after a 6-position YoY climb and Grassroots sits at #4 after a 14-position YoY rise with sales up 88.4%. Against this backdrop, Rolling Green Cannabis remains at #5 despite a 36.1% YoY sales decline, indicating incumbents can maintain top-5 presence even with contraction, whereas Herb - Made in New York’s 9-rank improvement over three months without a top-20 breakthrough suggests mid-pack momentum that will likely stall unless share gains accelerate beyond competitors’ double-digit YoY advances.

Notable Products
Sour Diesel Pre-Roll (1g) posted the largest month-over-month move in August 2026 at +235.5% and reached rank 2, while Tropicana Cookies Hash Infused Pre-Roll (1g) fell -39.6% to rank 6, indicating a decisive consumer pivot within the Pre-Roll set. Lemon Haze Infused Pre-Roll (1g) rose +80.3% at rank 3, and Runtz Pre-Roll (1g) climbed +141.4% at rank 4, with four of the top five slots held by Pre-Roll SKUs even as Gelato Pre-Roll (1g) held rank 1 with $57,611 in sales. The clustering of Pre-Rolls in ranks 1 through 4 alongside a single sharp decliner at rank 6 implies a strategy consolidating around high-velocity non-infused and select infused Pre-Rolls, with Flower relegated to ranks 5 through 10 as a stabilizer rather than a growth engine.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

