

Aug-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
LunchBox is stocked at 55 licensed dispensaries across Arizona, with the deepest coverage in Phoenix, Mesa, Tucson, Apache Junction, and Chandler. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
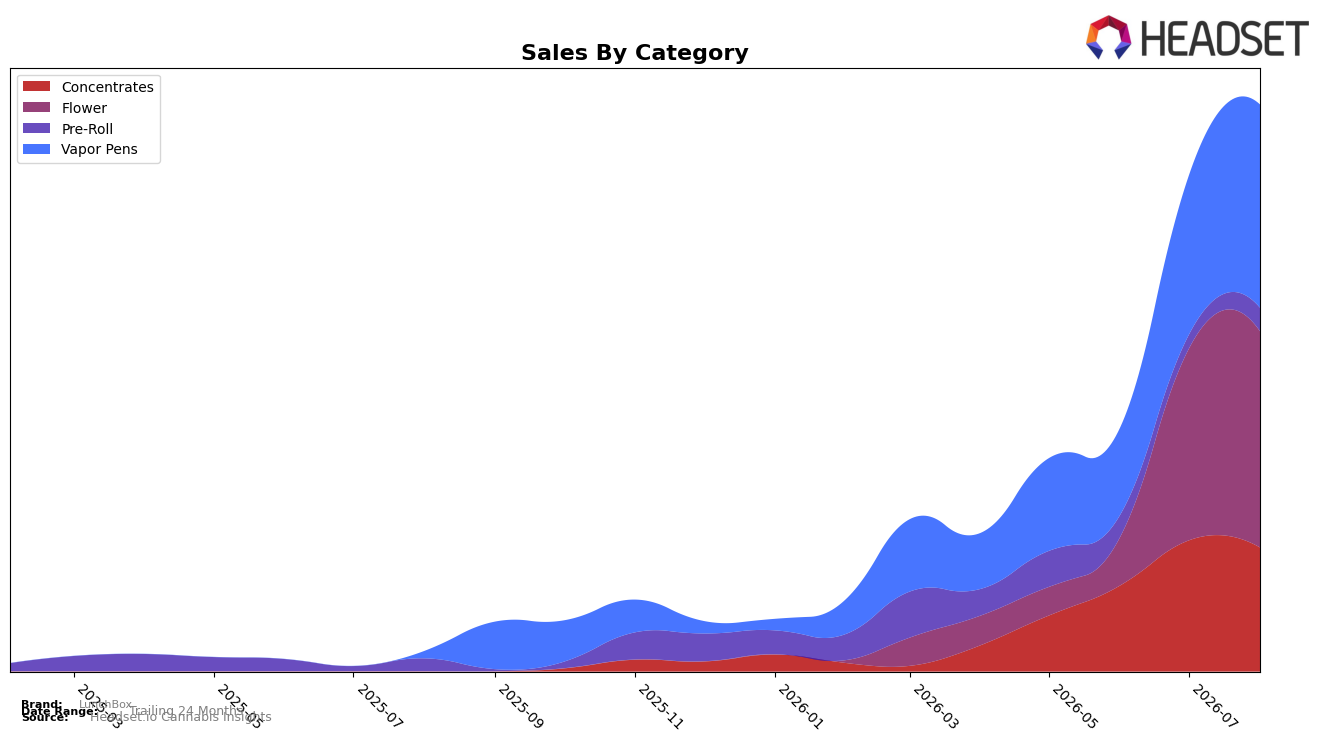
In August 2026, LunchBox’s mix concentrated in Flower at 38.14% share and Vapor Pens at 35.85% share, with Concentrates at 21.88% and Pre-Roll at 4.12%. Month over month, Vapor Pens expanded 27.51% while Flower rose 12.69%, whereas Concentrates contracted 5.47% and Pre-Roll surged 69.12%; year over year, Vapor Pens climbed 2,711.74% and Pre-Roll increased 84.44%. With LunchBox ranked 34 in Flower in Arizona and average price up 4.31% alongside a Flower average price of $41.61, the pattern implies the brand is leaning into higher-ticket inhalables while reallocating demand from Concentrates toward faster-growing pen and pre-roll formats.
The acceleration in Vapor Pens at 35.85% share paired with a 27.51% MoM gain, versus a 5.47% MoM decline in Concentrates and only a 12.69% MoM lift in Flower, implies positioning is shifting toward convenience-led inhalables and away from extract-heavy use occasions. With Pre-Roll’s 69.12% MoM jump but just 4.12% share and a $37.16 average price against the brand’s $34.00 overall average, and a Flower rank of 34 in Arizona, the mix suggests LunchBox is trading up in price while concentrating where rank headroom exists, signaling a strategy to capture velocity in pens and pre-rolls to elevate visibility beyond mid-pack Flower placement.
Competitive Landscape
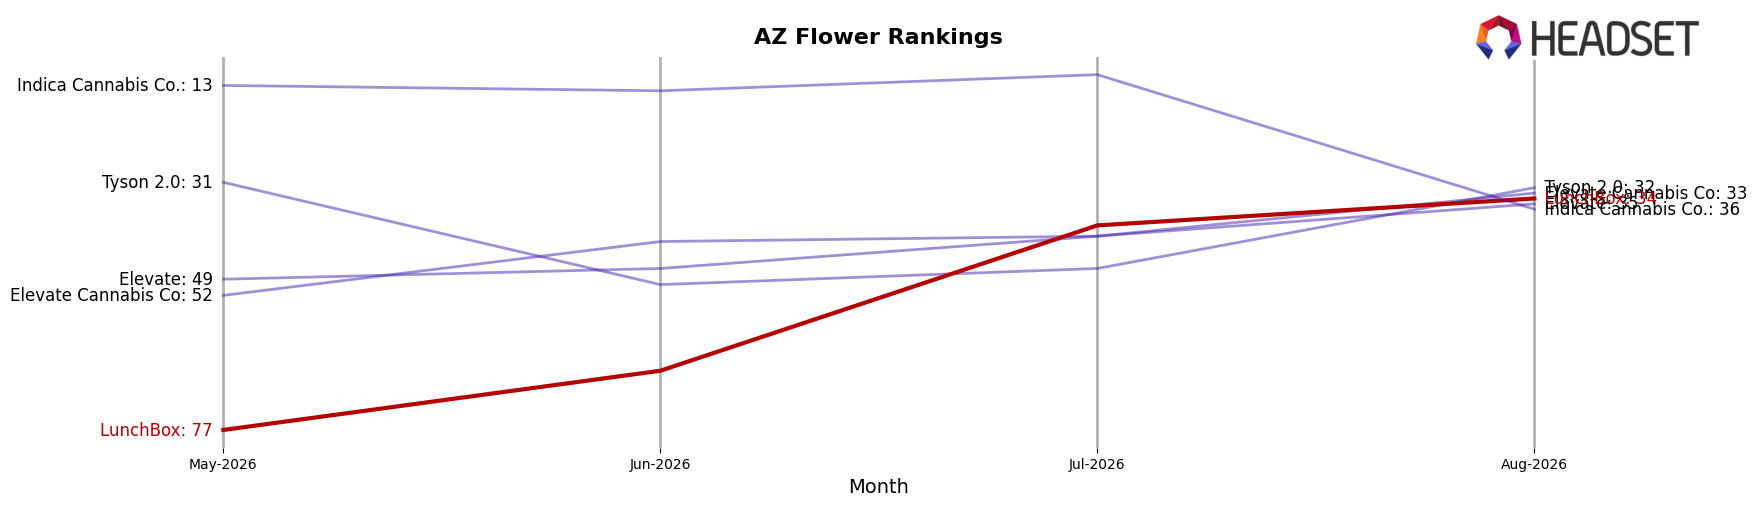
LunchBox sits at rank #34 in AZ Flower with a 43-position climb from #77 in May 2026 to #34 in August 2026, and it reached a new peak rank of #34 in August 2026; compared directionally, Just Flower held #1 while The Pharm moved from #21 year over year to #5 alongside a 289.6% sales YoY change, indicating that LunchBox’s momentum is recent and steep but it is scaling amid faster-moving leaders. With Find. at #2 after improving from #3 year over year and Mohave Cannabis Co. sliding from #2 to #3 while still posting a 12.7% sales YoY increase, the competitive set’s upward pressure implies LunchBox’s rank trajectory is catch-up acceleration rather than consolidation, signaling a need to convert short-term rank gains into sustained mid-tier presence.
Notable Products
Cherryzona Lemonade Smalls (14g) posted the largest movement in August 2026 with a 250.2% month-over-month surge into rank 3, while Okashi (14g) fell 46.9% yet held rank 1, indicating volatility concentrated within Flower where two of the top four SKUs sit. Sour Grapes Caviar Hash Rosin Disposable (0.5g) climbed 59.9% to rank 2 as Cherryzona Lemonade Live Rosin Disposable (0.5g) dropped 33.3% to rank 8, implying consumer trade-up toward premium vapor SKUs tied to fewer price-sensitive flavors. Strawberry Pie Caviar Live Hash Rosin Disposable (0.5g) advanced 50.6% to rank 7 as Papaya Live Hash Rosin Caviar (1g) slipped 7.8% at rank 9, and the product mix suggests LunchBox is pivoting from bulk Flower reliance toward higher-velocity caviar/live rosin formats despite uneven performance within Vapor.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

