

Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Is this your brand?
See your full sales and distribution data: where you sell, how you're priced, and how you rank against the brands next to you on the shelf.
See your brand's dataCarry this brand in your store?
Headset Retailer is free. Connect your POS and see what's selling and what's sitting.
Sign up freeWhere to Buy
Young Buck is stocked at 61 licensed dispensaries across Ohio, with the deepest coverage in Columbus, Cincinnati, Akron, Athens, and Dayton. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
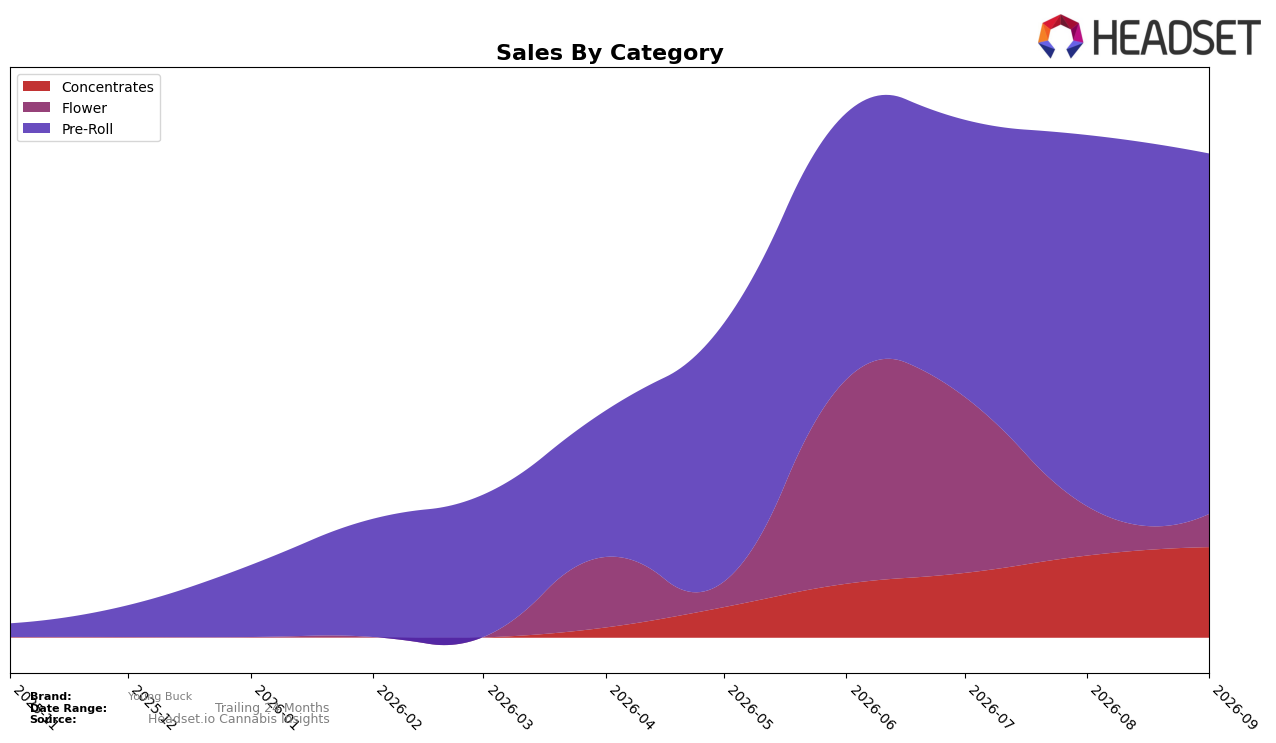
Young Buck’s September 2026 mix is concentrated in Pre-Roll at 74.50% share with a month-over-month decline of 2.94%, while Concentrates hold 18.68% share with a 10.32% MoM increase and Flower sits at 6.82% share with a 32.73% MoM drop. Within the Pre-Roll category in Ohio, the brand sits at rank 18, and the overall average price across the portfolio is $12.93, compared to category-level average prices of $10.69 in Pre-Roll and $27.69 in Concentrates. The pattern implies a tilt toward higher-ticket Concentrates offsetting volume softness in Pre-Roll, while a sharp contraction in Flower indicates de-prioritization of that SKU family relative to categories where the brand can maintain rank and price alignment.
The mix shift—10.32% MoM growth in Concentrates alongside a 2.94% MoM pullback in Pre-Roll and a 32.73% MoM decline in Flower—suggests Young Buck is consolidating around a two-tier strategy: value-access Pre-Rolls to sustain placement at rank 18 in Ohio and margin-accretive Concentrates to lift revenue density above the $12.93 portfolio average. With Pre-Roll carrying 74.50% of sales and Concentrates nearing one-fifth at 18.68%, the implication is that stability in overall performance will hinge on pricing discipline in Pre-Roll near the $10.69 mark and selective expansion in Concentrates where the $27.69 average price can absorb volatility from the 6.82% Flower base.
Competitive Landscape
Young Buck sits at rank #18 in OH Pre-Roll for September 2026, improving 6 positions from #24 in June 2026 and near its peak at #17 in August 2026, while year-over-year rank is unavailable. In contrast, Jeeter holds #1 and Buckeye Relief is #2 with a +1 YoY rank change and a 54.7% YoY sales increase, and Pure Ohio Wellness climbed to #3 with a +6 YoY rank change alongside 586.6% YoY sales growth; additionally, Dogwalkers advanced to #4 with a +4 YoY rank change as its sales rose 178.8%. The movement from #24 to #18 in three months and proximity to the peak at #17 imply Young Buck is stabilizing in the mid-tier but must outpace rapid climbers to secure a sustainable top-15 position.

Notable Products
LMN G Pre-Roll (0.5g) posted the largest month-over-month gain at +67.6% while climbing into rank 4, and Lemon G Pre-Roll (0.5g) followed with +64.0% at rank 3. In contrast, 91 Royale Pre-Roll 5-Pack (2.5g) fell -30.9% to rank 8 as Lemon G Pre-Roll 5-Pack (2.5g) contracted -41.3% at rank 10, signaling a tilt toward singles over multi-packs. With nine of the top ten in September 2026 concentrated in Pre-Roll formats and Super Buff Cherry #26 Pre-Roll (0.5g) holding rank 1, the mix points to a strategy centered on high-velocity singles, using selective 5-pack support to manage price tiers and basket size.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

