
Sep-2026
Sales
Trend
6-Month
Product Count
SKUs
Avg Price
YoY Sales Change
YoY Price Change


Where to Buy
Rare Headstash is stocked at 22 licensed dispensaries across Nevada, with the deepest coverage in Las Vegas, Reno, Henderson, Jackpot, and North Las Vegas. Search by ZIP code or city below to find the closest one, or filter by product type if you are after a specific format.
Market Insights Snapshot
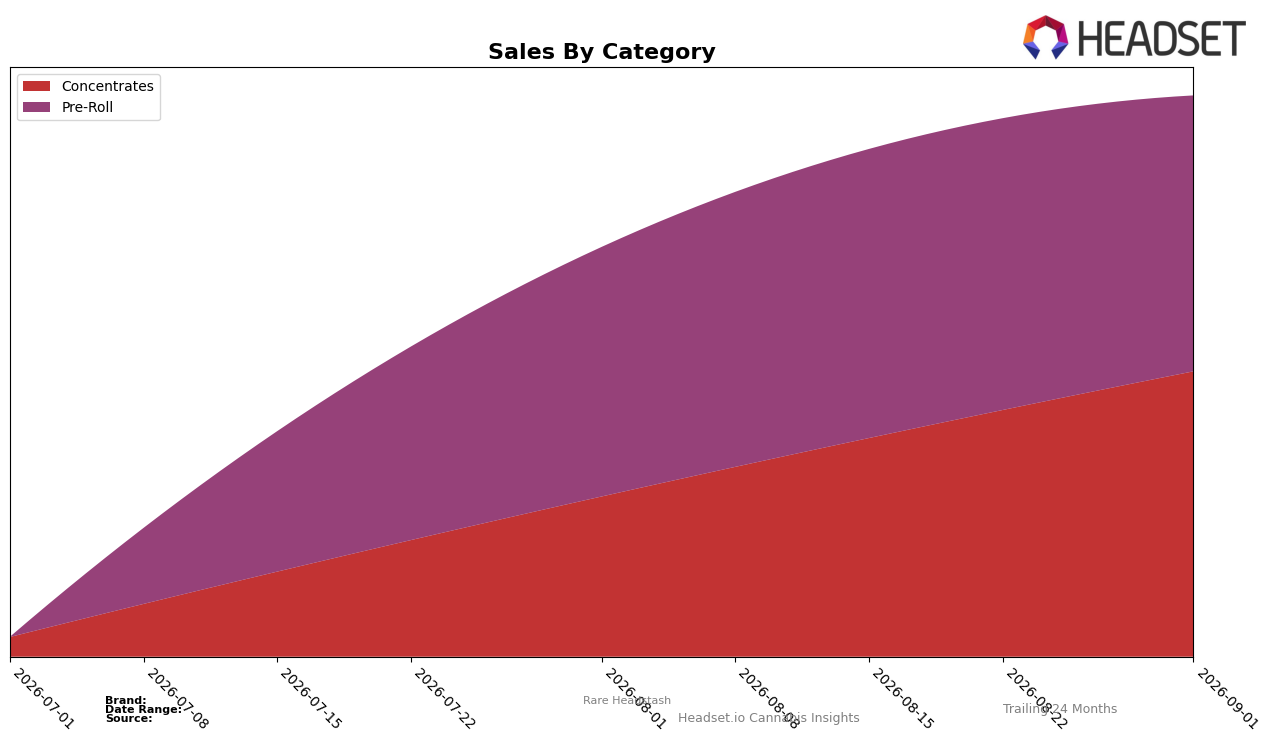
Rare Headstash split its September 2026 sales almost evenly between Concentrates at 50.75% share and Pre-Roll at 49.25% share, but the momentum skewed toward Concentrates with a 64.27% month-over-month rise versus a 9.27% month-over-month increase in Pre-Roll. With Concentrates carrying a lower average price of $17.32 compared to $33.39 in Pre-Roll, mix shifting toward Concentrates likely pulled the overall average price down even as unit velocity rose; the pattern implies Rare Headstash is leaning into volume-driven gains within Concentrates rather than ticket-size expansion in Pre-Roll.
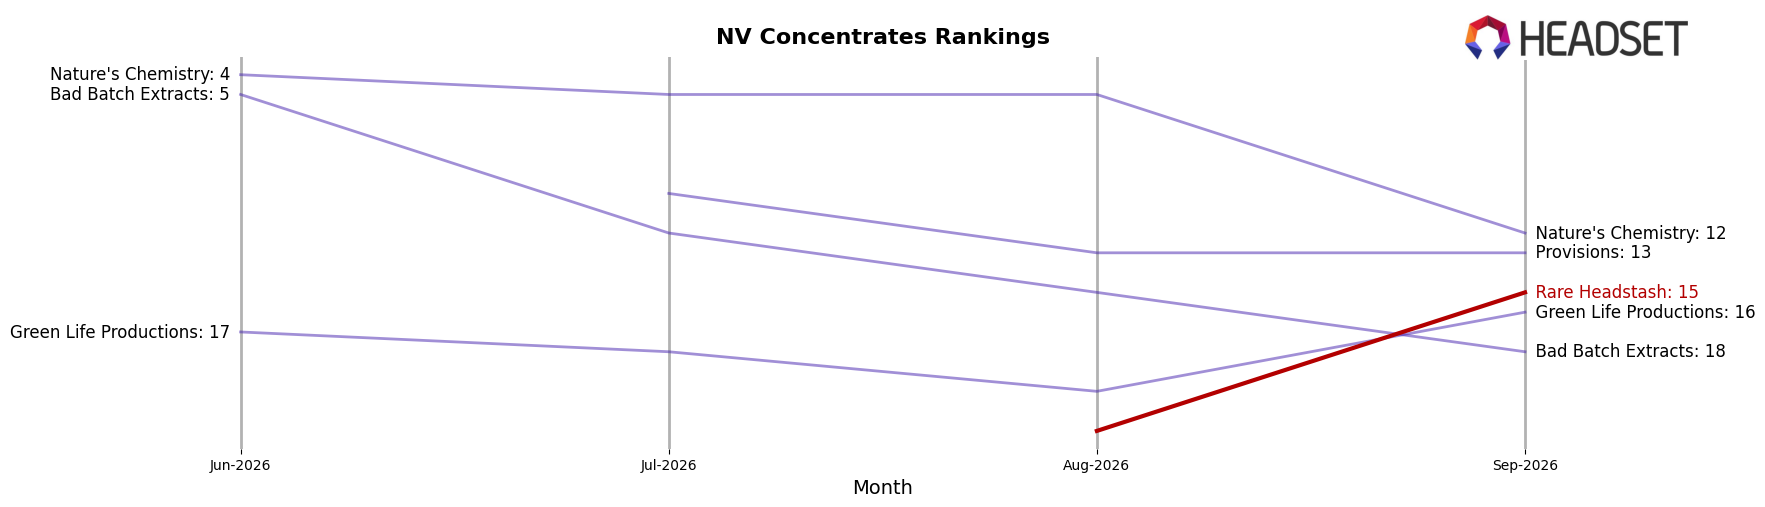
In Nevada, Rare Headstash held rank 15 in Concentrates, and the 64.27% month-over-month lift in that category alongside a 9.27% month-over-month move in Pre-Roll suggests competitive traction is concentrated where the brand already has an established foothold. The combination of a rank at 15 and a 1.50 percentage-point share edge for Concentrates (50.75% vs. 49.25%) indicates positioning that prioritizes depth in Concentrates over breadth in Pre-Roll, implying the near-term route to improved rank is further penetration in Concentrates rather than reallocating toward higher-priced Pre-Roll.
Competitive Landscape
Rare Headstash ranks #15 in NV Concentrates in September 2026, marking a new peak rank of #15 but with no recorded year-over-year rank change available; against this backdrop, Medizin holds #1 despite a -34.8% sales YoY decline while Alternative Medicine Association / AMA sits at #2 with +8.7% YoY growth, indicating Rare Headstash’s entry at #15 coincides with a top-heavy tier where the leader is contracting and #2 is expanding. Further, City Trees moved from #6 to #3 with +16.7% YoY sales and Tsunami Labs (NV) climbed from #10 to #5 with +28.3% YoY sales, while Locals Only Concentrates slipped from #5 to #4 amid -7.4% YoY sales, suggesting upward mobility in the mid-tier is achievable but requires outpacing competitors that are gaining share; the thesis is that Rare Headstash’s current #15 and first-time peak at #15 imply a foothold has been established, yet sustained share gains will depend on converting volatility at the top and mid-tier momentum into rank accretion over the next few months.
Notable Products
Dulce De Uva Live Rosin (1g) posted the standout surge at +97.3% month over month to rank 9 in September 2026, while Dulce De Uva x Dulce De Uva Infused Mini Hash Hole Pre-Roll 2-Pack (1.5g) fell -60.0% to rank 10, indicating sharp divergence within adjacent formats. Honey Banana x Sub Zero Mini Hash Hole Infused Pre-Roll 2-Pack (1.5g) also expanded by +84.5% to rank 5 as Honey Banana x Honey Banana Mini Hash Hole Infused Pre-Roll 2-Pack (1.5g) rose +71.3% to rank 7, and four of the top ten are Pre-Roll SKUs, concentrating gains in infused minis. Sour Diesel Live Rosin Badder (0.05g) in Concentrates edged up +9.0% to rank 1 as Dulce de Uva Live Rosin Badder (1g) declined -19.0% to rank 2, with Concentrates still anchoring the highest rank positions despite Pre-Roll volatility. The mix points to a dual-track strategy where Concentrates secure rank leadership while select infused Pre-Rolls capture outsized MoM spikes, suggesting portfolio emphasis on high-velocity novelty within a stable core; September 2026 revenue was $49,883.
Top Selling Cannabis Brands






Data for this report comes from real-time sales reporting by participating cannabis retailers via their point-of-sale systems, which are linked up with Headset’s business intelligence software. Headset’s data is very reliable, as it comes digitally direct from our partner retailers. However, the potential does exist for misreporting in the instance of duplicates, incorrectly classified products, inaccurate entry of products into point-of-sale systems, or even simple human error at the point of purchase. Thus, there is a slight margin of error to consider. Brands listed on this page are ranked in the top twenty within the market and product category by total retail sales volume.

